Market Research Briefing · Aerospace & Defense
Military Electro-Optical & Infrared (EOIR) Systems Market Seeing first, deciding faster: a USD 24.65 bn sensing opportunity by 2030 — global outlook,
growth levers and competitive moves
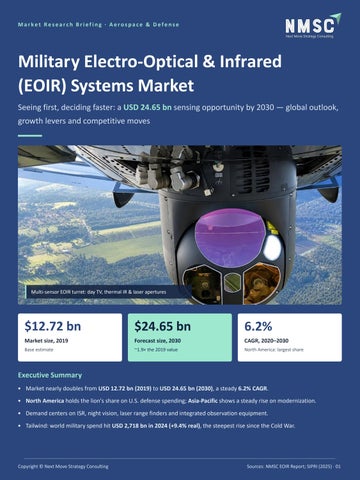
Multi-sensor EOIR turret: day TV, thermal IR & laser apertures
$12.72 bn
$24.65 bn
6.2%
Market size, 2019
Forecast size, 2030
CAGR, 2020–2030
Base estimate
~1.9× the 2019 value
North America: largest share
Executive Summary • Market nearly doubles from USD 12.72 bn (2019) to USD 24.65 bn (2030), a steady 6.2% CAGR. • North America holds the lion's share on U.S. defense spending; Asia-Pacific shows a steady rise on modernization. • Demand centers on ISR, night vision, laser range finders and integrated observation equipment. • Tailwind: world military spend hit USD 2,718 bn in 2024 (+9.4% real), the steepest rise since the Cold War.
Copyright © Next Move Strategy Consulting
Sources: NMSC EOIR Report; SIPRI (2025) · 01
01 · Market Landscape
A budget-backed market set to nearly double by 2030
6.2%
Market size trajectory (USD bn) 2019 & 2030 per NMSC; interim years interpolated at 6.2% CAGR
CAGR, 2020–2030 24.7
Steady, budget-linked compounding
23.2 21.9 20.6
12.7
13.5
14.4
15.2
17.2
16.2
18.3
19.4
+$11.9 bn Incremental value 2019→2030 1.94× growth multiple
North America Lion's share of market U.S. = ~37% of world military spend (2024) '19
'20
'21
'22
'23
'24
'25
'26
'27
'28
'29
'30
Industry ecosystem & segmentation By Type
By System
By Platform
By Geography
▸ Image Intensification ▸ Infrared ▸ Laser
▸ Imaging ▸ Non-Imaging
▸ Air-based ▸ Land-based ▸ Sea-based
NVDs, thermal sensors, range
distance-measuring devices
▸ North America ▸ Europe ▸ Asia-Pacific ▸ RoW
Cameras & IR imagers vs. laser /
finders
UAV / aircraft turrets, soldier &
& vehicle sights, naval EO
Incl. Israel, Qatar, Saudi Arabia
Key landscape insights • EOIR fuses visible and infrared sensing so forces operate in darkness and
low light, central to ISR battlefield awareness. • Demand pull from enhanced equipment: laser range finders, lenses, integrated observation gear. • Headwinds: high system cost, stagnant product lifecycles, limited extreme-weather performance. • Investor read: mid-single-digit growth in a high-barrier, governmentfunded market.
Copyright © Next Move Strategy Consulting
Sources: NMSC EOIR Report; SIPRI (2025) · 02
02 · Growth Drivers & Opportunities
Rising budgets and drone warfare pull EOIR demand forward $2,718 bn
5% GDP
90+
~2.2 mn
World military spend 2024,
NATO defense & security
Countries operating military
FPV drones built in Ukraine in
+9.4% real (SIPRI)
target by 2035 (3.5% core)
drones, each a payload buyer
Ukraine in 2024, each needing
(CNAS)
needing EO cameras
Regional growth opportunity map
Military spend 2024, USD, real growth (SIPRI)
2
1 4
3
1 · North America
2 · Europe
3 · Middle East
4 · Asia-Pacific
$997 bn
$693 bn
$243 bn
$629 bn
U.S. spend, +5.7%. Holds the
+17%: steepest regional rise;
+15%; Israel +65% to $46.5 bn
+6.3%; steady EOIR rise on
the market's lion share
rise; Germany +28%
modernization
High-growth segments: contract evidence Night vision (I² & IR)
Air-based ISR payloads
Laser systems
U.S. Army ENVG-B: L3Harris $263 mn order
MQ-9 Reaper MTS-B EO/IR turret: Raytheon
Elbit ~$200 mn Israeli MoD high-power laser
order (Jan 2025); BiNOD awards ~$1.3 bn
$191 mn award; drone proliferation widens
power laser contract (Iron Beam); laser
bn across 3 vendors
the buyer base
designation on ISR turrets
Opportunity
Watch-outs
R&D to boost operational capacity plus adoption of advanced
High system cost, stagnant product lifecycle, limited extreme-weather
technologies and sensors
performance
Copyright © Next Move Strategy Consulting
Sources: NMSC; SIPRI; NATO; CNAS; company releases · 03
03 · Competitive Scenario
Consolidated primes lead; M&A is reshaping the reshaping the supplier base Competitive positioning matrix
Leading companies
Indicative, based on company portfolios & disclosed activity
NMSC-profiled players (current entity)
PLATFORM SPECIALISTS
INTEGRATED PRIMES
L3Harris
Integration level: component → system →
GA-ASI
L3Harris· Harris + L-3 + Exelis BAE Systems· + Ball Aerospace Leonardo / Leonardo DRS· ex-Finmeccanica,
Elbit Systems
BAE Systems
DRS Teledyne FLIR· ex-FLIR Systems
IAI Leonardo DRS Airbus (EADS)
Elbit Systems· Israel Israel Aerospace Ind.· record 2024 Airbus· ex-EADS
Teledyne FLIR
General Dynamics
General Atomics ASI General Dynamics · Leidos
Excelitas
Leidos
Excelitas · EOIR Technologies
EOIR Technologies SENSOR SPECIALISTS
DIVERSIFIED SUPPLIERS
Portfolio breadth: EOIR-focused → multi-domain prime →
Disclosed EOIR-relevant M&A value (USD bn)
Company releases / SEC filings
8.0
Teledyne → FLIR (2021)
5.5
BAE → Ball Aerospace (2024)
4.75
Harris → Exelis (2015) Elbit → L3Harris Night Vision (2019)
0.35
All-stock: L3Harris merger (2019) · Leonardo DRS–RADA (2022)
Expansion
Partnerships & programs
M&A & portfolio reshaping
• Elbit ~$1.4 bn European modernization
• IVAS: Microsoft OTA capped at $21.88 bn;
• Harris + L3 all-stock merger forms
contract (2025) • Elbit ~$270 mn ISR & targeting payloads • Teledyne FLIR Black Hornet 4: up to ~$91 mn U.S. Army
Copyright © Next Move Strategy Consulting
Anduril taking over production (2025) • BiNOD: multi-vendor awards to L3Harris, Elbit, Photonis (~$1.3 bn)
L3Harris (Jun 2019) • Leonardo DRS–RADA merger adds advanced sensing (Nov 2022) • Divest-to-focus: night vision sold to Elbit
Sources: NMSC; company releases; SEC; CRS · 04
04 · Let's Connect
Thank You Connect with our Aerospace & Defense team for in-depth EOIR insights, custom segment
segment forecasts and strategic guidance on your next move.
WEBSITE
PHONE
www.nextmsc.com
+1 857 758 5017
info@nextmsc.com
Click here for the complete report
176 pages · 92 tables · 50 figures →
FOLLOW US
YouTube
Market sizing · Competitive intelligence · Custom research for investors and B2B leaders
Copyright © Next Move Strategy Consulting
www.nextmsc.com · 05