Market Research Briefing · Global Forecast 2022 –2030
Military Aviation Sensors & Switches Market
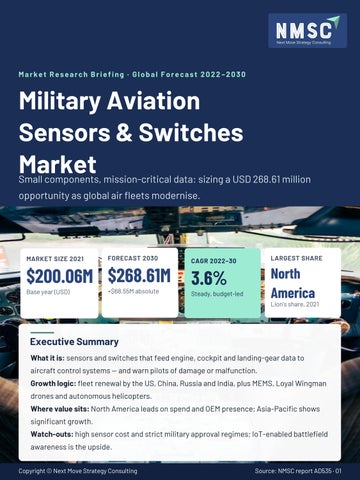
Small components, mission-critical data: sizing a USD 268.61 million opportunity as global air fleets modernise.
MARKET SIZE 2021
FORECAST 2030
$200.06M $268.61M Base year (USD)
+$68.55M absolute
LARGEST SHARE
CAGR 2022–30
North America
3.6% Steady, budget-led
Lion's share, 2021
Executive Summary What it is: sensors and switches that feed engine, cockpit and landing-gear data to aircraft control systems — and warn pilots of damage or malfunction.
Growth logic: fleet renewal by the US, China, Russia and India, plus MEMS, Loyal Wingman drones and autonomous helicopters. Where value sits: North America leads on spend and OEM presence; Asia-Pacific shows significant growth. Watch-outs: high sensor cost and strict military approval regimes; IoT-enabled battlefield awareness is the upside. Copyright © Next Move Strategy Consulting
Source: NMSC report AD535 · 01
02 · Market Landscape
A steady, defence-backed niche compounding at 3.6% a year Market size, USD million Global, 2021 base vs 2030 forecast
What the market covers Devices installed across the engine, cockpit and landing gear that capture data, relay it to the control system and alert pilots to damage or malfunction. Pressure, position, proximity, temperature, speed and angle-of-attack sensors, plus switches.
Industry ecosystem — how the report segments the market PRODUCT TYPE
APPLICATION
PLATFORM
TECHNOLOGY
Sensors: proximity,
Combat
Fixed-wing aircraft
Analog
position, pressure,
Surveillance &
Rotary-wing aircraft
Digital
temperature, angle of
reconnaissance
Unmanned platforms
Hybrid
attack, speed
Training aircraft
Switches
Transport aircraft UAVs
GEOGRAPHY N. America · Europe · APAC · RoW
Value adds USD 68.55M between 2021 and 2030 — a low-volatility market tied to multi-year procurement cycles. North America held the lion's share in 2021 and is expected to stay dominant through 2030. Report depth: 403 pages, 288 tables, 233 figures across product, application, platform and technology. Copyright © Next Move Strategy Consulting
Source: NMSC report AD535 · 02
03 · Growth Drivers & Opportunities
Fleet renewal and digital avionics pull demand forward Demand drivers Fleet modernisation
Technology step-change
US, China, Russia and India are renewing fleets — e.g. Russia's first modernised Su-34M bombers delivered in July 2022.
MEMS sensors, Loyal Wingman drones and easyto-fly autonomous helicopters raise sensor content per platform.
IoT battlefield awareness
Rising defence budgets
IoT integration to record and analyse in-flight data is flagged as the key lucrative opportunity for suppliers.
World military spend hit USD 2,887B in 2025 (+2.9%), the 11th straight year of growth (SIPRI).
Regional opportunity map NORTH AMERICA · Leader
EUROPE · Re-arming
Lion's share in 2021. US FY2023
Spend $864B in 2025 (+14%);
request: $773B, incl. $194B Air
Germany $114B (+24%).
& Space Force.
ASIA-PACIFIC · Growth China FY2022 budget $230B (+7.1%). India plans 114 fighters,
REST OF WORLD · Selective
96 built locally.
Middle East spend $218B in 2025 (+0.1%).
Segments aligned with the report's growth drivers Unmanned platforms
Digital & MEMS sensing
Combat & ISR
Loyal Wingman drones &
Lighter, data-rich sensors for
Upgraded reconnaissance pods,
autonomous helicopters
IoT-linked aircraft
IRST and datalinks
Copyright © Next Move Strategy Consulting
Sources: NMSC AD535; SIPRI 2026 · 03
04 · Competitive Scenario
A consolidating supply base: integrators reshape, specialists buy scale Competitive positioning matrix
Leading companies
Illustrative · based on announced 2021–26 activity ACQUISITIVE SPECIALISTS
CONSOLIDATING MAJORS
Honeywell International Thales Group
Inorganic / restructuring activity →
Raytheon (RTX) TransDigm
Safran
Meggitt / Parker
AMETEK
Safran Group TE Connectivity Honeywell
AMETEK Inc. Meggitt PLC
Eaton RTX
Curtiss-Wright
TE Conn.
NICHE SPECIALISTS
Curtiss-Wright TransDigm Group Eaton · Crane A&E
Thales Crane
GE Aerospace
GE Aerospace ORGANIC INTEGRATORS
Component specialistPortfolio scope →Systems integrator
Stellar Tech · ITT · Unison Players focus on R&D, product innovation and industrial collaborations to widen portfolios and geographic reach.
Key strategies in play M&A
Partnerships & contracts
Product innovation
Portfolio restructuring
Parker completes Meggitt (~£6.3B, Sep 2022) · TransDigm buys RTX's Simmonds Precision fuel & proximity sensing (~$765M, 2025) · Safran acquires Collins actuation & flight controls ($1.8B EV, 2025) Safran–Baykar optronic sensor & navigation partnership (May 2026) · Collins CEC design-agent award, up to $904M (Jan 2025) · AMETEK–Kellstrom aftermarket distribution extension (Feb 2020) Honeywell all-electric cabin-pressure control & monitoring (Jan 2021) and quantumsensor navigation contracts (Jul 2025) · Boeing upgraded IRST sensors on F-15 (Jan 2021)
Crane separates Aerospace & Electronics into Crane NXT (Apr 2023) · Honeywell Aerospace spin-off begins trading on Nasdaq as HONA (Jun 2026)
Copyright © Next Move Strategy Consulting
Sources: NMSC AD535; company releases · 04
05 · Strategic Outlook
Budget tailwinds are durable — where each stakeholder should focus WORLD SPEND 2025
Top military spenders, 2025 (USD B)
$2,887B
The demand pool behind aircraft procurement · SIPRI
954
US
336 +7.4%
China Russia
+2.9% · 11th year of growth
ASIA & OCEANIA
$681B
190 +5.9%
+8.1% · biggest rise since 2009
Germany
114 +24%
India
92.1 +8.9%
EUROPE (INCL. RUSSIA)
$864B
US −7.5% in 2025 as new Ukraine aid ended; 2026 approved budget
+14% · sharpest since Cold War
exceeds $1T.
Restraints to price in
Upside levers
• High unit cost of aviation-grade sensors
• IoT-enabled data capture for battlefield
• Stringent government approval and clearance
awareness
rules for military products
• Local-build programmes, e.g. India's 96 of 114
• Long qualification cycles favour incumbents
jets • Sensor-heavy unmanned & collaborative aircraft
Implications by stakeholder Investors
Internal strategy
B2B decision-makers
3.6% CAGR signals defensive, contract-backed revenue. Active M&A (Meggitt, Simmonds) shows strategic buyers paying for sensor IP.
Prioritise North America for scale and Asia-Pacific for growth; build digital/MEMS and IoT-ready portfolios.
Supplier ownership is shifting — re-check qualification, aftermarket and second-source plans after each deal.
Copyright © Next Move Strategy Consulting
Sources: NMSC AD535; SIPRI 2026 · 05
06 · Let's Connect
Thank You Connect with our analysts for in-depth market sizing, segment forecasts and strategic guidance on the Military Aviation Sensors & Switches Market.
→
Click here for the complete report WEBSITE
PHONE
www.nextmsc.com
+1 857 758 5017
info@nextmsc.com
Follow Us LinkedIn
YouTube
Inside the full report • 403 pages · 288 tables · 233 figures • Forecasts 2022–2030 by product, application, platform, technology
• 15 country-level breakdowns across 4 regions • Profiles of 15 key players
Copyright © Next Move Strategy Consulting
06