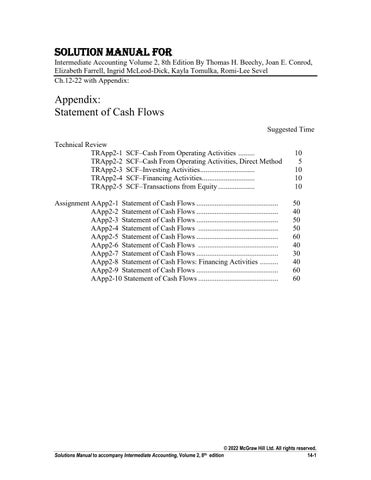
SOLUTION MANUAL FOR Intermediate Accounting Volume 2, 8th Edition By Thomas H. Beechy, Joan E. Conrod, Elizabeth Farrell, Ingrid McLeod-Dick, Kayla Tomulka, Romi-Lee Sevel Ch.12-22 with Appendix:
Appendix: Statement of Cash Flows Suggested Time Technical Review TRApp2-1 SCF–Cash From Operating Activities ......... TRApp2-2 SCF–Cash From Operating Activities, Direct Method TRApp2-3 SCF–Investing Activities .............................. TRApp2-4 SCF–Financing Activities............................. TRApp2-5 SCF–Transactions from Equity ....................
10 5 10 10 10
Assignment AApp2-1 Statement of Cash Flows ............................................. AApp2-2 Statement of Cash Flows ............................................. AApp2-3 Statement of Cash Flows ............................................. AApp2-4 Statement of Cash Flows ............................................ AApp2-5 Statement of Cash Flows ............................................. AApp2-6 Statement of Cash Flows ............................................ AApp2-7 Statement of Cash Flows ............................................. AApp2-8 Statement of Cash Flows: Financing Activities .......... AApp2-9 Statement of Cash Flows ............................................. AApp2-10 Statement of Cash Flows ............................................
50 40 50 50 60 40 30 40 60 60
© 2022 McGraw Hill Ltd. All rights reserved. Solutions Manual to accompany Intermediate Accounting, Volume 2, 8th edition 14-1
Technical Review Technical Review App2-1 Requirement 1 Operating activities Net earnings ...................................................................................$ 900 Adjustments for items not requiring cash: Depreciation expense ................................................................. 165 Discount amortization ($35 + $15 = $50 vs. 33) ....................... 17 Increase in deferred tax liability .............................................. 60 1,142 Changes in SFP accounts: Decrease in accounts receivable ................................................. 180 Increase in inventory ............................................................... (115) Decrease in accounts payable ..................................................... (60) Increase in interest payable ....................................................... 40 Cash from operating activities ............................................................$1,187
Requirement 2 Cash paid for interest ( -$135 + $40 + $17) ............................................... $ (78) Cash paid for income tax ( - $180 + $60) ............................................... $ (120)
© 2022 McGraw Hill Ltd. All rights reserved. Solutions Manual to accompany Intermediate Accounting, Volume 2, 8th edition 14-2
Technical Review App2-2 Operating Activities Cash from customers ($3,750 + $180) ....................................... $3,930 Cash paid for materials and labour (-$1,500 - $870 - $115 - $60) (2,545) Cash paid for income tax (-$180 + $60) .................................... (120) Cash from operating activities .............................................
$1,265
© 2022 McGraw Hill Ltd. All rights reserved. Solutions Manual to accompany Intermediate Accounting, Volume 2, 8th edition 14-3
Technical Review App2-3 (in 000‘s) Category
Description
Investing Operating
Sold FVTPL investment Change in FVTPL investment; deduct unrealized amount included in earnings ($800-$60 sold = $740 vs. $1,200) Sold equipment Bought equipment ($1,600 - $200 = $1,400 vs. $2,120)
$ 60 (460)
Depreciation expense: add back non-cash expense ($920 – ($200 - $20)) = $740 vs. $1,080
340
Investing Investing Operating
Amount
48 (720)
Note: The change in fair value of FVTOCI investments of $120 does not change cash or earnings; it would be an element of AOCI in equity.
© 2022 McGraw Hill Ltd. All rights reserved. Solutions Manual to accompany Intermediate Accounting, Volume 2, 8th edition 14-4
Technical Review App2-4
Category
Description
Operating Financing Operating
Earnings Retired bond payable $750 x 1.05% Loss on bond retirement: add back non-cash loss $787.5 paid vs. ($750 - $90; see below) carrying value Discount amortization: add back non-cash expense $30 amortization is given, Discount account: ($210 - $30 (given) - $90 for retired bond (to balance) = $90 closing balance Repayment of lease liability ($540 - $495) Issued common shares Dividends paid ($1,620 + $1,500 = $3,120 vs. $1,830)
Operating
Financing Financing Financing or Operating
Amount $
1,500 (787.5) 127.5 30
(45) 210 (1,290)
Note: The lease recognized at inception, both the increase in lease liability and leased asset of $540, constitutes a non-cash transaction and is not included on the SCF.
© 2022 McGraw Hill Ltd. All rights reserved. Solutions Manual to accompany Intermediate Accounting, Volume 2, 8th edition 14-5