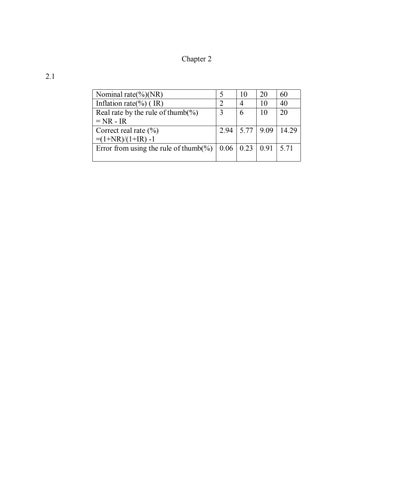
Chapter 2 2.1 Nominal rate(%)(NR) Inflation rate(%) ( IR) Real rate by the rule of thumb(%) = NR - IR Correct real rate (%) =(1+NR)/(1+IR) -1 Error from using the rule of thumb(%)
5 2 3
10 4 6
20 10 10
60 40 20
2.94 5.77 9.09 14.29 0.06 0.23 0.91 5.71
Chapter 3 FINANCIAL STATEMENTS, TAXES AND CASH FLOW 3.1.
Rs. in million A. CASH FLOW FROM OPERATING ACTIVITIES PROFIT BEFORE TAX
90
Adjustments for: Depreciation and amortization
30
Finance costs
30
OPERATING PROFIT BEFORE WORKING CAPITAL CHANGES
150
Adjustments for changes in working capital: Trade receivables
-20
Inventories
-20
Trade payables
20
CASH GENERATED FROM OPERATIONS
130
Direct taxes paid
-30
NET CASH FROM OPERATING ACTIVITIES
100
B.CASH FLOW FROM INVESTING ACTIVITIES Purchase of fixed assets
-50
NET CASH USED IN INVESTING ACTIVITIES
-50
C.CASH FLOW FROM FINANCING ACTIVITIES Increase in share capital
20
Increase in long- term debt
-10
Increase in short-term debt
20
Dividend paid
-40
Finance costs
-30
NET CASH FROM FINANCING ACTIVITIES
-40
NET CASH GENERATED
10
(A+B+C)
CASH AND CASH EQUIVALENTS AT THE BEGINNING OF PERIOD
20
CASH AND CASH EQUIVALENTS AT THE END OF PERIOD
30
Chapter 4 ANALYSING FINANCIAL PERFORMANCE
Net profit 4.1.
Return on equity = Equity =
Net profit
Total revenues x
Total revenues
Total assets x
Total assets
Equity
1 =
0.05
x 1.5
x
= 0.25 or 25 per cent 0.3
Debt Note :
Equity = 0.7
So
Total assets
= 1-0.7 = 0.3 Total assets
Hence Total assets/Equity = 1/0.3
4.2.
PBT
=
Rs.40 million PBIT
Times interest earned =
= 6 Interest
So PBIT = 6 x Interest PBIT – Interest = PBT = Rs.40 million 6 x Interest = Rs.40 million Hence Interest = Rs.8 million 4.3 Sales = Rs.7,000,000 Net profit margin = 6 per cent Net profit = Rs.7000000 x 0.06 = 420,000 Tax rate = 60 per cent 420,000 So, Profit before tax = = Rs.1,050,000 (1-.6) Interest charge = Rs.150,000
So Profit before interest and taxes = Rs.1,200,000 Hence 1,200,000 Times interest earned ratio = = 8 150,000
4.4.
CA = 1500 CL = 600 Let BB stand for bank borrowing CA+BB = 1.5 CL+BB 1500+BB =
1.5
600+BB BB = 1200 1,000,000 4.5.
Average daily credit sales =
= 2740 365
If the accounts receivable has to be reduced to 120,000 the ACP must be: 120,000 = 43.8days 2740 Current assets 4.6.
Current ratio =
= 1.5 Current liabilities
Current assets - Inventories Acid-test ratio =
= 1.2
Current liabilities = 800,000 Sales Inventory turnover ratio = = 5 Inventories Current assets - Inventories Acid-test ratio = Current liabilities Current liabilities
Current assets
= 1.2
Inventories
This means
Current liabilities
= 1.2 Current liabilities
Inventories 1.5
-
= 1.2 800,000 Inventories = 0.3 800,000 Inventories = 240,000 Sales = 5 So Sales = 1,200,000 2,40,000
4.7.
Debt/equity = 0.60 Equity = 50,000 + 60,000 = 110,000 So Debt = Short term bank borrowing = 0.6 x 110,000 = Hence Total assets = 110,000+66,000 = 176,000
66,000