Complete Solution Manual for Finance for Executives 5th Edition by Claude Viallet and Gabriel Hawawini Chapter 2-17
Finance For Executives -5th Edition -Chapter 2 Answers to Review Problems
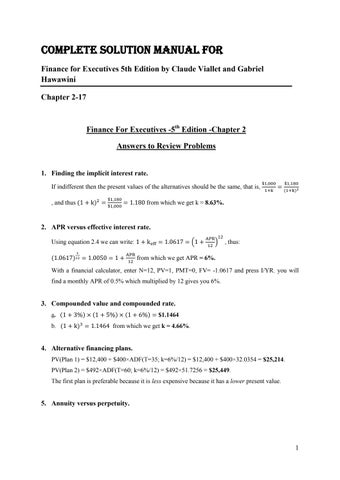
1. Finding the implicit interest rate. If indifferent then the present values of the alternatives should be the same, that is, , and thus
from which we get k = 8.63%.
2. APR versus effective interest rate. (
Using equation 2.4 we can write:
)
, thus:
from which we get APR = 6%. With a financial calculator, enter N=12, PV=1, PMT=0, FV= -1.0617 and press I/YR. you will find a monthly APR of 0.5% which multiplied by 12 gives you 6%.
3. Compounded value and compounded rate. a. b.
$1.1464 from which we get k = 4.66%.
4. Alternative financing plans. PV(Plan 1) = $12,400 + $400×ADF(T=35; k=6%/12) = $12,400 + $400×32.0354 = $25,214. PV(Plan 2) = $492×ADF(T=60; k=6%/12) = $492×51.7256 = $25,449. The first plan is preferable because it is less expensive because it has a lower present value.
5. Annuity versus perpetuity.
1
The future value of the $100 a year for the next 10 years (see formula 2.13 for the future value of an annuity) at the rate ‗k‘ must be equal to the present value, at the end of 10, of a $100 perpetuity at the same rate ‗k‘, hence we have: [
]
, and thus [
]
, from which we get
Using a financial calculator we find k =7.18%. (Enter N=10, PV=1, PMT=0, FV= -2 and press I/YR. you will find 7.18%.)
6. Valuing a loan. a. The loan will generate fixed interest income of $800,000 (8% of $10 million) every year over the next 4 years plus $10 million at the end of the fourth year. Its value is thus the sum of the present value of 4-year, $800,000 annuity at 7 percent (the prevailing market rate) and the present value of $10 million to be received in 4 years at 7 percent: Value of loan = [$800,000×ADF(T=4; k=7%)] + [$10,000,000×DF(T=4; k=7%)] Value of loan = [$800,000×3.3872] + [$10,000,000×0.7629] = $10,338,760. b. Value of loan = [$400,000×ADF(T=8; k=3.5%)] + [$10,000,000×DF(T=8; k=3.5%)] Value of loan = [$400,000×6.8740] + [$10,000,000×0.7594] = $10,343,600.
7. Perpetual cash flows. a.
If the current membership is renewed every year in perpetuity with fees growing at 3 percent annually, its the present value at 6 percent is
. This is a
higher amount than the proposed price of $65,000 for life-long family membership. The lifelong family membership is thus a better deal. b. The interest rate that makes you indifferent is the one that equates the present value of the two choices, that is,
, from which we get k = 6.17%.
c. The annual fee, call it X, that makes you indifferent is giving by the equation: , from which we get X = $1,893.20. d. $68,667, which is the present value of the current membership if it were an annuity growing at 3 percent.
8. Growing annuities versus growing perpetuities. a.
It is the present value, at 8 percent, of an annuity of $80 million growing at 3 percent for 5 year. Using formula 2.12 you get:
[
(
) ]
2
b. It is the present value, at 8 percent, of a perpetuity growing at 3 percent, that is, which is $1,600 million.
9. Mortgage loan. a. The monthly mortgage payment, call it X, is the solution to the equation: $80,000 = X×ADF(T=360; 8%/12) = X×136.2783 from which we get X = $587.03. b.
Interest payment in first installment =
$533.33.
Principal repayment = $587.03 – $533.33 = $53.70. c.
Total interest payments = Total payments – Principal repayment = ($587.03×360) – $80,000 Total interest payments = = $211,330.80 - $80,000 = $131,330.80.
10. Retirement planning. a.
The capital needed at 65, call it X, is an immediate annuity such as: X = $50,000 +$50,000×ADF(T=19; 6%) = $50,000 + $50,000×11.1581 = $607,905.82 The lump sum needed today is the present value at DF(T=40; k=6%): Lump sum = $609,905.82×DF(T=40; k=6%) = $609,905.82×0.0972 = $59,088.45.
b.
Amount to invest every month is an annuity, call it X, whose present value (including the immediate payment) must be equal to the lump sum $59,088.45, that is: $59,088.45 = X + X×ADF(T=40×12; k=6%/12) = X + X×181.7476, from which we get X = $323.33.
Finance For Executives -5th Edition -Chapter 3 Answers to Review Problems
1. Attitudes toward risk. a. She is either risk averse or risk neutral because stock A has a higher expected return with less risk. b. He is a risk seeker because stock B has a lower expected return with more risk. c. A risk neutral investor will buy stock B if it offers more than 13 percent. d. A risk-averse investor will buy stock B if its volatility is 25 percent. 2. Characteristics of a two-stock portfolio. 3
a. b. c.
. √
√
√
√
d.
e. No, portfolio P2 is not efficient because it has the same expected return as portfolio P1 with more risk. To be efficient, portfolio P2 must have a volatility of 24.23 percent, the volatility of portfolio P1. 3. Risk reduction through diversification. a. The expected return of the equally-weighted portfolio is the same as the expected return of the three individual stocks, that is, E(RP) = (1/3)10% + (1/3)10% + (1/3)10% = 10%. b. The variance of the 3-stock portfolio has the following structure: three variances each equal to 20 percent and three covariances each equal to 0.0200 (0.50×0.20×0.20). Given one-third investment in each stock, the variance of the portfolio is thus: Var (RP) = [(1/3)2×(0.20)2 + (1/3)2×(0.20)2 + (1/3)2×(0.20)2] + [2×(1/3)2×(0.02) + 2×(1/3)2×(0.02) + 2×(1/3)2×(0.02)] = 0.026667 The volatility of the portfolio is thus √
The risk of the portfolio
is thus significantly lower than the risk of the individual stocks in the portfolio.
4. Correlations, covariances and betas. a. Re-arrange the SML equation, E(R) = 4% + 6%β, as
Using the expected
returns in Exhibit 3.12, row 5, you can infer the betas of the 5 stocks. We have Use the same procedure you get βB = 0.50, βC = 0.90, βD = 1.30 and βE = 1.50. b. We have
from which you get
Using the same procedure you get 4
We have
Using the
same procedure you get c. (
)
(
)
. d.
( )
The portfolio beta is lower
than the market beta because there are more stocks with betas lower than one than higher. Recall that the market beta is a value-weighted portfolio, not an equallyweighted one. 5. Negative Betas. a.
(
)
(
)
. The negative sign indicates that the stock
returns have a tendency to move in the opposite direction to those of the market. b. E(RA) = 4% + (-0.20 x (9% - 4%)) = 3%. The expected return of stock A is lower than the risk-free rate because the demand for this stock is high (because its negative beta allows investors to reduce their market risk). The strong demand raises its price which lowers its expected return.
6. The CML vrsus the SML. a. If the portfolio is efficient, its expected return is given by the CML equation. Its composition must be a combination of the risk-free rate and the market portfolio. In practice, it must be one of the following four cases: (1) A proxy for the market portfolio and a riskless bank deposit or government bond; (2) A proxy for the market portfolio held without any debt (purchased exclusively with my own money); (3) A proxy for the market portfolio purchased partly with money borrowed at the risk-free rate; (4) An asset that is perfectly positively correlated with the market portfolio (either held exclusively or held with a riskless asset or with some debt borrowed at the risk-free rate). b. If the portfolio is inefficient, its expected return is given by the SML equation. Its composition is any investment other than those listed in the answer to question (a).
5