Next Move Strategy Consulting Market Research · Energy Transition
01 · Title & Market Landscape
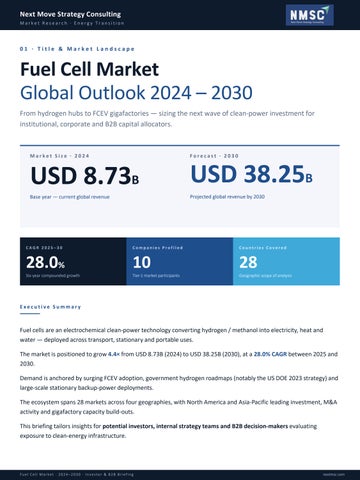
Fuel Cell Market Global Outlook 2024 – 2030 From hydrogen hubs to FCEV gigafactories — sizing the next wave of clean-power investment for institutional, corporate and B2B capital allocators.
Market Size · 2024
Forecast · 2030
USD 8.73B
USD 38.25B
Base year — current global revenue
Projected global revenue by 2030
CAGR 2025–30
Companies Profiled
Countries Covered
28.0%
10
28
Six-year compounded growth
Tier-1 market participants
Geographic scope of analysis
Executive Summary
Fuel cells are an electrochemical clean-power technology converting hydrogen / methanol into electricity, heat and water — deployed across transport, stationary and portable uses. The market is positioned to grow 4.4× from USD 8.73B (2024) to USD 38.25B (2030), at a 28.0% CAGR between 2025 and 2030. Demand is anchored by surging FCEV adoption, government hydrogen roadmaps (notably the US DOE 2023 strategy) and large-scale stationary backup-power deployments. The ecosystem spans 28 markets across four geographies, with North America and Asia-Pacific leading investment, M&A activity and gigafactory capacity build-outs. This briefing tailors insights for potential investors, internal strategy teams and B2B decision-makers evaluating exposure to clean-energy infrastructure.
Fuel Cell Market · 2024–2030 · Investor & B2B Briefing
nextmsc.com
Next Move Strategy Consulting Market Research · Energy Transition
02 · Growth Drivers & Opportunities
What's Fueling the 28% CAGR Demand Drivers · High-Growth Segments · Regional Openings Demand Drivers
01 FCEV Adoption Surge Global demand for hydrogen fuel-cell electric vehicles is expanding — Nikola opened its Coolidge, Arizona FCEV plant in July 2023, signaling scaled commercial production.
02
03
Government Hydrogen Push
Clean-Energy Capex Cycle
The US DOE published the National Clean Hydrogen Strategy and Roadmap in June 2023, formalising federal coordination behind fuel-cell investment and adoption.
Environmental concerns and rising clean-energy capex — China alone posted USD 890B in 2023 clean-energy investment (+40% YoY, 13% of fixedasset spend) — anchor multi-year demand.
High-Growth Segments Segment
Why it Matters
Time Horizon
Transport (FCEV)
Buses, trucks, material-handling fleets & passenger
Near-term catalyst
vehicles — Ballard shipped 177 engines to Solaris in Oct 2023 alone. Backup power for telecom, remote industrial & utility sites
Stationary Power
Mid-term anchor
— the most material future opportunity flagged in the report.
Portable / Military
Defense & construction portable power, low-emission
Long-tail niche
generators (e.g., Teijin Tokyo trials, Aug 2023).
Regional Opportunities
North America
USD 50B · 7 Hydrogen Hubs · 100 CA Refuel Stations
Europe
Solaris · Mobility Hubs · Transit Decarbonisation
Asia-Pacific
China USD 890B Clean Energy · Japan R&D
Rest of World
Emerging pilot programs
Headwind to Track
High upfront capital for hydrogen refueling stations — driven by specialised equipment & safety infrastructure — remains the most material near-term cost barrier. Fuel Cell Market · 2024–2030 · Investor & B2B Briefing
nextmsc.com
Next Move Strategy Consulting Market Research · Energy Transition
03 · Competitive Scenario
Who's Winning the Race Leading Players · Market Positioning · Key Strategies Top 10 Companies Profiled
Ballard Power Systems Inc.
Hyster-Yale Materials Handling
North America · Transport / Bus Engines
North America · Industrial Lift Trucks
Bloom Energy Corporation
Plug Power Inc.
North America · SOFC Stationary Power
North America · PEMFC / Hydrogen Ecosystem
Toshiba Corporation
SFC Energy AG
Asia-Pacific · PEMFC Multi-Sector
Europe · Direct-Methanol / Portable
ClearEdge Power, Inc.
Ceres Power Holdings PLC
North America · PAFC Stationary
Europe · SOFC SteelCell Technology
The Meditor Group
Ceramic Fuel Cells Limited
EMEA · Diversified Fuel-Cell Holdings
Asia-Pacific · SOFC Specialist
Key Strategies Reshaping the Market
Capacity Expansion & Gigafactory Build-outs: Ballard is establishing a fuel-cell gigafactory in Texas backed by USD 54B in IRS-aligned incentives (announced April 2024) — the largest single capacity commitment disclosed. 1
Strategic Partnerships & Volume Contracts: Ballard's October 2023 order book from Solaris (177 engines powering 127 buses + 50 modules) shows how OEMs anchor multi-year volume commitments with single fuel-cell suppliers. 2
Product Launches into Adjacent Verticals: Nuvera (Hyster-Yale subsidiary) launched the G-Series modular zeroemission power generator in January 2023 — delivering up to 85% output with one module offline, opening industrial backup-power revenue lines. 3
Geographic Diversification through M&A and R&D: Players are using acquisitions (e.g. Hyster-Yale / Nuvera) and Japan/China-led R&D programmes to secure IP and reach — key signals B2B buyers should price into supplier risk models. 4
Fuel Cell Market · 2024–2030 · Investor & B2B Briefing
nextmsc.com
Next Move Strategy Consulting Market Research · Energy Transition
04 · Regional & Product Landscape
Where the Map Lights Up Geography, End-User & Fuel-Cell Technology Mix Regional Highlights
North America USD 50B · 7 Hydrogen Hubs
Europe Public Transit Decarbonisation
· US Hydrogen Hub programme; California 100-station refueling
· Strong bus & heavy-duty fleet mandates across DE / UK / NL
build-out
· Solaris (177 Ballard engines, Oct 2023) anchors volume pull
· Ballard Texas gigafactory + IRS USD 54B incentive stack
· Listed specialists: Ceres Power (SOFC), SFC Energy (DMFC)
· Hosts tier-1 suppliers: Ballard, Hyster-Yale, Bloom, Plug Power
Asia-Pacific China USD 890B Clean Energy Capex
Rest of World Emerging Pilot Programmes
· China: +40% YoY clean-energy investment in 2023
· Latin America / Middle East / Africa — early-stage pilots
(CarbonBrief)
· First-mover opportunity for OEM & engineering partnerships
· Japan: Teijin portable / stationary pilots near Tokyo (Aug 2023)
· Local content & infrastructure requirements yet to crystallise
· R&D hubs in China + Japan anchor next-gen PEMFC / SOFC
Market Segmentation — How the Report Slices the Opportunity
By Product Type
By Application
By End-User
PEMFC — Transport & portable
Transport — FCEV cars, buses, trucks,
Automotive — OEMs, Tier-1 fleets
SOFC — Stationary power
forklifts
Military & Defense — Portable power
PAFC — Large-scale commercial
Stationary — Backup, telecom, remote
Residential — Micro-CHP
MCFC — Industrial utility
sites
Others — Industrial, telecom, utilities
Others — DMFC, alkaline, etc.
Portable — Defense, construction, offgrid
Fuel Cell Market · 2024–2030 · Investor & B2B Briefing
nextmsc.com
Next Move Strategy Consulting Market Research · Energy Transition
Thank You
Let's Build Your Hydrogen Strategy. For in-depth market insights and customised strategic guidance, we invite you to connect with us. Whether you're evaluating a fuel-cell investment, sizing a regional entry, or building a B2B partnership thesis — our analysts will scope the right rigour for your decision.
Official Website
Contact Number
Email Inquiries
nextmsc.com
+1 857 758 5017
info@nextmsc.com
Full report library & analyst access
Direct line to our research desk
For custom-scope engagements
Click Here for the Complete Report
Follow Us On
YouTube
Twitter / X
Custom regional cuts · competitor teardowns · supply-chain diligence — on request.
Fuel Cell Market · 2024–2030 · Investor & B2B Briefing
nextmsc.com