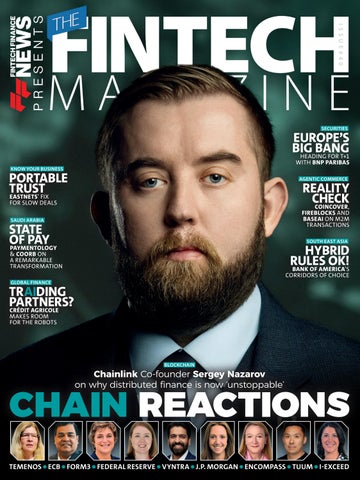
I S S U E #40 SECURITIES
EUROPE’S BIG BANG HEADING FOR T+1 WITH BNP PARIBAS
KNOW YOUR BUSINESS
PORTABLE TRUST EASTNETS’ FIX
AGENTIC COMMERCE
REALITY CHECK COINCOVER,
FOR SLOW DEALS
FIREBLOCKS AND BASEAI ON M2M TRANSACTIONS
SAUDI ARABIA
STATE OF PAY PAYMENTOLOGY
SOUTH EAST ASIA
HYBRID RULES OK! BANK OF AMERICA’S
& COORB ON A REMARKABLE TRANSFORMATION
CORRIDORS OF CHOICE GLOBAL FINANCE
TRAIDING PARTNERS? CRÉDIT AGRICOLE MAKES ROOM FOR THE ROBOTS
BLOCKCHAIN
Chainlink Co-founder Sergey Nazarov on why distributed finance is now ‘unstoppable’
CHAIN REACTIONS TEMENOS ● ECB ● FORM3 ● FEDERAL RESERVE ● VYNTRA ● J.P. MORGAN ● ENCOMPASS ● TUUM ● I-EXCEED
OCT 29
NE W Y O R K C I T Y
Your invitation to the new financial system. Join senior executives from banks, market infrastructure providers, asset managers and institutional allocators for one day focused on the future of global finance.
chain.link/linknyc
Apply to attend
2026
THE FINTECH MAGAZINE ISSUE#40
6
TOKENISED ASSETS
Putting collateral to work
Why Chainlink believes its partnership with DTCC will unlock tokenised lending
8
CORE BANKING
Taking control of your payments transformation With the migration to ISO 20022, the whirlwind expansion of A2A and instant solutions plus tokenisation on the horizon, banks could be forgiven for feeling they are victims of change, not the masters of it. By combining the best of buy and build, Icon Solutions is giving them the tools to design their own destiny
12
CROSS-BORDER
Going with the flow
As choices between traditional transaction corridors and new ones multiply in APAC and elsewhere, Bank of America is focussed on providing clarity and choice for institutional clients
15
TRANSACTION MONITORING
Navigating change
What’s worse than a transaction getting stuck? Not knowing about it. Vyntra’s Transaction Observability platform is designed never to leave a bank or its corporate customer in the dark again
8 FFNEWS.COM
18
TOKENISATION
The freedom to choose
With the FIUSD token, Fiserv has its own stablecoin ambitions. But, for now, the opportunity lies less in creating digital money and more in enabling financial institutions to move it
22
SECURITIES TRADING
Time travellers
A sizeable chunk of the globe will halve the settlement time for securities trading next year. It’s a major moment – but not the last temporal shift
24
AML/CFT
When too much is not enough
LSEG Risk Intelligence is known around the world for providing some of the best data enrichment for AML/CFT screening. But with financial services weighed down by the cost of increasing false positives, could it be a case of too much information? LSEG turned to Amazon Bedrock to solve that dilemma
15
THEEDITOR’SVIEW We’re coming to the end of our 10th anniversary. The first edition of The Fintech Magazine was published in May 2016. It was a monster; at 128 pages, it landed like a brick on physical subscribers’ mats. There was just ONE feature in that edition that mentioned blockchain, written by Simon Taylor, then heading up R&D at Barclays in the UK. Taylor went on to found the fintech consultancy 11:FS. Now he’s probably best known for creating essential Sunday reading, the Brainfood newsletter and the accompanying podcast. And he’s still backing blockchain as an enterprise utility (as, indeed, is Barclays). Compare that issue to this, where it’s hard to find a feature that doesn’t mention distributed ledger technology (DLT) and the tokens it facilitates. Taylor’s ‘rail above the rails’ thesis isn’t a ‘what if?’ concept any more. It’s being hard-wired into Tier-1 banks. And that puts them in a powerful new position. Such is the strategic reach and investment needed to add these new pipes to the network powering global commerce – and to broker the interconnectivity needed to make sure the data flows smoothly – that they’re now widely regarded as best equipped to do the job. The now mature deFi ecosystem of providers will lend technology heft, of course. But, it appears less and less likely that fintechs will eventually ‘eat the banks for lunch’. Sue Scott, Editor This issue’s spinetingler is a quote from the businessman, investor and philanthropist Michael Dell, who founded Dell Technologies, one of the world's largest tech infrastructure companies in which he is STILL invested. ISSUE 40 THEFINTECHMAGAZINE 3
FINTECH
MAG A Z I N E
26
BLOCKCHAIN
Token economics
Through its blockchain business J.P. Morgan Kinexys, the global bank is proving that ‘old money’ institutions can play a thoroughly modern role
29
KNOW YOUR AGENT
Putting trust in real-time
34
Eastnets is using verifiable Legal Entity Identifiers to create a reusable record of people, companies and documents to accelerate the business of commercial exchange
32
32
CBDCs
The digital euro: Future-proofing European payments The concept of a digital euro was to give European citizens and businesses greater choice and a trusted means of payment in the digital age. With its arrival expected in 2029, we discuss preparations, pilots, and how PSPs can benefit
34
PLATFORM BANKING
App-ortunity knocks
Banks needn’t be the ghost in the machine – a background utility powering the superapp economy. They can be that economy, says S. Sundararajan – and agentic AI will enable it
36
REUSABLE IDENTITY
Know your corporate
Momentum is building for a reusable digital identity that allows banks to process corporate requests quickly and securely. Royal Bank of Canada and technology partner Encompass share their experience of implementing just such a data passport
40
AGENTIC AI
Reinventing trade finance
Crédit Agricole is investing in AI across its estate, but its trade finance platform Optimtrade is leading the way
42
TOKENISATION
Time to build is now!
Bockchain is fundamentally changing the way global finance operates. The challenge now is interconnectivity
44
26 SME FINANCE
Lending a hand
Small businesses in the Middle East and South East Asia aren’t getting the credit facilities they deserve – and banks aren’t seeing the profit from them. Tuum has a blueprint that could help both
46
PAYMENT RAILS
Hello olo!
AGENTIC BANKING
When agents hold the keys
A new autonomous entity in the payments chain is reframing everything we thought we knew about trust and accountability
52
PAYMENTS
Acing the payments of tomorrow
AI and tokenisation in all its forms will transform payments – but you still need to decide the best game plan for delivery, says BNP Paribas’ Bruno Mellado
56
MENA & APAC
From follower to leader: Saudi Arabia’s payment market grows up
The Clearing House in the U.S. is about to offer so-called One-Leg-Out 24/7 cross-border payments processing over a familiar rail. Here, it’s joined by Form3 to tell us about the technological challenges and what comes next
48
54
INSTANT RAILS
Open all hours
Three years after its launch, the U.S. instant payment rail FedNow has more than 1,900 institutions on board and a world of use cases it never predicted
The Kingdom has transformed its infrastructure, its regulatory approach and consumer payment habits, taking just a few years to achieve what other countries spent generations building. So what next for this precocious payments child?
61
AGENTIC COMMERCE
Building trust in the agentic age
As AI moves from answering questions to executing transactions, the banking industry faces a fundamental shift, says Temenos
62
TOKENISATION
TradTok: Why banks must learn to bank both ways The new norm isn’t a choice, but a symmetry of transaction methods
THEFINTECHMAGAZINE2026
ISSUE#40
EXECUTIVE EDITOR Ali Paterson
EDITOR Sue Scott
PARTNERSHIP MANAGER Georgia Stubbs
ONLINE EDITOR Lauren Towner
GENERAL MANAGERS Tom Dickinson Chloe Butler
ART DIRECTOR Chris Swales
PRODUCTION TEAM Tom Dickinson Matthew Burls Dylan Young
VIDEO TEAM Louis Jean La Grange David Hill Ethan Peck
CHIEF REVENUE OFFICER Shaun Routledge
SUB EDITOR Frank Tennyson
PHOTOGRAPHER Jordan Drew
FEATURE WRITERS David Firth James Grant Martin Heminway Amelia Isaacs Tracy Mitchell Sue Scott James Tall Frank Tennyson
The Fintech Magazine is published by FF NEWS LTD. Pantiles Chambers 85 High Street Tunbridge Wells, TN1 1XP
CONTACT US ffnews.com DESIGN & PRODUCTION www.yorkshire creativemedia.co.uk
IMAGES BY www.istock.com PRINTED BY IPrint Express, Singapore "PROUDLY NOT ABC AUDITED"
All rights reserved. No part of this publication may be reproduced, stored in a retrieval system or transmitted in any form or by any means, electronic, photocopying or otherwise, without prior permission of the publisher and copyright owner. While every effort has been made to ensure the accuracy of the information in this publication, the publisher accepts no responsibility for errors or omissions. The products and services advertised are those of individual authors and are not necessarily endorsed by or connected with the publisher. The opinions expressed in the articles within this publication are those of individual authors and not necessarily those of the publisher.
4 THEFINTECHMAGAZINE ISSUE 40
FFNEWS.COM
FINTECH
MAG A Z I N E
TOKENISED ASSETS
DTCC and Chainlink put collateral to work Chainlink’s bundle of upgrades and launches in late 2026 was hailed as the infrastructure for moving ‘the next $60trillion in onchain finance’. And it brought that to life alongside America’s leading central securities depository, DTCC Collateral has stubbornly kept to bankers’ hours. It moves when the settlement systems are open, sits still when they are not, and spends a surprising amount of its life doing nothing at all. Citi estimates that around a quarter of institutional collateral is idle at any given moment, trapped behind settlement cut-off times and operational friction, a habit that, by Chainlink’s reckoning, costs the average Tier 1 bank roughly $346million a year in forgone revenue. At Sibos in September, the Depository Trust & Clearing Corporation (DTCC) and Chainlink set out to show that idle collateral can be put to work. On stage, DTCC’s Digital Assets CTO Dan Doney and Chainlink Cofounder Sergey Nazarov demonstrated Chainlink Fulcrum executing a cross-chain securities financing transaction using the DTCC Collateral AppChain. Stripped of the acronyms, the demo was a loan. “It’s tokenised cash being lent out and it’s tokenised equity in the form of Microsoft shares being used as collateral,” Nazarov told journalists at the time. “So you have tokenised cash and tokenised equity across two chains interacting with each other.” Remember, DTCC is the institution that, as Nazarov puts it, ‘basically holds all the equity in the U.S. financial markets’. That is a slight stretch, though not much of one. Through its subsidiary, the Depository Trust Company (DTC), DTCC acts as the central securities depository for virtually all broker-to-broker equity transactions in the U.S., holding more than $114trillion in securities. Its subsidiaries processed transactions valued at $4.7quadrillion in 2025, and three of them, DTC included, are designated systemically important financial market utilities, which puts them 6 THEFINTECHMAGAZINE ISSUE 40
under direct regulatory oversight and firmly in the ‘too big to fail’ territory. In short, DTCC is the infrastructure on which Wall Street runs. So when it settles a transaction using a private and public chain simultaneously for the first time, the market pays attention. The collaboration between DTCC and Chainlink was first announced in May, when DTCC said its Collateral AppChain would integrate the Chainlink Runtime Environment (CRE) and Chainlink’s data standard for orchestration, data and automation. The AppChain is designed as shared infrastructure for collateral providers, receivers, managers, triparty agents and custodians, automating eligibility checks, valuation, margining, optimisation and settlement. It is expected to go live before the end of the year.
It will show the first really large-scale use case of tokenisation and the value that provides beyond just the act of tokenisation itself Sergey Nazarov, Chainlink “Our goal is to enable 24/7, near real-time collateral management across global markets and blockchains,” said Nadine Chakar, global head of DTCC Digital Assets, at the time. Nazarov called it ‘the killer app that traditional finance has been waiting for from our industry’. The timing matters, because the assets that will flow through the AppChain have only just arrived. The DTCC Tokenization Service went live on 28 October on the Canton Network and DTCC’s private Besu network, with 20 firms signed up, including Bank of America, Barclays, Citi, J.P. Morgan, Morgan Stanley and UBS.
It lets participants convert DTC-custodied securities – Russell 1000 stocks, index-tracking ETFs and U.S. Treasuries – between traditional and tokenised form. For Nazarov, DTCC’s involvement is what separates this next stage of blockchain maturity from the tokenisation wave that came before it. “Maybe two years ago, there were a lot of tokenised funds,” he says. “But there really weren’t many places or venues where you could post it as collateral or get yield on a tokenised fund. And so tokenised funds didn’t take off as much as we thought.” It is a refreshingly candid admission. Tokenising an asset, it turns out, is the easy bit. The hard act is giving anyone a reason to hold the token, beyond its novelty value. Nazarov thinks equity will be different on both counts. The first is trust: DTCC is putting ‘a reliable and de-risked form of equity’ on chain, he says. The second is utility, through ‘securities lending, better yield, 24-7, 365 movement of the equity in ways that traditional equity can’t be moved’. “I think it will really show the first large-scale use case of tokenisation and the value that provides beyond just the act of tokenisation itself,” he says. Chainlink’s job in all this is to make sure the equity actually has utility once it is tokenised. “What we do with the DTCC is enable that equity to have data that moves across chains, be coordinated with the DTCC AppChain correctly and various other key operations,” Nazarov explains. That is where Fulcrum, launched on the final day of Sibos, comes in. Chainlink bills it as the first cross-chain repo flow, and its central idea is to separate the venue that manages a financing agreement from the networks FFNEWS.COM
Making collateral work harder: The Chainlink/DTCC project proved both trust and utility
where the cash and collateral actually settle. Counterparties pick eligible assets, set terms – prohibiting rehypothecation of collateral, for instance – and settle across whichever supported chains they like. Under the bonnet, the Chainlink Runtime Environment handles the workflow, Chainlink’s Cross-Chain Interoperability Protocol (CCIP) moves the assets and Data Streams supplies valuations and agreed haircuts. Fulcrum does not hold assets, act as a counterparty or run a trading venue. Nazarov describes it as ‘an efficient single place where the agent lender, the prime broker, the pension fund, the hedge fund, can all go and interact with the collateral venue. They can interact with all these different loan agreements. They can do repo transactions very efficiently with each other’. “It’s really an interface for the business side,” he adds – the people who would rather not think about which blockchain their collateral happens to be sitting on this week. There is a bigger ambition behind it, too. Nazarov wants Fulcrum to open decentralised finance’s lending markets to traditional institutions and vice versa. “How do we get the tradFi and deFi convergence to happen? That’s really been our focus now for a few years,” he says. “Fulcrum, I think, is the answer.” The other half of the plumbing got an upgrade at Sibos as well. CCIP 2.0 adds Cross-Chain Verifiers (CCVs), which let issuers layer their own independent verification over the protocol’s default security; built-in links to Chainlink’s Automated Compliance Engine (ACE) for eligibility checks, approvals and transaction limits; and offers a choice between faster transfers FFNEWS.COM
and waiting for full finality on the source chain. At Sibos, Chainlink declared that ‘the infrastructure for the next $60trillion in onchain finance is now in your hands’, which is, in practice, quite a lot to put in anyone’s hands. CCIP is already part of the DTCC work. And without that kind of interoperability, Nazarov argues, tokenisation does not get very far. “If you can’t move tokenised cash, if you can’t move tokenised equity across chains, then it’s not very useful, right? Because all the clients and all the users and all the liquidity will not be based in any one chain.”
The Swift Ledger piece The third announcement by Chainlink at Sibos involved Swift, which is building a blockchain ledger of its own. Chainlink said banks can use CRE to connect existing systems and key-signing infrastructure to the ledger, while retaining control of the keys that authorise transactions. The goal is 24/7 cross-border payments using tokenised deposits held on banks’ balance sheets, with settlement continuing overnight and at weekends. Bottomline, one of Swift’s largest service providers, is connecting ISO 20022 messages to onchain settlement through its Global Pay Connect platform, powered by Chainlink.
The Swift Ledger is ‘more a payments-focussed solution’, says Nazarov, which ‘makes sense since they’re Swift and a lot of their network traffic and usage is around payments’. UBS and other large institutions have previously used Swift and Chainlink together to execute transaction flows for tokenised funds. “Now with the Swift Ledger, we’re building on all that past work,” says Nazarov, “and we’re making it very easy for banks to connect into the Swift Ledger and eventually do more and more advanced operations on it.” The common thread across all three announcements in September is that the Chainlink Runtime Environment (CRE) now sits behind both DTCC’s collateral work and banks’ route into Swift. That is quite a position to occupy with two of the most important institutions in global finance. “People will buy more tokenised equity with tokenised cash,” Nazarov predicts. “They’ll both be used as different types of collateral and different loan agreements.” Whether the industry’s collateral managers are ready to work weekends is another matter. But if Nazarov is right, their collateral will be.
Sergey Nazarov, Co-founder of Chainlink
ISSUE 40 THEFINTECHMAGAZINE 7
FINTECH
MAG A Z I N E
TAKING CONTROL OF YOUR PAYMENTS TRANSFORMATION
PAYMENTS
With the migration to ISO 20022, the whirlwind expansion of A2A and instant solutions plus tokenisation on the horizon, banks could be forgiven for feeling they are victims of change, not the masters of it. Icon Solutions’ remedy is to allow banks to build and buy as much as they want to create their own unique payments solutions
The global payments landscape is undergoing its most significant transformation since card schemes were first rolled out across the mid-20th century. The industry is approaching a tipping point where account-to-account (A2A) payments, powered by open banking infrastructure, are rapidly gaining ground on traditional card networks, buoyed by the twin promise of lower costs and faster settlements. According to Juniper Research, global A2A payment transactions are set to surge from 60 billion in 2024 to 186 billion by 2029, which represents a staggering 209 per cent increase. Instant payments are seeing even greater traction, with traffic migrating from net settlement schemes to instant schemes, and direct debit volumes expected to partially move to Request to Pay. The accompanying uptick in new payment methods for banks to onboard and manage means that life won’t be getting any easier for financial institutions any time soon. But it’s certainly becoming more interesting! At the same time, while ISO 20022 marks a major milestone for global payments standardisation, the transition to richer XML messaging and stricter data mandates has also 8 THEFINTECHMAGAZINE ISSUE 40
Toine van Beusekom, Strategy Director at Icon Solutions
introduced significant operational and technical complexities. With banks increasingly operating in a 24/7, always-on world, where customers expect their payments to complete immediately (domestically and now internationally), payment processing remains one of banking’s most critical functions and must meet the highest standards of resilience and availability.
SCALING FOR THE REAL-TIME RUSH
Liam Jeffs, Global Sales Director at Icon Solutions
As the race to real time continues to heat up, there will be significant peaks in payment traffic that banks will need to respond to – and an ever-increasing proportion of that traffic will be bound to strict service level agreements (SLAs) spanning several seconds. That means that banks will need agile payments systems and databases that are able to deal with the throughput, the peaks and the processing SLAs while remaining ultra-resilient. This is where Icon Solutions steps in. The fintech company has been designing and implementing state-of-the-art payments systems since 2009. Its core product, the Icon Payments Framework (IPF), is now trusted by a host of leading banks, including NatWest, UBS, BNP Paribas
Masters of the universe: Banks can take control of their payments destiny
and Citi, with the latter currently undertaking a multi-year modernisation of its payments platform in partnership with the company. IPF gives banks the technology and processes to independently accelerate the transformation of their payments infrastructure, allowing them to build, test and deploy payments processing solutions much faster, while staying in total control of timelines and costs. It supports a wide array of payment types and clearing and settlement schemes, including instant payments, Real-Time Gross Settlement (RTGS), and SWIFT cross-border wires. Integration is competently handled via IPF Connectors, which bridge the gap with core banking systems (e.g. fraud, sanctions, accounting), and it uses the MongoDB database to back FFNEWS.COMA
both the active IPF Event Journal (for audit and event state tracking) and the IPF Operational Data Store (for downstream streaming, reporting and operational insights). IPF offers banks a middle ground between risky legacy systems and complex wholesale replacement. With flexible build-and-buy options, Icon Solutions says it caters to varying levels of engineering capability across the banking sector. “Hardly anyone is buying a complete solution anymore,” explains Toine van Beusekom,
To put it simply, whether a bank wishes to buy, build or both – with IPF, they can do their payments, their way. The guiding principle is that the best way to achieve payments perfection is by consolidating fragmented systems and moving step by step towards a single infrastructure that can support any payment, anytime and anywhere. The first step is overcoming the limitations of legacy infrastructure. Legacy systems are often difficult to replace because they support critical payments services
released a reference implementation showing how banks can use IPF to integrate and orchestrate digital asset payments using any DLT network, while enabling seamless connectivity with existing core banking systems and payments infrastructure.
ALIGNING TO NEW STANDARDS In the legacy rails environment, ISO 20022 has created both a problem and an opportunity for banks. It’s generating significantly more usable data around
HARDLY ANYONE IS BUYING A COMPLETE SOLUTION ANYMORE. BUT THEY’RE ASKING THEMSELVES HOW MUCH THEY SHOULD ACTUALLY BUILD, AND WHETHER THEY HAVE ENOUGH ENGINEERS TO DO SO Toine van Beusekom, Icon Solutions
Strategy Director at Icon Solutions. “But they’re asking themselves about how much they should actually build, and whether they have enough engineers to do so. “We’re working with these banks and our partners to package up the capabilities they will need and then deliver them as a solution.”
STARTING SMALL Icon Solutions is guided by a belief that banks should lead their own transformation, and that they should retain the control to change things safely, quickly, and cost-effectively. IPF gives those banks greater flexibility in how they can structure and scale a new payments engine with a predictable, reliable runway to peak load. With flexible build-and-buy options, Icon Solutions also supports varying levels of engineering expertise while enabling banks to modernise at their own pace. FFNEWS.COM
that can’t be interrupted. Icon therefore encourages banks to start small, using IPF to integrate with their existing technology estate. “Starting small with a simple initial use case, whether that’s instant payments or high-value payments, is a good way to begin the journey,” says Liam Jeffs, Icon’s Global Sales Director. “What we’ve seen recently is that this approach breeds confidence, allowing banks to then subsequently transition other rails and use cases, including digital assets, onto IPF to continue their modernisation.” Digital assets are increasingly moving into the spotlight, and IPF is ready for them. It is agnostic to both the type of digital asset and the distributed ledger technology (DLT) network on which they are issued, and it has already been used in live environments for DLT-based clearing and settlement. To promote greater interoperability and prepare for wider adoption, Icon recently
payments that needs to be managed, mostly through translation layers and middleware that can interpret the new MX codes, while standardisation is broadening the number of settlement options that banks can now access. According to van Beusekom, this should prompt banks to move from vertical product silos to a more horizontal, value-driven operating model. The IPF architecture encourages them to do exactly that, he says. It enables banks to ask whether a transaction is best achieved via traditional or newer alternative rails – or a combination of both, focussing on the value proposition for each client rather than just the last mile of clearing. “We all thought that ISO 20022 would simplify things, but we now have more and more options,” says van Beusekom. “There must be 50 ways to clear a payment. ISSUE 40 THEFINTECHMAGAZINE 9
FINTECH
MAG A Z I N E
“Traditionally, banks have been organised vertically around specific products – ‘I’m a product manager for’ SEPA or for FedNow, or for international payments. But if you start to move that vertical to more horizontal thinking along the value chain – such as order management, execution and clearing and settlement – you can do much more interesting things.” Jeffs agrees that this decoupled thinking will become crucial as banks carefully consider how they can convert huge streams of data, whether they can monetise it by using it to offer new products and services, and how. “The question to ask is how banks can handle these surging data volumes from a resiliency and also from a latency perspective,” he explains. “The research from our recent white paper with MongoDB, Scale Without Sacrifice, proved that IPF can achieve 6,000 TPS (transactions per second) with excellent latency rates. “This optimal performance gives banks more confidence that they can maintain a scalable and resilient solution, even as they are transitioning from card-based payments to high-volume instant payments and A2A transactions.”
THE QUESTION TO ASK IS HOW BANKS CAN HANDLE THESE SURGING DATA VOLUMES FROM A RESILIENCY AND ALSO A LATENCY PERSPECTIVE Liam Jeffs, Icon Solutions
The strength of IPF’s proposition is particularly well illustrated by the successful partnership between Icon Solutions and Citi. IPF has allowed Citi’s engineers to rapidly build and implement an ISO 20022-native global payments processing platform. Citi Malaysia was chosen as the first market to deploy the architecture, reflecting its role as a regional transaction hub that needs to meet tight deadlines for high-value RTGS payments. The successful rollout has provided a blueprint for modernisation, with Citi now scaling the IPF-driven platform globally and planning to extend it across most of its markets.
ADJUSTING TO AI There has been a noticeable and decisive shift over the past year or so, with more and more banks moving from an ethos of AI experimentation towards more practical 10 THEFINTECHMAGAZINE ISSUE 40
and value-adding deployments. As Icon continues to refine and evolve IPF, the company therefore has a very close eye on AI and other emerging technologies. It views AI through three distinct pillars. The first concerns internal product development, using AI to significantly reduce the time taken to create products within a closely controlled development lifecycle. “Some of the things that once took weeks can now be scaled back to a couple of days,” says van Beusekom. The second covers helping banks to translate their individual business requirements into implementable flows through IPF. “We’re looking at requirements gathering,” he explains. “Can AI do that, and, if so, how do we move from identifying a business requirement to creating the supporting flow? It can really speed things up. However, we’re
analysts and architects with the skills to get the most out of Icon's framework technology. “Our certification programme has really exploded over the past couple of years,” says Jeffs. “When banks want to go through the change management process and they want to look at their estate, they can build it themselves completely or they can leverage a network of partners to build it with them. “This gives them the fungibility and resources that are certified to deliver the kind of changes they are looking for.” There are now nearly 200 IPF-certified professionals across the company’s clients and partner organisations, who are being empowered by a comprehensive training programme as well as a new learning portal. The purpose of the portal is to enhance the learning experience, support ongoing
Gearing up: AI is helping banks accelerate payments innovation
always, of course, dependent on guardrails to ensure safety.” The third pillar is applying AI to specific operational tasks, such as converting unstructured addresses into structured formats, or performing name and number comparisons. This integration of AI into specific runtime tasks and requirements gathering shows a focussed and highly practical application of the technology where it can provide immediate operational efficiency, without compromising the underlying stability of the payment rails. Above all, Icon’s approach is realistic. “If you’re thinking about asking me whether we can ‘vibe code a payments engine’, we’re not there yet,” adds van Beusekom.
PLOTTING THE PATH AHEAD Looking forward, Icon’s focus is on further building out its expanding ecosystem and collaborating closely with the banks that it supports around the world. The IPF certification programme reinforces this approach, equipping engineers, business
professional development, and create a scalable foundation to meet the needs of a rapidly growing community – with Icon saying it’s ‘further accelerating our clients’ journey to independence’. It’s yielding the right kind of results. Earlier this year, the company presided over its largest-ever European and North American IPF Client Days, sessions that provide opportunities for senior executives to exchange perspectives on the evolving payments landscape and share their experiences and insights on how they are using IPF to respond to it. Icon’s considerable contribution to the payments industry – and the modernisation agenda – was recognised recently when it became one of the organisations in the UK to be honoured with a prestigious 2026 King’s Award for Enterprise in Innovation. The award stands as a testament to the team’s expertise in providing banks and other financial institutions with the technology they will need to innovate incrementally and transform payments on their own terms. FFNEWS.COM
FINTECH
MAG A Z I N E
G oıng with the f low CROSS-BORDER
As choices between traditional transaction corridors and new ones multiply in APAC and elsewhere, Bank of America is focussed on providing clarity and choice for institutional clients The next big advance in cross-border payments may be less about building new networks than finding better ways to connect the ones already in existence. Across Asia-Pacific, sophisticated real-time payment systems are transforming domestic transactions. But connecting them with Western infrastructure remains a challenge, particularly when markets operate to different rules and timetables. The question is how much can be achieved by bridging existing systems, and where might blockchain, stablecoins and tokenised deposits offer something more. “This year it feels like we’re at an inflexion point,” says Sid Gupta, Head of Financial Institutions Transaction Banking for Asia at Bank of America. “There’s been so much conversation around digital assets and cross-border payments over the last two years, and that conversation has now matured. We and our banking partners and clients have reached a stage where we have a view on which rails work for which flows.” 12 THEFINTECHMAGAZINE ISSUE 40
Asia’s economic growth and shifting trade patterns are clearly adding to the demand for faster, more flexible cross-border payments. “APAC as a region has been growing at a pace slightly higher than other regions and there are various factors for that: things like demographics and the AI build-out,” Gupta explains. “If you look at North Asia, markets like Taiwan, Korea and Japan have seen a lot of growth in the last couple of years. There are also shifting supply chains, and markets like South East Asia benefit from some of that.” But speed is only part of the challenge. Asia-Pacific is a patchwork of advanced payment systems, with different networks, regulatory requirements and operating hours. Bank clients increasingly expect more than fast settlement. They also want to know where their money is, when it will arrive and what information accompanies it, while for treasurers, round-the-clock payments bring additional challenges around liquidity, funding and reconciliation, particularly when transactions cross time zones. “The market and our clients are super-focussed on two things,” notes Gupta. “One is access: the ability to access markets at all times and move funds cross-border in real time. That’s been a theme for the last few years and banks are getting closer to delivering that experience through the investment they’ve made. So, removing the friction from cross-border payments is one overarching theme. “The other, I’d say, is the ability to add intelligence to the payments experience, whether through AI or other technology
investments that provide that extra layer of intelligence, and leveraging AI more broadly for our corporate clients. “That can also extend to supporting our financial institution clients,” Gupta adds. “It’s providing our network to help support flows that our financial institution clients can’t access directly; they need a partner to access those – and provide it in a way that is frictionless.”
New rules of engagement Fintechs and digital payment platforms are winning a larger share of cross-border business in APAC, which has emerged as a major hub for stablecoin activity. Global banks face a complex regulatory landscape. In the US, the GENIUS Act establishes a framework for payment stablecoins, while preserving the ability of banks to issue tokenised deposits. Meanwhile, Singapore is developing a regulatory framework intended to support high-quality, trusted stablecoins as settlement assets. Approaches also differ across Hong Kong, Japan and Australia, where regulators are developing their own requirements for stablecoin issuance and oversight. These differences are reshaping relationships between banks and fintechs. “Even when we think about the relationship banks have with each other, we compete, but we also rely on each other to support our underlying clients, because no bank can do everything for everybody. So, it is a bit of a partnership,” Gupta points out. “With fintechs, that relationship is also evolving. Fintechs cater to a market where maybe some banks are not comfortable, and they’ve developed a layer to support those flows or clients. But they do need banks to FFNEWS.COM
A sea change: Banks are finding new ways to connect traditional and emerging payment systems across Asia-Pacific
There’s a realisation that these alternative technologies are probably here to stay, and we need to stay invested in them
settle the last mile or to expand what they’re doing for their clients. “Depending on what the fintech does, there may be more direct competition; in others, it’s a partnership. But we do think there’s a place for fintechs to coexist with banks, and that’s how we look at that space.”
Bridging the divide Bank of America’s Cross-Border Real-Time Payments solution is one example of how banks are responding to this diverse payments landscape. In September, Brazil’s Bradesco Bank completed a pilot transaction using its existing Swift connection to send money through Bank of America to a beneficiary in Hong Kong, where it was delivered via the Faster Payment System. It proved that faster payments, real-time tracking and greater certainty could be achieved in cross-border payments without replacing existing infrastructure. “A lot of financial institution clients are spending on technology, because banks are competing – or have been competing – with new players that can offer a number of the products and services banks have historically provided. Technology has been a huge enabler for them,” says Gupta. He identifies three areas of focus. “They are very much looking at practical use cases for AI, and that requires investment,” he says. “Banks are also super-focussed on cybersecurity and fraud detection, given the rising risks. And then there’s the whole FFNEWS.COM
tokenisation space – being effective in moving money around the world in a frictionless way, whether that’s using blockchain technology or better connectivity with traditional rails.” Bank of America is also among the major US institutions backing The Clearing House’s On-Chain Money Initiative, which aims to connect traditional payment systems with blockchain-based transactions. The planned network would allow participating banks to clear and settle tokenised deposits around the clock, while retaining the benefits of regulated commercial bank money. It could also support automated transactions and richer payment data. For Bank of America, the opportunity extends beyond payments. “We try to help our clients move money around the world or help finance the investments they’re making, whether through trade finance or by providing a balance sheet to support them,” Gupta says. For now, the bank’s direction of travel is towards a hybrid landscape, with traditional and alternative rails operating alongside each other. “In some ways it’s still exploration, but we’ve been discussing traditional rails versus alternative rails – tokenised deposits or stablecoins, and what role they play in cross-border payments – for some time now,” says Gupta. “We and our bank clients have made investments, and there’s been regulatory clarity in the US and in other markets. So, it’s fair to say the market
and our clients have a better sense of where this sits. “Having said that, we still don’t know the full potential of some of these technologies for use cases we’re not currently supporting. Things like agentic commerce – once that takes off, could these alternative rails and tokenised solutions play a bigger role? That’s something we’re monitoring.” Until those longer-term technologies find wider application, Bank of America is concentrating on what works right now. “Our approach is that we’re connected to a number of real-time payment rails, and we’re able to help move money for our bank clients in real time into these markets,” Gupta explains. That doesn’t currently require tokenised deposits, although the bank is investing in them through consortia, initiatives involving Swift’s shared ledger, multiple clearing houses and Early Warning’s international Zelle payments. “There’s a realisation and a pragmatism that these alternative technologies are probably here to stay, and we need to stay invested in them,” says Gupta. “But we can also leverage existing networks and existing rails to provide a better cross-border payments experience. “I see that conversation progressing further next year as there’s more regulatory clarity on the tokenised front, such as regulation around stablecoin issuance. And I see banks like us offering an enhanced cross-border payments experience in more markets and more corridors in real time.”
Sid Gupta, Head of Financial Institutions Transaction Banking for Asia at Bank of America
ISSUE 40 THEFINTECHMAGAZINE 13
FINTECH
Navıgatıng MAG A Z I N E
TRANSACTION MONITORING
ch hange
What’s worse than a transaction getting stuck? Not knowing about it. Vyntra’s Transaction Observability platform is designed never to leave a bank or its corporate customer in the dark again
“If a bank has real-time visibility on a transaction’s journey, you instantly know something is happening that is different from your normal operating state. You can act and never face that angry customer,” he says. “That’s what Vyntra delivers. Our systems monitor the state of the transaction, not the IT systems [handling it]. After all, systems can appear healthy, with no lights flashing even when a payment has become stuck somewhere along its journey.”
It’s said that ‘worse things happen at sea’, but for one corporate enterprise whose payment to a shipping company never arrived, the pain was felt before leaving port.
TRANSACTION OVERSIGHT
When the down-payment failed to materialise, the container ship captain refused to weigh anchor – delaying goods worth millions of euros. News of the transaction failure came from the captain, not the bank, causing an almighty row about who would pay damages incurred by the ship’s delayed departure, not to mention the harm done to the corporate customer’s reputation. This true story is told by Vyntra director Antoine Cuypers to highlight the very real risk of a financial shipwreck on the rocks of legacy payment systems. FFNEWS.COM
Formed by the merger of Swiss firm NetGuardians and Belgium’s Intix in 2025, Vyntra promises transaction oversight and fraud prevention across the full transaction lifecycle. In its first year, the firm says it monitored 11.1 billion transactions and prevented 70,500 instances of fraud. Now serving 130 financial institutions across more than 60 countries, including four of the top 10 European financial institutions, Vyntra’s Transaction Observability platform provides a single, format-agnostic view of every payment message and transaction event, from initiation to settlement. “If I order something, I can track it to my front door, sometimes to the minute,” says Cuypers. “The same level of service is expected from financial
Antoine Cuypers, Director of Strategic Alliances & Key Accounts at Vyntra Global
institutions but not all of them can deliver it yet. The crucial element is moving away from monitoring systems to monitoring the transaction journey.” Cuypers identifies this heightened customer service expectation as one of three drivers of increased pressure on the payments ecosystem. The others are higher volumes due to instant payment systems, and regulators who provide less time for providers to respond to queries. “The instant payment genie is out of the bottle and the data sizes have increased, too – the move from Swift MT to ISO 20022 messages has quadrupled the data size of a transaction,” he says.
PEELING THE ONION Cuypers believes the mix and match of legacy and modern IT at financial institutions is a key reason why providers focus on systems in isolation. Describing a typical system as an onion, with an old mainframe at its core and translation layers built around it, this silo-based approach means the bigger picture is missed, he says. “They’re looking at a specific system and it’s monitored very well. Do I have CPU capacity? Do I have disk space? But your systems could be showing a green light and the money is still not flowing. The transaction is stuck somewhere and now you need a manual interaction. In truth, you’re flying blind. ISSUE 40 THEFINTECHMAGAZINE 15
FINTECH
MAG A Z I N E
“We take a different approach. We are not asking whether a machine is running. Instead, we have touchpoints on the entire customer journey. “Our system auto-learns what is normal behaviour. For instance, it will make a distinction between a Monday in the month when people received their salaries and that month’s other Mondays. It auto-learns behaviour patterns across different channels – between your retail channel and your remittance business, perhaps. “And it learns, for example, that the time needed for a transaction to move between step A and B should be one minute. Anything longer is an anomaly and it could be caused by a range of issues, even though no red lights are showing.” Vyntra says this approach has enabled Tier 1 institutions to halve their number of ‘where is my payment?’ inquiries and reduce the level of investigations escalated across departments. Rather than reacting once a customer complains or a deadline is missed, operations teams see bottlenecks and breaches building before they cause damage and can drill down from an alert to the underlying transaction without the need for a separate technical investigation. Cuypers says the platform’s power was demonstrated by a banking client that had undergone a recent merger and had only one half running Vyntra’s system. With datasets still not combined, staff who could access Vyntra’s platform had answers to customer queries within 30 seconds, while for the rest a query would take three days to resolve via a formal operations request.
FOUNDATIONAL PILLARS The Vyntra Transaction Observability platform is built on four pillars. Pillar one demands
complete audit trails so a user can instantly customer, they no longer need to call you reconstruct what happened to a payment, to raise a query and you no longer need from initiation through enrichment, validation, to go into a web portal and start clicking screening, routing, any repair, approval and around,” says Cuypers. settlement. This ‘know your transaction’ view “They click on a button, and, through the API, ensures one correlated record per payment. all the data – the single version of the truth – is The second pillar means spotting anomalies fed back in human language to the customers. before they become incidents, which is driven This is what corporate customers want. by asking ‘are the payments healthy?’, rather “They may be curious to see how payments than ‘is the system healthy?’. from this country to that country have Pillar three involves clean data, whereby if evolved over three months, for example. So, a payment’s data is changed during its journey, they type a query in their spoken language, the institution knows immediately. and the large language model Pillar four is instant access to (LLM) communicates with the Through the API all this information, and Vyntra says platform via an MCP [model the data is fed context protocol]. institutions that manage this back in human well give operational, compliance “Our system provides all the language to and customer service teams necessary data and the LLM gives the customers. direct, self-service access to them an overview, illustrated This is what transaction data, so there’s no with graphs, and provides options corporate need to raise a formal IT request to drill down further. Underpinning customers want. or wait for a batch report. this, we have transaction Antoine Cuypers, This fourth pillar of access ‘turns observability across the entire Vyntra Global the other three from theoretical payment journey. capability into daily operational reality’, he says. “Customers, auditors and compliance AI is then layered on top to amplify the four officers can all harness the platform’s power pillars, because AI goes beyond static rules because they no longer need to understand the to learn what’s normal, provides users with technicalities of the transaction. They simply a natural language interface to raise queries, raise their query in natural language.” and can provide predictive analytics. Cuypers believes AI will ultimately take the Transaction Observability platform one step SHARING THE POWER further, allowing it to repair a stalled transaction With McKinsey estimating the cost of a typical in flight because ‘you can only repair something customer service enquiry at between $200 if you know something’s gone wrong’. and $300, offering the platform’s capability to “One could imagine that an agentic customers saves both time and money for all AI is notified of a problem and interacts parties, especially the corporate client. immediately by diverting that payment to “If you enable the power of this platform another rail or backup system. Auto-repair of and open up the capability to your corporate the flows is what I think we will move to.”
STRONG MESSAGE HERE! Firms that used ISO 20022 to improve data quality are reaping its benefits, such as improved straight-through processing. However, those that saw it as simply a message conversion task are struggling. This was Vyntra’s conclusion after speaking with delegates during October’s Sibos 2026 event in Miami. Multiple teams said they could send and receive ISO 20022-compliant Swift MX messages, but cross-border flows remained compromised by unstructured debtor and creditor addresses – exactly the reason Swift delayed its deadline for address compliance 16 THEFINTECHMAGAZINE ISSUE 40
for a third time, after snapshots showed as many as 60 per cent of payments still carried unstructured addresses. It’s a particular problem in APAC where addresses tend not to be linear and are often very fluid and long – which means they don’t map easily into Swift data fields. Vyntra says institutions must approach problems around geographical addresses as a data governance task and include their operations, compliance and customer onboarding teams in executing it. Separately, Vyntra found several banks were anticipating a surge in truncated and rejected payments this month (November) as
the MT 101 coexistence regime, under which corporates initiating payments were allowed to use legacy message fields, comes to an end. With banks still operating in a hybrid environment with domestic rails, legacy corridors and counterparties at differing stages of adoption, a single source of truth for historical data to answer regulator and customer queries becomes even more compelling. Vyntra’s advice is to index every message, be it MT, ISO 20022 or domestic, and keep an auditable trail to ensure they are all searchable in seconds. FFNEWS.COM
TOKENISATION
The
Ftoreedom choose With the FIUSD token, Fiserv has its own stablecoin ambitions. But, for now, the opportunity lies less in creating digital money and more in enabling financial institutions to move it Tokenised payments, including stablecoins and programmable money, are expanding the way value moves. But how can banks ensure that increased choice delivers better customer experiences rather than just greater complexity? Fiserv, one of the world’s largest financial technology providers, has been pondering that question for some time. It even has its own stablecoin ambitions with its token, FIUSD. But its current focus is on accommodating different payment methods and settlement mechanisms for digital assets released by other organisations and providing the on and off ramps that ensure they work inside the monetary and financial systems we have now. 18 THEFINTECHMAGAZINE ISSUE 40
Conor Gallagher, who heads Fiserv’s Financial Solutions product group across EMEA, sees the industry moving rapidly beyond the payments paradigm. “People are talking about moving money between pockets now, or moving between currencies and accounts, and using modern methods like stablecoins to do it,” he says. Consumers and businesses increasingly want money to move as easily as information, regardless of the underlying technology. And Gallagher believes it’s that convenience that will drive tokenised money mainstream. “You used to have to download a different app [for tokenised money]. Now it should just start appearing alongside your existing money or banking facilities,” he says. “That’s the expectation. The second thing is users expect it to be safe, whereas before they might not have.”
From payment tokens to tokenised money The technology might be revolutionary, but customers won’t need to become experts in it. In fact, they’ve unwittingly been using tokenisation for some time – albeit behind the scenes. They didn’t need to figure it out; it’s just worked, in much the same way that Gallagher
Conor Gallagher, Head of Financial Solutions Product EMEA at Fiserv
Rossana Thomas, Vice President, Head of Commercial Payment Solutions at Fiserv
anticipates ‘new money’ will. Like many technology providers, Fiserv already replaces sensitive card credentials with digital tokens through its card services and e-commerce technology, protecting payment information, facilitating repeat purchases and supporting digital wallets. Blockchain-based tokenisation takes that idea further. Rather than substituting payment credentials, it represents the asset itself, enabling transfers and offering the potential to programme this digital money with limits or conditions coded into the token. Stablecoins are prominent in this evolution. Designed to maintain a stable value relative to whichever conventional currency the coin is pegged against, they offer round-the-clock transfers, more efficient cross-border payments and automated settlement. Fiserv has championed their potential, announcing its own fully reserved, US dollar-backed stablecoin FIUSD in June 2025, which is intended to integrate with established banking technology and for which collaborations with PayPal and Mastercard are well advanced. But while a timeline for minting the first FIUSD hasn’t been confirmed, Fiserv’s newly launched Digital Asset Platform is now providing the infrastructure for other stablecoins FFNEWS.COM
to move over. In October 2026, Roughrider Coin, a dollar-backed stablecoin for the Bank of North Dakota’s interbank network, was the first to go live on the platform. The initiative, which brought together VersaBank, Fireblocks and the Solana blockchain to support money movement between more than 90 banks and credit unions, sees Fiserv’s Digital Asset Platform being used for issuance, reserve, custody and settlement. It offers, the company says, ‘a more efficient way to conduct bank-to-bank transactions while establishing a foundation for additional digital money use cases’. The institutions can access the service through Fiserv’s existing Commercial Center banking platform, demonstrating how blockchain-based money movement can connect with established financial workflows.
Different money, different opportunities Fiserv’s Digital Asset Platform is intended to support tokenised deposits, treasury services, cross-border transfers and programmable commerce, with scope for further digital asset capabilities. Because, for banks, stablecoins are just one part of a much bigger tokenised landscape, says Gallagher. Tokenised deposits and central bank digital currencies (CBDCs) represent different approaches to digital money, particularly regarding who holds funds and meets obligations. “With a tokenised deposit, the bank is holding the funds,” he says. “With stablecoins it’s more nuanced as to who has the funds and where. With central bank digital currencies, the central bank has the funds. They’re all quite different products; the money has a different behaviour.”
People now expect tokenised money to be safe, whereas before they might not have Conor Gallagher, Fiserv These distinctions influence the services banks can offer and the risks they must manage, he explains. Gallagher identifies B2B transactions as a promising application for tokenised deposits, particularly where payment is linked to contractual performance. “A bank can offer a supplier a way to get paid, and the money is held until the actual goods are delivered. It gives a 24-hours-a-day facility. It’s always on.” FFNEWS.COM
Modernisation without missing a beat Amol Deshmukh, Fiserv’s Director for IT Projects, discusses how you bring legacy payments infrastructure into an always-on, multi-rail world without disrupting the banking services that depend on it Platformisation isn’t just about building new infrastructure; it’s a way to bring modernisation safely into complex, mission-critical banking environments, says Amol Deshmukh. As Fiserv’s Director for IT Projects (Enterprise Payments Solutions), his central argument is that flexibility depends on separating services, simplifying architecture and allowing different technologies to work together. “Introducing new technology is one challenge; introducing it while a bank continues processing payments is another. “The systems, products and technologies are all different, yet they have to somehow make it seamless for the customer. The approach we take to modernisation means the banks don’t have to stress about making things happen for the customer, so they can really focus on evolving the business. “Modernising, or building a new platform, is generally the easy part. Rolling it out is where the rubber hits the road. “You have to focus on the payments journey – the journeys the operators have to learn or relearn, and the business services supporting those journeys – separately. When you’re able to decompose those
business services, then you’re able to roll them out. “If banks want traditional payment rails, CBDCs and tokenised deposits to operate alongside one another, then the architectural approach is for the businesses to function as services and you’re simply orchestrating them. They’re not stuck to each other; the orchestration is doing the work. “The bank should not necessarily be sitting on a single stack in the same place. It’s important for different markets and services to have the flexibility to run independently. “At Fiserv, we are literally looking at every function within each organisation. We want to allow our customers to do the extraordinary, by giving them the solutions they need in one stack or across multiple stacks. Separate the risks where banks need to, and bring them together where they want to.”
We want to allow our customers to do the extraordinary, by giving them the solutions they need in one stack or across multiple stacks Amol Deshmukh, Fiserv
ISSUE 40 THEFINTECHMAGAZINE 19
FINTECH
MAG A Z I N E
Anybody can process a payment: The value is in monetising the service
Such arrangements could reduce uncertainty over settlement, demonstrating how programmable money might create value beyond faster transfers. But Gallagher cautions against expecting immediate adoption. “A lot of things have to be modernised and standardised around it, to make it all work,” he says. “So while I think it’ll happen, it’s not going to be quick.” Obstacles include regulation, interoperability, liquidity, operational controls and whether customers see sufficient benefits to change established behaviour.
The power of choice As digital money evolves, banks must manage an expanding collection of payment rails without multiplying complexity. Rossana Thomas, Fiserv’s Head of Commercial Payment Solutions, believes traditional infrastructure makes this unnecessarily difficult. “The challenge right now is that they’re individual rails,” she explains. “In most cases, each of those rails is connected to all the same systems: the core system, the fraud system, the
OFAC (Office of Foreign Assets Control) system, the billing system, the reporting system.” This creates duplicated integration, technical debt and inconsistent customer experiences, she explains. Thomas offers a practical example. A business might initiate a payment through an automated clearing house (ACH) network but miss the same-day processing window. Switching to a real-time rail could still deliver
One journey, many rails
Jennie Farley, Fiserv’s VP of Enterprise Functional Architecture, on why banks need a common approach to processing every kind of money The growing choice of payment rails explored in our main feature creates a fundamental architectural challenge for banks. Supporting a new digital currency is one thing; integrating it into the systems responsible for accounting, settlement, customer services and regulatory compliance is another. For Jennie Farley, whose career in payments spans more than 40 years, the answer lies in looking beyond individual transactions to the entire journey of money. Here, she explores the integration challenges, the risks of excessive complexity and the decisions banks must make when building the payments infrastructure of tomorrow. THE FINTECH MAGAZINE As banks move from processing payments to managing 20 THEFINTECHMAGAZINE ISSUE 40
different forms of value, what needs to change in the way their systems are designed? JENNIE FARLEY Banks have always worked with payments, and it’s been easy. You’ve got a payment, you push it across the rail, it settles. But what we’re looking at now is banks having to work more with the whole journey of the payment – taking it from customer initiation, through traditional currencies, then possibly through digital currencies, too. The biggest challenge is probably managing this boundary between the traditional core and the new digital asset platforms. The systems have to talk to each other, so they understand where the payment is in the workflow and can track it across multiple operational systems. They have to know not just when it’s complete in one, but when it’s complete across all of them; when it’s settled on the digital asset platform and when it’s moved through traditional clearing as well.
funds that day, but becomes complicated when each rail operates independently. “With a hub, when you have all the rails on the same system, you can normalise that payment, normalise that data and jump different rails.” In other words, through payment orchestration, banks can coordinate payment methods according to the customer’s required outcome rather than the limitations of individual networks.
TFM With real-time payments, cross-border transactions and digital assets all demanding different capabilities, how can banks avoid creating a technology environment that’s too complicated to manage effectively? JF All payments process in a very similar way, so what banks have to look at is where the payment is in terms of ownership: who owns the payment and which part of it. Who owns the accounting? Who owns the transaction? Who owns the position? You have to work out what’s common to a payment as you process it and what the variations are when you’re processing a digital asset, then keep those variances away from the common processing. If you try to put all of the processing in one place, you’ll end up with spaghetti. TFM Should banks build, buy or compose their next-generation payments capabilities – and what does the ideal platform look like in 2030? JF I don’t think there is a single answer to that question. Banks are very unlikely to replace their whole payment system in one go, anyway. It’s too big a job. So they have to look at what they do today and understand where they have systems that add value and they want to keep; where they have systems
FFNEWS.COM
“You don’t have to be rail-specific, but you have to be client-experience-specific,” Thomas says. This becomes increasingly important as card networks, account-to-account transfers, instant payments and blockchain-based rails coexist. The objective isn’t necessarily to replace established systems, but to make them work together while retaining flexibility to adopt new technologies.
Beyond the transaction For Thomas, moving money efficiently is only part of the opportunity: “The payment piece becomes a commodity. Anybody can do the payment. It’s how you provide the value and how you monetise that value.” She points to transaction information, settlement certainty and integration with broader business processes. “Businesses especially want the data to go with the payments, so they can feed their supply chain, their trading partners know what they’re being paid for and they have all the information to go downstream and meet the other system requirements.”
If richer payment data can improve reconciliation, cashflow visibility and trading relationships, delivering it consistently across rails may prove as important as transaction speed. It also changes how banks approach technology investment.
I’ve had a number of conversations with clients here who say ‘we’ve built something to handle digital assets, but we’ve built a solution for a problem we’re still trying to find Rossana Thomas, Fiserv “Modernisation is not a rip and replace. It’s a transformational journey, and it could take financial institutions many years to complete,” Thomas observes. Banks must decide which capabilities to develop, which to buy and where partnerships
are most effective. The danger, Thomas says, is investing in technology without establishing customer demand. “I’ve had a number of conversations with clients here who say ‘we’ve built something to handle digital assets, but we’ve built a solution for a problem we’re still trying to find’.” For Fiserv, that tension between technological ambition and commercial reality may shape its digital asset strategy. FIUSD illustrates its ambition to participate directly in digital money, while building live infrastructure for other issuers is a much broader and potentially more influential role. As Gallagher sees it, even as payment interfaces change, banks will still be performing essential checks and balances – just increasingly in real time and around the clock. For Thomas, success depends on translating more payment rails into simpler, more valuable customer experiences. The future of payments may therefore be less about which network or currency wins, and more about the freedom to choose whichever works best. Multiple and interoperable: The new world of payments
that, if they changed them, would be a cost that they may not get any benefit from; and where they have systems they want to enhance while keeping the core. What we’re hearing is that banks are moving more towards composable services. But they have to be very careful that they’re not just implementing multiple composable services that don’t speak to each other. They also need to understand where buying buys them compliance. Suppliers can provide
a platform that comes with compliance built in and with an understanding of the architecture, so the banks don’t need to build that out. If it’s a platform that they can’t add value to, then it’s a utility. What we’re hearing with the digital euro, for example, is that it’s a service that the bank can’t make money on. So, that’s a utility and what they probably need to do is buy in the systems that support
it and build their own where they’re adding value for their customers around it. Ideally, you want a stack that can handle any payment type or asset through a single workflow. Banks want to avoid silos and multiple ways of doing something. But you also want an architecture that can handle any new assets coming into the market without a complete rebuild.
What we’re hearing is that banks are moving more towards composable services. But they have to be very careful that they’re not just implementing multiple composable services that don’t speak to each other Jennie Farley, Fiserv
FFNEWS.COM
ISSUE 40 THEFINTECHMAGAZINE 21
Chain reaction: Europe’s T+1 transition will trigger changes throughout the post-trade ecosystem
SECURITIES TRADING
A sizeable chunk of the globe will halve the settlement time for securities trading next year. It’s a major moment – but not the last temporal shift The need for speed is constant in financial services – and T+1 for settlements next year is a major leap forward for UK and European securities trading. The continent is playing catch-up; India completed its transition to T+1 in January 2023 and the US, Canada, Mexico and Argentina made their move in May 2024. The European Union, EEA members Iceland, Liechtenstein and Norway, plus the UK and Switzerland have a T+1 deadline of October 11, 2027. But though others have gone before, the route map to halving settlement times to one business day is not a ‘copy and paste’ task, says Marie-France Dessertenne, BNP Paribas’ T+1 Programme Manager. 22 THEFINTECHMAGAZINE ISSUE 40
“T+1 is a transformative moment for our markets – it’s the first step towards the Savings and Investments Union, and to making European capital markets more attractive to foreign investors,” she explains. “It aligns with transformations that have already happened elsewhere in the world on a T+1 cycle, but there’s a catch. The European T+1 transition covers three initiatives: the UK, the EU and Switzerland. That’s 32 markets transitioning big bang, at the same time, in October 2027. “It’s massive, and it forces us to rethink a number of processes and flows that need to be enhanced to be sustainable in the compressed timeframe of T+1 settlement.”
Marie-France Dessertenne, T+1 Programme Manager at BNP Paribas
SAVINGS AND INVESTMENTS UNION Moving from a T+2 to a T+1 settlement cycle is a key policy measure of the EU’s Savings and Investments Union (the new incarnation of the Capital Markets Union), which works to boost financial opportunities for citizens, improve economic investment and bring regulatory alignment to the EU’s member states. It improves efficiency by shortening the window during which counterparties are exposed to settlement risk, such as defaults, and results in lower margin requirements for central counterparty clearing houses (CCPs). Buyers get their investments quicker; sellers get their cash FFNEWS.COM
earlier, and the switch will reduce cross-border friction with other countries and regions that are already running T+1 settlement. But settlement compression will force big changes to back-office functions. Administrators will need to accelerate cash verification, trade posting and settlement processes – in the US, it was reported that firms with limited automation were forced to increase staffing by around one-fifth to manage exceptions manually. Unavoidably, the T+1 switch means an upheaval for every member of the trading chain. So, to help the industry prepare, BNP Paribas spent a year talking to its clients and partners. In October, it revealed its findings in the publication What Does T+1 Mean For You? Dessertenne says: “Our aim was to understand what the impact of T+1 is for each business line and function. How it translates for them, and how it translates across the wider ecosystem, so each partner understands the others’ dilemmas, how they fit in, and what to expect from their counterparties, clients and vendors. “It was really engaging and very collaborative, because that’s what T+1 is all about: collaboration, first and foremost.”
NO ONE TRANSFORMS IN ISOLATION As outlined in the report’s foreword, T+1 ‘demands sweeping change across the entire post-trade ecosystem... no single firm can navigate this transformation in isolation’. Counterparty readiness was a concern, with 60 per cent of custodians, 67 per cent of brokers and 50 per cent of wealth managers citing dependency on other market participants as a challenge. Europe’s transition is more complex than that of the US. While the US has one currency, one major time zone and a majority settlement venue in the DTCC, Europe spans multiple currencies, four major time zones and more than 35 central securities depositories. “Europe is fragmented and complex, with more of the distribution chain involved,” Dessertenne explains. “What really worked in the US, and is a great lesson for Europe, was involving the regulators from very early on, and all players going through an extensive nine-month testing period, so that everyone was ready. “But one of the learnings concerned the players who thought automation wasn’t needed: they’ve seen costs rise by up to 20 per cent in back-office operations within the first year. And that’s the US, with one language and a pretty large workforce. Apply that to Europe, FFNEWS.COM
with smaller markets, different languages and a workforce that’s probably less available. Still, today [in the US], there are issues around SSI [standing settlement instruction] quality and automation. That hasn’t really caught up yet.” There’s a difference in the two regions’ approaches to compliance, too. “The US essentially has a Securities and Exchange Commission penalty approach for major fails, whereas in Europe every fail carries a penalty. So, you need to get it right the first time. The implications are different.”
CURRENCIES COMPLEXITY Dessertenne cites currencies as a particular point of strain for Europe. “With T+1 you have one day less to move funding, or sometimes you even have to pre-fund, notably because of the different currencies. Trying to do foreign exchange within the continuous linked settlement window and on-trade date heightens the risk of not having the cash at the right moment and therefore failing. And any fail in Europe, as I mentioned, triggers a penalty. That’s not a moment we want to face. “It also compresses the window for securities lending. Being able to recall within a day needs anticipation. Otherwise you take a penalty, or you have to borrow while still paying a penalty fee because the transaction hasn’t settled.
The European T+1 transition covers 32 markets transitioning big bang, at the same time. It’s massive, and it forces us to rethink a number of processes
Marie-France Dessertenne, BNP Paribas “Another element, similar to the US but heightened in Europe, is time zones. Actors in the Americas will have very little time in their early mornings to deal with exceptions and fails and move funding before Europe closes. For APAC clients, the European market will likely open and close during their night-time. So, the ability to automate, standardise and harmonise, and also to find partners you can outsource certain services to, notably FX, will be absolutely key.”
BRING IN THE ROBOTS Fostering automation is a key driver of the European Securities and Markets Authority’s first T+1 deadline for market participants
this year. From December 7, the financial regulator will demand the use of ‘electronic standardised communication channels and international messaging standards, and machine-readable communication methods, except in cases of temporary technical disruptions’. Dessertenne says: “T+1 will leave technically only 20 per cent of the time to do the job that was done in 100 per cent of the time yesterday. You can’t go five times faster on the same processes, and you can’t add many more people for exception processes. “The T+1 change will demand investment by businesses, but it’s also a great opportunity to review your end-to-end business model and address any friction to make it more efficient. AI definitely has a role. We’re seeing more AI-driven solutions that can project and anticipate disruption within the settlement cycle.” As for the future, Dessertenne admits that, while T+1 is a leap forward, it’s ultimately just a stepping stone towards T+0. “T+0 and digital assets will come; it’s not a question of if, but when,” she says. “Digital assets can technically allow real-time movement and exchange… but what does T+0 mean? Is it intra-day? Within an hour? A question of minutes? Near real-time? Real-time? These aren’t the same thing. “Then we need a whole ecosystem able to support these immediate settlements, notably the European central banks and their opening hours. Most probably there will be a hybrid model, with the current settlement model and digital assets running in parallel, until a single system takes over. It will happen, and we’re working hard on it, for example with the solutions we’re deploying around tokenised funds and digital assets. Data quality will be key, because without proper data hygiene nothing we build will be sustainable in the long run. “There will always be legacy systems to adapt, and moments of human intervention and oversight. That human oversight will certainly remain, but it has to be on the right things, at the right moment, with the right number of people.” Dessertenne’s takeaway is that by preparing for and implementing T+1, the financial industry is ‘creating the future of our business’. She adds: “Much of what we’re doing at BNP Paribas is really about education. Bringing our clients together to help them understand the impacts of T+1, and also looking at how they operate in our systems: what we see of their activity, and where the points of attention are, so they can find efficiencies faster and adapt to T+1 in a more targeted way.” ISSUE 40 THEFINTECHMAGAZINE 23
FINTECH
MAG A Z I N E
In an age where passport details are sent around the world as though they were commodities and you can buy five-dollar documents on the web that pass screening tests, financial institutions have good reason to err on the side of caution when configuring know-your-customer processes. But the cost is high. Rules set to minimise false negatives inevitably inflate false positives – so much so that it’s estimated 90–95 per cent of all transaction monitoring and sanctions alerts ultimately turn out to be erroneous. Each of those, however, has already triggered a manual review by a member of staff who will, on average, take 15 to 45 minutes to change a red flag to green or escalate for further action. “What’s clear to us is that the customer wants the highest-quality decision to be made as efficiently as possible. And, if we look at the cost in the process, a significant part of it is driven by false positives,” says David White, Global Head of Product and Data, Risk Intelligence at LSEG. The challenge is not solved simply by loosening thresholds. Financial institutions need to maintain robust controls, demonstrate how results were reached and defend their processes to regulators and internal assurance teams. Any solution designed to reduce review effort therefore needs to preserve recall, provide clear supporting rationale and keep the final compliance decision with the customer.
A broader capability for World-Check LSEG’s response is Active Intelligence, a new AI-enabled data and technology capability introduced to the World-Check portfolio, the LSEG’s existing global risk intelligence and screening solution. Active Intelligence combines improvements to data sourcing, curation, deduplication and enrichment with advanced matching and explainability, but still supported by specialist human oversight. It is intended to strengthen LSEG’s wider World-Check portfolio. Customers that consume World-Check data through services such as World-Check On Demand can benefit from improvements to the underlying risk intelligence, while World-Check Verify provides embedded matching and screening through a cloud-native API for onboarding, payment and compliance workflows. The first commercial product powered by Active Intelligence is World-Check Resolve, a separately licensed add-on to World-Check One. Resolve is designed to help screening teams prioritise and assess potential matches more efficiently within existing World-Check One desktop and API channels. In testing across 650,000 screening cases, it reduced false positives by more than 70 per cent of false positives without without compromising true-positive recall. Resolve also surfaces the supporting rationale behind each result, so analysts can focus their expertise on the cases that warrant
investigation rather than repeatedly ruling out weak name matches. “There was a conventional wisdom that more data is better,” says White. “But when we actually did the modelling, we realised that wasn’t necessarily true. And this is one of the real benefits. “Effective screening depends on two things: the quality of the data and the ability to find the matches that matter,” continues White. “World-Check Resolve powered by Active Intelligence strengthens both, and it keeps strengthening them. This is data that learns.”
Humans in control LSEG specialist risk teams continue to oversee data curation and quality assurance, while customer analysts remain responsible for reviewing screening cases and making final risk and compliance decisions. The technology is designed to support those decisions, not replace them, says White. “If you’ve got to look through three results to say which is the right one, that’s fine. But if you’ve got to look through 300, that not only takes time, but it also introduces risk. That’s very much front of mind for our customers. And it’s absolutely the mission that we were aiming to solve.” The introduction of these new capabilities raises the bar on the service offered by LSEG’s Risk Intelligence division, which is already an established and trusted provider within the financial-crime, compliance and risk management sectors. “We continue to collect
When too much AML /CFT
is not enough
LSEG Risk Intelligence is known around the world for providing some of the best data enrichment for AML/CFT screening. But with financial services weighed down by the cost of increasing false positives, could it be a case of too much information? LSEG turned to its collaboration with AWS to solve that dilemma 24 THEFINTECHMAGAZINE ISSUE 40
FFNEWS.COM
high-quality data, and we can now also link that to where we see the noise in the system,” says White. That requires substantial processing capability, which led LSEG to partner with AWS. “Working with AWS helped LSEG accelerate development while maintaining the governance, explainability and human oversight required for financial-crime compliance applications,” says White. “The partnership provides the technology foundation for innovation, including the use of Amazon Bedrock, while LSEG contributes trusted World-Check data, financial-crime expertise and established quality controls. “The partnership with AWS was fantastic in speeding up time to market and ensuring we were really taking full use of the capabilities that were offered.” Active Intelligence builds on World-Check’s established approach to data by using additional signals to help determine where enrichment can add most value,
FFNEWS.COM
combining technology with the specialist human expertise that remains central to World-Check. That combination of efficiency and explainability is particularly important for firms operating in a regulated environment, says White.
There was a conventional wisdom that more data is better. But when we actually did the modelling, we realised that wasn’t necessarily true David White, LSEG
“On the technical side, we can see lots of ways to improve the situation for the customer [but] it’s got to come with all of the explainability and trust that’s essential. “From the very start, we designed that explainability into the system to ensure that when customers are making a decision, they can also defend that decision to the regulator and internally. “You’ve got to have trust that the data is correct. That sits at the very foundation of what we’re offering with World-Check Resolve,” he adds. “We already do a lot of work around both how we collect data and how we check the quality of that data. But in the world of AI, you have to combine that with solid explainability to really say ‘this is the provenance of the data; this is the timestamp’. Using that later down the line in the process then becomes that much easier.” The result is a more efficient and explainable screening process, says White, one that helps analysts focus on what truly matters: the potential matches requiring investigation.
David White, Global Head of Product and Data, Risk Intelligence at LSEG
ISSUE 40 THEFINTECHMAGAZINE 25
TOKEN ECONOMICS
BLOCKCHAIN
Through its blockchain business Kinexys by J.P. Morgan, one of the biggest global banks is proving that ‘old money’ institutions can play a thoroughly modern role For a technology once pitched as a way of subverting the traditional banking system, there’s irony in blockchain being championed these days by one of financial services’ big institutional hitters. J.P. Morgan’s blockchain unit, Kinexys, put its deposit token JPM Coin live on Ethereum mainnet last month. The message was simple: the experiment is over. Tokenised bank transactions are going mainstream. Kinexys handles around $7billion a day and has processed $4trillion since launch, which Kara Kennedy, Managing Director and Global Head of Asset Tokenization at Kinexys by J.P. Morgan, says ‘really demonstrates that we’re well beyond the proof-of-concept stage’. The wider bank moves nearly $12trillion a day, meaning that, by volume, Kinexys is still small change, representing well under a tenth of one per cent of the total. But volume, 26 THEFINTECHMAGAZINE ISSUE 40
though, isn’t the whole picture. Kinexys is doing two things at once – building new forms of money, such as tokenised deposits, and building tools that fix problems every payment has, whatever form the money takes. Increasingly, J.P. Morgan is selling those tools to others. The money came first. Kinexys has operated since 2015 and, as Kennedy puts it, has ‘10 years of experience deploying production, bank-grade blockchain infrastructure for our clients’. It first moved commercial bank money on J.P. Morgan’s private, permissioned ledger in 2019 – one of the first major banks to do so. This gave its corporate clients a way to move money between themselves around the world. The blockchain unit responsible, previously called Onyx, was renamed in November 2024 to develop the bank’s digital payments architecture. Last November, JPM Coin went live on Base, the Ethereum Layer 2
Kara Kennedy, Managing Director and Global Head of Asset Tokenization at Kinexys, part of J.P. Morgan Payments
network built by Coinbase, which runs on top of the main Ethereum chain, with the ticker JPMD. This was widely reported as the first time a major bank had deployed deposit-based money onto public blockchain infrastructure.
Taking tokens public This October’s move to Ethereum mainnet goes further. While JPM Coin is still restricted to approved, eligible institutional clients of the bank, the move places tokenised bank dollars directly on the same public blockchain network as J.P. Morgan Asset Management’s tokenised money market funds (such as MONY and JLTXX). That means clients can settle trades and pay for them in one place. Stablecoins hog the headlines, and deposit tokens tend to get lumped in with them as their more sensible cousin. Kennedy is clear that, for institutional clients, they are not the same thing. FFNEWS.COM
Beyond the bank: Tokenised money is moving onto wider blockchain networks
“Stablecoins have certainly captured the imagination as an on-chain payment vehicle that can transfer peer-to-peer, 24/7/365,” she says. “We believe deposit tokens, backed by a bank’s balance sheet, are the preferred solution for our institutional clients. “Deposit tokens benefit from the capital and accounting treatment of a bank deposit, and treasurers are already very familiar with managing bank deposits from a risk perspective. Stablecoins, on the other hand, are issued by private issuers and operate with a number of different structures for their underlying reserves.” Stablecoin advocates argue that a deposit token’s strength is also its limit: JPM Coin can only be held by approved J.P. Morgan clients, while a stablecoin can circulate freely between counterparties, exchanges and wallets. J.P. Morgan is also not the only bank in the game. Citi and HSBC run their own tokenised deposit services, which raises the question of how one bank’s tokens will move and interact with another’s. Kennedy does not expect one form of digital cash to win outright. “We certainly think that you’ll see a variety of digital cash assets in the end state: stablecoins, deposit tokens and CBDCs in certain jurisdictions,” she says. “But what FFNEWS.COM
really differentiates deposit tokens is their interoperability with traditional banking infrastructure.”
15 per cent of international payments fail because of incorrect recipient details. Fraud raises the stakes further: ACI Worldwide’s Scamscope research puts annual Money in motion global losses to authorised push payment The bank’s blockchain unit has made big scams at around $4.4billion, rising to $7.6billion strides under its new identity and now has by 2028, with roughly 63 per cent of those live client activity to point to. losses on real-time rails where a payment In August, BlackRock launched tokenised cannot be recalled once it has gone. share classes for 12 of its European Institutional “Kinexys Liink Confirm really solves an Cash Series money market funds, built on the important information gap, particularly for Kinexys tokenisation platform and minted on cross-border payments,” says Kennedy. “It Ethereum – although the funds’ shareholder now operates across more than 70 markets, register stays with the transfer agent, so, for using the information that already exists now, the tokens sit alongside existing fund within banks. This allows them to tap the infrastructure rather than replace it. information about a particular account and In Korea, KB Kookmin Bank is using beneficiary to validate that the account is Kinexys’ Blockchain Deposit Account network open and the beneficiary is as expected before to offer importers and exporters near-instant making the payment. US dollar trade payments. “We’ve now seen hundreds of millions of “Clients have come to us to solve the pain requests processed through Confirm.” points in traditional infrastructure, whether Swift offers its own payment pre-validation that’s limited operating windows or friction in service, and domestic schemes such as transferring assets peer-to-peer,” says Kennedy. the UK’s Confirmation of Payee and the “What we’ve seen is clients now embedding EU’s Verification of Payee, mandatory for these flows within their operating models.” euro credit transfers since October 2025, That money will not live on a single network. already cover many payments within those Public chains, Canton, bank ledgers, shared markets. Kinexys Liink Confirm’s pitch networks such as Partior and central bank is a single connection that works across projects will all hold a share. borders and payment rails. “It’s likely we’ll ultimately end up with Evidence that the pitch is landing comes a multi-network environment and the ability from Kinexys Liink Confirm’s growing list of to move value across it,” says Kennedy. partners. In April, ACI Worldwide integrated J.P. Morgan has said it plans to bring JPM it into its Fraud and Financial Crime solution, Coin to Canton, too, but how these networks embedding payee checks across ACH, wire will connect, and on whose standards, is and instant payments. still one of the industry’s open In August, insurance payments questions. For Kennedy, platform Diesta added it for the priority is working out insurers, brokers and MGAs. We believe ‘how do we work together, And in October, cross-border particularly on shared data payments network deposit tokens backed and standards’. TerraPay linked its own by a bank’s balance sheet That shared plumbing Verify service to the Liink are the preferred solution is arguably the more network, extending for our institutional clients interesting half of the checks to digital wallets Kara Kennedy, Kinexys by J.P. Morgan, part of J.P. Kinexys story. Some of as well as bank accounts. Morgan Payments its tools solve problems Kennedy expects common to both traditional always-on, programmable rails and tokenised payments, and to matter even more as AI agents J.P. Morgan is offering them beyond start transacting on our behalf. its own client base. Whether the model outlined here reaches The clearest example is Kinexys Liink far beyond J.P. Morgan’s own clients and Confirm, which checks that the payee in partners remains to be seen. But it does turn a cross-border payment is who the sender an old fear on its head. thinks they are before any money moves. For years, the worry was that fintechs would Anyone who has chased a bounced eventually eat the banks for lunch. Here, one international payment will see the appeal. of the world’s largest institutions is building And the problem is sizeable. A LexisNexis Risk services that fintechs plug into. Lunch, it seems, Solutions study found that between 10 and is now being served by the bank. ISSUE 40 THEFINTECHMAGAZINE 27
A world of connected payment possibilities ›› Metal, Ceramic, Wood Payment Cards ›› Instant Card Issuance, AI card designer ›› Digital asset custody ›› Secure Remote Commerce
onnected bilities
i i i i
FINTECH
MAG A Z I N E
Putting trust in real-time trade KNOW YOUR BUSINESS
Eastnets is using verifiable Legal Entity Identifiers to create a reusable record of people, companies and documents to accelerate the business of commercial exchange The technology exists to make payments in seconds – across borders, currencies and interconnected payment networks. But one critical transaction component remains stubbornly slow: trust.
The disconnect is particularly acute in trade finance, where verifying people and businesses before money can move can still take hours, days, weeks – sometimes even months. Eastnets is working on a novel way to close that gap. Unveiled in September, FFNEWS.COM
Portable Trust is an emerging technology designed to help banks, payment providers and regulators make compliance match the pace of money. If it lives up to its promise, it could transform processes and unlock opportunities in global trade. The ambition is to make trust as transferable as money itself, allowing supporting documentation to accompany financial transactions through the layered requirements of real-time payments, complex sanctions regimes, and AI-enabled fraud and compliance systems, rather than needing to be repeatedly checked at every stage. Portable Trust could act as a passport for transactions – a way for trust itself to move through the financial ecosystem. “Payments move in seconds, sub-seconds even,” explains the company’s Chief Technology Officer Luay Gadallah. “The issue is that trust has not followed through at the same speed. We’re trying to make sure that trust signals move along with financial transactions.”
Breaking the bottleneck
Luay Gadallah, Chief Technology Officer at Eastnets
Baiba Miezere, Group Product Development Director at Eastnets
Compliance is complex, expensive and fragmented. Know-your-business (KYB) checks, anti-money laundering (AML) screening, sanctions verification and fraud prevention often operate in separate systems, forcing institutions to duplicate work. The problem is especially pronounced in cross-border transactions involving multiple banks, buyers, suppliers and intermediaries across jurisdictions. “Sometimes in trade finance, they need to wait months for a customer to go through screening, including KYC/KYB and AML,” explains Baiba Miezere, Eastnets’ Group Product Development Director. “Yet transactions need to happen increasingly fast.” In reality, by the time verification is complete, information may already be outdated. For smaller businesses, the consequences of this can be severe. When compliance costs become disproportionate to the financing required, otherwise viable transactions can become financially unattractive. ISSUE 40 THEFINTECHMAGAZINE 29
FINTECH
MAG A Z I N E
The scale of this challenge is considerable. Providing investors with independently Interoperability is non-negotiable The Asian Development Bank’s latest Global “Portable Trust, in order to work, needs to verifiable evidence could reduce duplication, Trade Finance Gap Survey estimates that be genuinely portable,” stresses Gadallah. accelerate asset distribution and improve the $2.5trillion in trade financing demand went “We need to ensure it’s an open system, not economics of financing smaller businesses. unmet in 2025, equivalent to approximately a proprietary solution that only we can read.” It would not eliminate investors’ regulatory 10 per cent of global trade. Meanwhile, 80 The industry’s direction of travel supports responsibilities, but could make satisfying per cent of surveyed banks expect those that thinking. In October 2026, the them more efficient. Against the backdrop of demands to increase as businesses diversify International Chamber of Commerce’s Digital the ADB’s $2.5trillion trade finance gap, the markets and reorganise supply chains. Standards Initiative renewed its focus on significance is clear. Making trade assets easier Portable Trust is not being presented as interoperability, warning that fragmentation to assess and distribute could help banks a panacea for every cause of that shortfall. across digital platforms threatened adoption recycle capital, increasing their capacity to But reducing repeated verification could at scale. Its next phase prioritises common support underserved businesses. remove one key source of friction, potentially standards, trust and identity, bringing together Portable Trust is part of Eastnets’ broader making smaller transactions more economical technology providers, standards bodies and financial crime technology offering, reflecting to finance. And Miezere says the concept industry participants. demand for connected investigations. is already moving into practical testing. The message is clear: digitising individual Its FinCrime Intelligence Platform, launched “We already have proof-of-concept documents is not enough if the systems in July, is an investigation and orchestration validation with several banks, so we are out handling them cannot communicate. layer connecting AML, sanctions, KYC and fraud of the ideation stage,” she says. Eastnets wants Portable Trust to bridge gaps, workflows, which incorporates explainable AI. Miezere says Eastnets has seen encouraging enabling participants to contribute to, access The company’s expanded relationship with levels of interest following discussions and independently verify evidence across the London Stock Exchange Group (LSEG) brings at the International Trade and platforms. Several applications continuously updated risk intelligence into Forfaiting Association (ITFA) have been identified, with sanctions screening. And recognition from Portable conference, where the cost and proof-of-concept work under way. Chartis Research has also reinforced Eastnets’ Trust needs complexity of establishing trust For example, one focusses on position in trade-based financial crime to be genuinely across multiple institutions were internal bank audits, where prevention. Together, these developments point portable. We raised as being persistent concerns. need to ensure evidence generated across towards a strategy that connects compliance it’s an open Portable Trust is built around departments must be assembled intelligence, transaction processing and digital system, not a straightforward principle: into a coherent regulatory record. trust in trade finance. a proprietary once information has been “Banks are complex organisms,” Eastnets is already exploring further solution that verified, other authorised parties adds Miezere. “One department applications for Portable Trust in insurance and only we can read should be able to validate and can be doing one thing, another tokenised assets, although these remain at Luay Gadallah, reuse that evidence without something else.” an earlier stage of development. Next it will Eastnets starting from scratch. Much of that evidence remains translate promising proof-of-concept work The platform is being developed to scattered across spreadsheets, into adoption across institutions that integrate with digital identity frameworks departmental platforms and We already operate under different regulations, and independent trust registries, creating manual workflows. Portable Trust have proof- technology standards and risk of-concept appetites. Success will depend not a verifiable record of the people, businesses could create a verifiable record, validation and documents involved in a transaction. demonstrating what happened, simply on technical capability, with several A key enabling technology is the verifiable when and whether information was but on establishing common banks Legal Entity Identifier (vLEI), developed altered. It could satisfy regulators standards and confidence in the Baiba Miezere, Eastnets through the Global Legal Entity Identifier without slowing payments. evidence being exchanged. Foundation (GLEIF). Another application involves documentary Eastnets recognises that adoption will Unlike conventional identifiers, the vLEI uses collections in trade finance, where verification happen incrementally. cryptographic credentials to verify not only an evidence could accompany existing Swift “While one is getting implemented, another organisation’s identity but also the authority and MT400-series messages. But perhaps the most is at the ideation stage,” says Miezere. role of individuals acting on its behalf. GLEIF’s compelling opportunity lies in the secondary That pragmatic approach may prove framework, standardised under ISO 17442-3 market for trade finance assets. essential in an industry where innovation in 2024, is designed to support automated Banks frequently sell or distribute assets to must coexist with rigorous oversight. But, if verification across digital transactions. investors, releasing capital for further lending. institutions can exchange verifiable evidence For Eastnets, this provides a foundation on Yet prospective investors must assess the securely, supported by intelligent analysis and which additional compliance evidence, trade underlying transactions and counterparties, without repeatedly reconstructing trust, the documentation and verification results can be often repeating due diligence already benefits could extend beyond compliance. assembled into an independently verifiable undertaken by the originating institution. The opportunity is in building that missing audit trail. Crucially, the original issuer need “That is the use case I like the most,” layer of financial infrastructure, because not remain online for evidence to be checked, Miezere explains. “Investors don’t need to go moving money faster is only half the battle. while notifications can alert participants to and check everything again. They can rely, if The real breakthrough will come when trust changes during a transaction’s lifecycle. they want, on what the bank already did.” can keep pace. 30 THEFINTECHMAGAZINE ISSUE 40
FFNEWS.COM
The digital euro: CBDCs
future-proofing European payments The concept of a digital euro was to give European citizens and businesses greater choice and a trusted, future-proofed means of payment i n the digital age. With its potential arrival in 2029, we discuss preparations, pilots, and how PSPs can benefit Having spent years talking about it, European policymakers are now moving with determination and speed when it comes to digitising the official currency of the eurozone. It’s had to overcome several policy and legal boundaries, but a landmark vote in June 2026 in the European Parliament's Economic and Monetary Affairs Committee allowed negotiations on the digital euro legal framework to move forward. The European Central Bank’s (ECB) digital euro could be issued in 2029, subject to the adoption of the necessary legislation. 32 THEFINTECHMAGAZINE ISSUE 40
Questions remain about how receptive the industry and the public will be. Just a handful of nations are fully live with a central bank digital currency (CBDC) – and none is proving particularly popular. The Central Bank of Nigeria, for example, is refreshing its CBDC strategy to drive take-up of the slow-moving eNaira. In the UK, the Bank of England and HM Treasury are pondering over a multi-year ‘design phase’ for a digital pound following dismal polling among a largely sceptical public, while Trump has made it clear that a CBDC is off the table in the US. If the digital euro is to succeed, the ECB knows it needs to ensure the widest array of stakeholders are fully on board.
UNDERSTANDING THE RATIONALE In a world where digital payments are becoming the norm, the use of cash is declining rapidly as we shift ever more towards online spending. “The digital euro will complement, not replace, banknotes and coins, as well as the range of payment methods we now have across Europe,” explains Mayte Arráez, Head of the Digital Euro Service Platform Division at the ECB. “So it’s another way to pay that will allow citizens to use a pan-European solution across the euro area. It will also serve different use
cases, including person-to-person (P2P) and person-to-business (P2B) payments.” She also highlights it would offer a high level of security and privacy, and its offline functionality would ensure it’s always available, even when there are connectivity issues or temporary power outages. More broadly, a digital euro would help preserve the euro area’s monetary sovereignty and strengthen Europe’s strategic autonomy by improving payment efficiency, fostering innovation, boosting resilience to cyberattacks and technical disruptions, and reducing reliance on US card networks – the last being a long-held ambition. Proponents of the digital euro also point out it would help solve the longstanding issue of payments fragmentation across Europe. The continent is home to local payment methods, such as Bizum in Spain and EPS in Austria, while more than 60 per cent of euro area countries don’t have their own national card payment system. Where such systems exist, they usually only work domestically and are sometimes limited to specific types of payments.
THE NEXT STEPS The European Parliament, the Council of the European Union, and the European Commission FFNEWS.COM
(with technical support from the ECB) are now engaged in formal inter-institutional talks (trilogues) to discuss the specifics of the Digital Euro Regulation. “We expect that it could be approved by the end of the year,” says Arráez. Assuming the required regulation is adopted by the end of 2026, the ECB plans to be ready for a first issuance during 2029. The Eurosystem – which comprises the ECB and the national central banks of the euro area – is keen to ensure the digital euro meets users’ needs. It therefore engages regularly with legislators, market participants, and civil society organisations, as well as members of the public. To lay the groundwork for a seamless and secure launch, the ECB expects to run a 12-month pilot starting in the second half of 2027. Participants will include 36 payment service providers (PSPs) licensed in the euro area (including Stripe, Revolut, and Adyen), selected merchants, and staff from the ECB and 19 national central banks. Together, they will assess a beta version of the digital euro to validate the infrastructure in real-life situations – including the ECB’s cafeteria! – and check it’s robust, user-friendly and scalable.
THE BIGGER PICTURE
The digital euro shouldn’t be viewed in isolation. It’s part of the Eurosystem’s comprehensive payments strategy to modernise European payments and strengthen strategic autonomy. Supporting the development of a European tokenised ecosystem is a key part of the strategy. Pontes is a Eurosystem solution launched in September 2026 that links market DLT platforms and TARGET Services to settle DLT-based wholesale transactions in central bank money. It is a significant milestone on the roadmap towards a future-oriented European digital asset ecosystem. Looking ahead, the Eurosystem’s Appia initiative aims to shape the development of a European tokenised financial ecosystem, exploring how central bank money and other assets could operate in an integrated way using DLT technology. “The Eurosystem supports all forms of digital finance,” says Arráez. “We’re FFNEWS.COM
working with the market to shape solutions. We welcome regulated, safe, and secure tokenised deposits and stablecoins. We’re basically working towards a complete ecosystem where central bank money can be supported in secure settlements.” Project Agorá, the public-private collaboration convened by the Bank for International Settlements (BIS) and the Institute of International Finance (IIF), has already successfully executed initial testing for a shared platform that tokenises wholesale cross-border payments between institutions. It provided operational validation, as well as a practical ‘proof-of-concept’, that will now inform the design of Appia.
PREPPING THE PSPS Providing the schedule runs on time, and the digital euro launches in 2029, then European PSPs and fintechs will be keen to know how they are expected to integrate it. Once the regulation applies and the ECB has authorised issuance, PSPs across the euro area – including commercial banks, e-money institutions and post offices – would be required to offer basic digital euro services.
PSPs will be the entry point for individuals and merchants accessing digital euro wallets. They will onboard users and ensure holding limits are respected Mayte Arráez, ECB “PSPs will be the entry point for individuals and merchants accessing digital euro wallets, so they will onboard users and ensure that holding limits, which will be implemented to ensure financial stability across Europe, are respected,” explains Arráez. “Once the final rulebook is adopted, they will need to take its requirements into account when developing the APIs needed to connect mainly to the digital euro infrastructure.” PSPs inside the euro area will fall under the mandate, but for non-
eurozone providers engagement will be voluntary, allowing them to choose whether to offer digital euro services based on their own business model – though it remains to be seen how this will work in practice. The ECB has made it explicitly clear that the digital euro will not be programmable money. While it will support automated and conditional payments (such as pay-on-delivery services), it will never feature built-in restrictions on where, when or with whom it can be spent. Because basic services must be free of charge for citizens, PSPs can’t rely on standard consumer transactional fees, and will need to generate revenue through value-added services. “While the digital euro isn’t programmable money, we intend it to be a catalyst for innovation,” says Arráez. PSPs will be able to charge merchants management fees, up to a specific cap determined by the regulatory framework, and build and market commercial features on top of the public infrastructure, whether that’s conditional payments, loyalty programmes or even specialised risk and analytics tools. It could also help private payment solutions scale across the euro area by providing common standards and infrastructure. “We’ve signed agreements with different European standard-setting organisations, such as ECPC, nexo standards and the Berlin Group, to ensure we can leverage some existing standards to minimise the impact on banks,” says Arráez. “We’re focussed on open standards that national or cross-border solutions can leverage to expand their reach and services across Europe.” There is a clear plan in place, but there are still some unknowns to work through. It will be important for PSPs to watch closely and react accordingly, as the ECB plots the path to issuance. “The real measure of success will be whether everyone who wants to use a digital euro can do so smoothly,” adds Arráez, “whether that’s paying for a coffee in Lisbon, splitting a dinner bill with friends, or even transacting offline in an Austrian forest.”
Mayte Arráez, Head of the Digital Euro Service Platform Division at the European Central Bank
ISSUE 40 THEFINTECHMAGAZINE 33
FINTECH
MAG A Z I N E
Banks needn’t be the ghost in the machine – a background utility powering the superapp economy. They can be that economy, says S. Sundararajan – and agentic AI will help enable it In the race to embrace the transaction boom, banks have been painfully aware of a critical trade-off: gain massive transaction volumes but potentially sacrifice direct customer ownership. Many spent millions building digital destinations, only to see their customers live, interact and transact elsewhere, leaving them at risk of becoming the ghost in the machine – a silent backend provider for someone else’s front-end experience. It’s a global trend, felt most keenly perhaps in countries where state-backed real-time payment schemes have hoovered up users. In India, for instance, the Unified Payments Interface (UPI) has grown to be the world’s largest real-time instant payments system, processing about 84 per cent of retail payments or 800 million payments a day.
S. Sundararajan, Founder and CEO of i-exceed
Crucially, its open architecture has allowed agile third-party applications to build innovative, consumer-first experiences – feature-rich ‘superapps’ – right on top of secure legacy banking infrastructure. In doing so, they’ve become the primary front door for everything from paying bills and arranging insurance to buying movie tickets, all quietly anchored by UPI. For financial institutions, integrating with these superapps was an initial no-brainer. It offered immediate distribution to hundreds of millions of users and instant scale. Few stopped to consider the long-term erosion of the customer relationship. Now many question that sacrifice: surrendering direct access and brand visibility to third-party ecosystems. There is an alternative, of course: adopt a platform banking model and transform from a product provider into an ecosystem orchestrator yourself. Instead of selling isolated products, such as deposits, loans and payments, the bank curates and integrates financial and non-financial services within its own digital environment. Customers stay in the bank’s environment – not in a fintech’s, a marketplace’s or a technology giant’s. One company offering banks just that choice is India-based i-exceed, whose AI-driven platform banking model, Appzillon, and its agentic upgrade Appzillon AI, are used by more than 125 banks across 25 countries. S. Sundararajan, i-exceed’s Founder and CEO, is keenly aware of the threat
posed by big tech and superapp developers to banks. “At the end of the day, every market is looking at digital transformation: how they can do what they’ve always done, but digitally, faster and better,” he says. “Maturity, regulation and compliance vary from country to country, and that’s the only real difference. Otherwise, everyone is looking at the same industry trends, whether they come from Apple, Google, Facebook or Amazon. Those are the trendsetters, and that’s what gets followed. “Some markets adapt faster than others, while levels of regulation vary. But we have a range of offerings that cater to different customers, allowing us to take the same solutions to markets globally.” Platform banking, i-exceed stresses, is not digital banking (a better channel), open banking (regulated data sharing via APIs), or banking-as-a-service (embedding your infrastructure into someone else’s app). In platform banking, the bank is the destination; it owns the customer relationship end-to-end, sets governance rules for partners, and earns revenue across the entire ecosystem. In essence, platform banking creates a digital economy where, for example, a business owner can incorporate a company, buy insurance, book logistics and pay suppliers – all without leaving the platform. Contrast that with the relatively sparse offerings provided by a regular banking app with a product
PLATFORM BANKING
34 THEFINTECHMAGAZINE ISSUE 40
FFNEWS.COM
catalogue routinely limited to transfers, loan calculators and a payment button – in reality, a digital branch. McKinsey’s Global Banking Annual Review 2025 concluded those banks with advanced digital operating models outperform peers on revenue growth and productivity metrics. Of course, any major digital transition requires investment, but i-exceed stresses that most banks do not need a new core. They need an orchestration layer above it. Appzillon is just that: a composable, low-code digital banking platform which sits above legacy core systems, enabling banks to launch partner integrations in weeks via API-first architecture, sandbox governance, and AI-ready data layers, without the multi-year risk of core replacement. Sundararajan says Appzillon’s extended AI capabilities also enable it to fast-forward that transition for its customers. “Over the last two years, the industry has been going through rapid change because of AI,” he says. “That is having a tremendous impact on what we do and how we do it, both in how we deliver software and in what we give to our customers. “We have traditionally offered digital transformation and digital banking solutions. With AI, we can accelerate the whole delivery journey, and we can give more to the bank’s end users when they use the app: making it more automated, less manually intensive, and bringing more intelligence into it through AI. “That’s what we have been offering as added value. We are fully embracing the power of AI and bringing in the intelligence that’s needed, based on what customers have done in the past.”
FFNEWS.COM
Sundararajan says i-exceed has set itself strict parameters in its mix of controls, checks and balances so agentic AI earns the trust of banks and their customers. “That’s the only way to increase adoption: by showing the end user that it is credibly doing the right thing,” he says. “More importantly, every agentic AI capability we introduce has to do two things: “First, it has to solve a real-life problem. Is the end user doing laborious, monotonous work? How can that be automated or pre-populated, and how can we reduce the manual effort? “Second, whatever the AI does, we need the right validation mechanisms and guardrails, and we need to keep verifying that it’s doing the right job. We start with manual validation and control, and once it improves, we automate that validation.
Everyone is looking at the same industry trends, whether they come from Apple, Google, Facebook or Amazon. Those are the trendsetters, and that’s what gets followed
“We take one use case at a time, validate it fully, then take it into the solution. That’s how we are increasing AI adoption overall.”
BANKING ON INTELLIGENCE Looking ahead, Sundararajan forecasts that AI will help create ‘intelligent banks’ where successful data analysis will allow them to offer better services and products to their customers. “Essentially, it’s using intelligence to work out what the customer needs,” he adds. “We’ll use available data, along with agentic AI, to give better service, product recommendations and address real needs. So, over the next three to five years, it will be about becoming an intelligent bank: using data and AI to offer an intelligent service to the customer.” Sundararajan is confident of the banks’ longevity, despite the maelstrom of change. “Many organisations are offering financial services – a great example is buy now, pay later. Any industry can now offer financing and lending to its customers. “In our view, banking will remain. But will it only be through the banking app or the branches? Probably not. Those will be one channel. The other channel will be wherever customers already are. If they’re in a shop and need finance, that’s the entry point. If they’re at home and want to buy something, that’s the entry point to a financial product. “So banking will remain, but the entry point won’t necessarily be the app, the ATM or the branch. It will be wherever we live, wherever we operate, whatever we do. “The bank, through APIs and a composable architecture, gets embedded into the end customer’s overall journey. That’s the transformation we see over the next three to five years.”
ISSUE 40 THEFINTECHMAGAZINE 35
REUSABLE IDENTITY
Momentum is building for a reusable digital identity that allows banks to process corporate requests quickly and securely. Royal Bank of Canada and technology partner Encompass share their experience of implementing just such a data passport Perhaps the biggest victim of the recent $6.3billion Binance hack – the single largest cyber heist in history – was trust. Bosses there know that particular commodity is the hardest won and most precious of all. It’s why Binance immediately pledged to cover 100 per cent of client losses and has set aside company funds to do so. How big a hit its reputation – and wider confidence in the industry – will take is not yet clear. Whether you’re a cryptocurrency exchange or a regulated bank, verifying identity is critical before releasing the keys to the vault. It’s why bank-grade digital identity for citizens and corporates has gained traction worldwide.
36 THEFINTECHMAGAZINE ISSUE 40
Where adoption is widespread, the impact is impressive: in Norway, where BankID is used by 97 per cent of individuals, it has helped reduce fraud to a staggering 0.00042 per cent of total payment volumes. In a report last year, the UK’s Centre for Finance, Innovation and Technology (CFIT), a coalition of banks, technology partners, public sector bodies and regulators, highlighted digital ID’s potential to cut business verification and know-your-business costs by more than 50 per cent. It also claimed to reduce the time taken to verify and onboard businesses by 60 per cent. Know-your-customer is tough enough in a retail banking environment, but
know-your-corporate is a whole lot more complicated as cyber criminals employ ever more sophisticated methods, such as synthetic identities, spoofed corporate senders, fake vendor profiles, and high-tech AI deepfake video and audio clips. Technology provider Encompass, which was one of the partners involved in the CFIT digital ID report, has already built a Corporate Digital Identity (CDI) platform for Tier-1 banks called EC360. Outlining its competitive advantages, Roger Carson, Co-founder and Executive Director of Encompass, says: “There are two key aspects to Corporate Digital Identity for corporate and commercial banking clients and providers.
FFNEWS.COM
“One is trust. You have to be able to “That is something that you need to A robust KYC framework with CDI is fully trust the data that you’re using so take into consideration from a risk critical to the bank meeting their that your outputs are 100 per cent profile. So how does that client look in expectations for real-time services. every time – not 98 per cent, not 99 its entirety across all of the connected “Real-time is only as good as the per cent, but 100 per cent. elements of that client?” content flying through it. It’s about “And the other is that speed is of That clunky but absolutely essential speed, ease and accuracy. If we don’t vital importance. Banks seem to have client record due diligence maintenance have a proper KYC and a proper client solved the retail banking problem in process causes a mismatch between identifier at the front, we put a wrench terms of delivering services and security, speed and the client’s own into everything that we’re doing, which products quickly to their customers. expectations vis-à-vis the service it will slow down the whole process,” he The corporate banks need to be able receives from the bank. says. “So we won’t be taking advantage to do the same. With Corporate Digital “I’ll give you an example. If you think of a real-time rail and the speed with Identity, they’re able to deliver at the about speed asymmetry,” continues which we can execute.” speed they need to deliver to their Messer, “when we’re onboarding a The benefits of CDI for the bank and its customer base. If a bank doesn’t do client, a client can move at market pace. corporate customers are considerable. that, other banks will.” If it wants to execute a transaction “By having a proper client identifier, Royal Bank of Canada’s Capital quickly, if it wants to arrange financing we can start linking all those pieces Markets business has been quickly, it can move at that speed. together and remove one more step that automating its know-your-corporate “It’s when financial institutions step could possibly add friction and delay.” processes, working with its in and say, wait, you need to clear your Echoing Messer, he explains: “Instead compliance technology providers, identity verification process with us. of taking time and resources to put including Encompass, for some time. You need to wait until all of our KYC KYC in place at different connection Lori Messer, US COO and Global frameworks are executed appropriately. points, we can move those resources Head, Cross Product at “If you think about it from a client into a client experience. RBC Capital Markets, perspective, that could “In the context of global transaction emphasises how lead to a competitive banking, entities have different Banks seem complexity is a key disadvantage for them. subsidiaries and if we have proper client to have solved the differentiator in And it could also lead identifiers and look at an entity as an retail banking problem carrying out KYC to a missed revenue entire group of companies right across in terms of delivering protocols in opportunity for the globe, we can start to penetrate services and products corporate cases, the financial better and deliver a seamless client quickly to their customers. compared to institution.” experience instead of spending our time The corporate banks the relatively Encompass, asking for more documents.” need to be able to straightforward whose CDI platform RBC has taken the decision to embed do the same equivalent in is also used by agentic AI into the CDI process. Roger Carson, retail banking. major banks including “We’re building CDI as a structured Encompass “One of the core J.P. Morgan and ING, agentic capability, not an internal differences between CDI in retail envisages playing a key process,” says Messer. “For versus capital markets and transaction role in a global framework clients, that means faster, We’re banking is the fact that identity in a supporting ‘perpetual more transparent building corporate retail environment is an individual KYCorporate’. Under onboarding. And, as we digital identity as whereas when you’re talking about this model, banks start to seamlessly a structured agentic capital markets and transaction would obtain most integrate that CDI capability, not an banking, you’re talking network agentic framework of the information internal process complexity,” she says. into client lifecycle needed for corporate Lori Messer, RBC “A corporate client, for example, is management verification from trusted Capital Markets not often just a single entity. You’re ecosystems, into our AI external sources, ‘only dealing with a web of subsidiaries, platforms, across capital reaching out to clients when with multiple beneficial owners. markets, for example, it’s allowing it’s really needed’. Related entities, counterparties. our teams internally to have a more In August, Royal Bank of Canada “And when you are trying to comprehensive and real-time view of launched a unified Global Transaction transact, whether it’s a transaction what our clients look like.” Banking business. Michael Klopchic, its in a capital markets environment, RBC’s use of an AI platform is built Global Head of Client Coverage, says arranging financing or managing within a strict framework of governance three priorities underpin the bank’s collateral, you need to not only know with clearly articulated guardrails, approach: consolidation, simplification who your client is, but who they’re and human expertise remains a vital and digitisation, brought together to connected with. part of the process, says Messer. deliver a better client experience.
FFNEWS.COM
Roger Carson, Co-founder and Executive Director of Encompass
Lori Messer, US COO and Global Head, Cross Product at Royal Bank of Canada's Capital Markets
Michael Klopchic, Global Head of Client Coverage for Global Transaction Banking at Royal Bank of Canada
ISSUE 40 THEFINTECHMAGAZINE 37
FINTECH
MAG A Z I N E
Asked what questions RBC Capital Markets considered when establishing those guardrails, Messer says: “Where can the AI platform make autonomous decisions? How do we document the actions and the decisions that the AI platform takes to make it more auditable and transparent? How does the AI platform need to connect with humans in the loop when there is a high-risk scenario or there is an expectation that humans step into the process? “I think talent is really essential to this, but it’s more than data scientists and AI engineers. It’s about having the subject matter experts who understand the business, who understand technology, and also understand the regulatory and operational context.” Consistent delivery and explanation of rational reasoning by agentic AI will give users confidence, which allows RBC to scale rapidly, says Messer.
“Closing the gap between trust and to arrive at the right decision, it should admit capability, in my opinion, requires three key that it can’t and that it requires human things,” she continues. judgement to intervene. “First, transparency. An AI platform or “This humility of the agent instils trust agent makes a decision. It should be able to in the humans who are relying on the explain its rationale, provide the data agent or the AI platform. points, provide the logic on how “So I think it’s transparency, It’s about it arrived at the decision or the consistency and this consolidation and action that it took. sentiment of graceful failure digitisation and ease “Two, consistency. If will help bridge the gap of doing things. If the AI agent is delivering between trust and we get CDI right, we consistent outcomes in capability quickly.” can make the client analogous situations or According to Klopchic, if experience that scenarios, it starts to the industry gets behind build greater confidence CDI, ‘the prize is multifold’. much better Michael Klopchic, with the people that are “It’s about consolidation RBC relying on the platform and and digitisation and ease of the agents involved. doing things,” he says. “If we get “And the third one is what I call graceful it right, we can make the client experience failure. When an AI agent or platform is unable that much better.”
Corporate Digital ID in the UK The case for a ‘Digital Company ID’ is being made most forcefully in the UK by the Centre for Finance, Innovation and Technology (CFIT), which counts Encompass among its supporting partners. CFIT brings together a coalition of leaders from finance, technology and academia to work alongside regulators, and it’s made introducing corporate digital identity a lodestar for improving UK business efficiency, security and trust. It claims CDI could save billions of pounds a year in lost revenue through fraud, slash the costs associated with red tape and claw back time for banks and businesses alike. It could also catalyse different use cases across sectors, says CFIT. The coalition has called on policymakers, industry leaders and regulators to collaborate in driving forward Digital Company ID, which, it argues, will reinforce the UK’s position as a leader in digital innovation and financial security. 38 THEFINTECHMAGAZINE ISSUE 40
Businesses, it seems, are open to the idea. A survey among 403 UK decisionmakers found that three-quarters (74 per cent) would adopt a reusable Digital Company ID today and 83 per cent said it would be worth paying for. Almost half (48 per cent) said they would adopt it when widely accepted by the financial institutions they bank with. The greatest demand came from businesses facing the most banking friction. Top of that list were those with complex ownership structures – including overseas shareholders, multiple jurisdictions or trust arrangements. They were more than twice as likely as simple businesses to be told to make an in-person branch visit to complete a verification process. They were also close to three times more likely to be chased for additional documents three or more times after applying for an account. Tougher anti-money laundering (AML) rules have substantially raised the evidential bar
for identifying who ultimately owns and controls a business. So it perhaps was not surprising that complex businesses said gathering shareholder and beneficial owner information was their single biggest cause of delay (28 per cent). Among these more complex businesses, 64 per cent said they would adopt Digital Company ID now if it were accepted by financial institutions, and 67 per cent would pay a meaningful amount for it. Interestingly, an analysis of 22 Financial Conduct Authority enforcement cases found that data and documentation failures were contributory factors in 68 per cent of them, illustrating maybe that the utility of reusable digital credentials goes way beyond the everyday banking relationship. FFNEWS.COM
FINTECH
MAG A Z I N E
Reınventıng AGENTIC AI
Crédit Agricole is investing in AI across its estate, but its trade finance platform Optimtrade is leading the way The next generation of trade finance transactions could begin with a conversation between two AI agents: one acting for a corporate client, the other connected to its bank. They’ll exchange information, review documentation and potentially initiate transactions without navigating traditional banking platforms. For Crédit Agricole, this future is already taking shape. It’s earmarked €500million to invest in AI and the European technology partnerships to deliver it between now and 2028. And it’s created an AI enterprise, Crédit Agricole Artificial Intelligence, that will impact every aspect of the organisation, including its Corporate and Investment Bank (CIB). “Ultimately, instead of simply reacting to a payment or a trade instrument, you’ll have a new player, an AI agent, acting on someone’s behalf: answering requests, or actually pushing trade and payment instruments,” says Etienne Bernard, CIB’s Deputy Head of Global International Trade & Transaction Banking. That means the bank must establish not only who its corporate customers are, but also the identity and authority of the systems representing them – and fast. “Instead of the KYC (know your customer) we’re used to, we’re going to move to KYA (know your agent),” Bernard predicts. The relentless global contraction in transaction and 40 THEFINTECHMAGAZINE ISSUE 40
Etienne Bernard, Deputy Global Head, International Trade & Transaction Banking and Global Head of Sales and Advisory at Crédit Agricole CIB
settlement times is a major incentive for the Group to embed agentic AI into all its internal processes. The entire bank must accommodate growing volumes of real-time and instant payments while managing the operational, fraud and compliance risks that faster processing creates for both domestic and cross-border payments. Bernard points to initiatives including the One-Leg Out Instant Credit Transfer (OCT Inst) scheme, which extends SEPA Inst beyond the EU by executing international, cross-border payments in under 10 seconds, 24/7/365. As payment flows increase, banks ‘must react online, in real time, to the specifics of each payment’, says Bernard. For CIB, which generates a third or more of its business outside of Europe – often where real-time and instant payments are the norm – agentic AI offers the prospect of scaling business without proportionately increasing costs or workloads. That’s particularly relevant in trade finance where the sheer number of documents, multiple counterparties, regulatory requirements and approvals needed before the money moves can add significant delay.
Raising the AI stakes Trade finance is being supported with a specific solution. In September, Crédit Agricole CIB announced plans to integrate agentic AI into Optimtrade, its trade finance platform developed with
Hands across the world: AI will connect corporates and banks through increasingly autonomous systems
Komgo. The proposed agent will enable clients to upload trade documents, extract information and populate draft instructions for letters of credit, bank guarantees and standby letters of credit. Clients will also be able to query transaction data using natural language, accessing outstanding instruments, exposures and maturities without navigating dashboards. For Bernard, this represents a shift in how banks serve clients. “First, it’s about the offer. How can we change this to make it more attractive for our customers?” he says. He envisages agents handling sophisticated activities across both cash and trade finance. “As a customer, as a financial institution, you receive an RFP (request for proposal). At the same time, without FFNEWS.COM
doing anything, the agent can answer the RFP, look at the pricing, or whether you need to issue a guarantee, and basically do it on its own.” The next step would be to allow clients to connect their own AI agents securely to Optimtrade using model context protocol (MCP), so they could access information and initiate workflows from existing corporate systems rather than banking platforms. Although the technology remains exploratory and future transactional autonomy is unconfirmed, it points the way to fully integrated agent-to-agent trade.
Unlocking value from data AI’s utility to trade finance has already been
proven elsewhere. In June, the bank launched Smart Platform Assisted SustainablE (SPASE), an AI-powered, ESG-linked trade finance solution in Asia-Pacific. SPASE turns transaction data into ESG dashboards covering suppliers, products and trade flows, helping corporates assess sustainability, improve supply chain transparency and identify commercial opportunities. Following a pilot with a Hong Kong-based regional sourcing hub, Crédit Agricole CIB plans to expand SPASE across Asia-Pacific. The solution demonstrates how AI can turn trade data into actionable business intelligence, and builds on digitalisation encompassing electronic bills of lading, digital guarantees, API connectivity and a dedicated trade data hub. More broadly, Crédit Agricole Artificial Intelligence, operational since October 2026, develops shared infrastructure for the Group. It FFNEWS.COM
has partnered with French AI developer Mistral to support industrial-scale deployment, including agentic transformation of banking processes, conversational assistants and cybersecurity. Meanwhile, European technology provider Prisme.AI is supporting Sécur’IA, the bank’s secure platform enabling employees to design and deploy AI agents connected to Crédit Agricole’s systems. Both initiatives form part of the Group’s ‘AI for All’ programme, combining adoption with governance and human oversight. The strategy reflects Crédit Agricole’s emphasis on European technological sovereignty. Combining private cloud infrastructure with European partners and adapting models to its data should help
With greater autonomy, comes greater responsibility Yet autonomous financial systems introduce a fundamental tension. As transactions accelerate and banks delegate responsibility to agents, boundaries around authority, accountability and risk become critical. Crédit Agricole emphasises supervised AI rather than unrestricted automation. Friedblatt and Assayag argued that while AI reduces repetitive workloads, specialist judgement remains essential for legal interpretation, exceptions and sensitive decisions. That distinction becomes harder as agents move from preparing documents towards initiating transactions. Bernard’s KYA concept raises questions beyond traditional KYC. How should banks authenticate agents? What permissions should they have? How can instructions be verified, and who is responsible when an autonomous system makes a mistake? Faster payments compound these challenges, reducing time to detect an erroneous activity or intervene. AI-powered sanctions screening, fraud detection and compliance will therefore be as important as faster execution. It will, Bernard believes, demand collaboration between banks, fintechs and technology providers. Crédit Agricole’s partnerships with Mistral, Prisme.AI and Komgo illustrate this interconnected ecosystem. In transaction banking, where payments and trade instruments cross institutional boundaries, these relationships are fundamental.
Ultimately, instead of simply reacting to a payment or a trade instrument, you’ll have a new player, an AI agent, acting on someone’s behalf
retain control over critical systems, manage dependencies and optimise computing costs. In Global Trade Review, Etienne Bernard, Crédit Agricole CIB Crédit Agricole CIB executives Vincent Friedblatt and Ludivine “We use some [technology providers’] Assayag argued that innovation must products to give our customers a better, more move beyond digitising documents towards complete offer,” Bernard explains. “A few fundamentally redesigning workflows. The Siboses ago we were discussing whether it’s bank has applied AI to guarantee vetting, competition or partnership. Actually, we have document examination and compliance, the answer: it’s both. As banks, they’re my while improving interoperability between competitors, but they’re also my friends.” corporate and banking systems. How far banks adopt that approach will For Bernard, internal efficiency matters define whether AI delivers isolated efficiencies equally: “There’s a lot of efficiency we or transforms global trade. can bring to our back office, thanks to AI: Bernard fully expects agentic AI to reshape better, more efficient, more reliable transaction banking. customer service,” he says. “I think agentic AI is the technology that AI also helps sales teams understand will really evolve over the year ahead,” he says. markets and client needs. “And it will change customer behaviour.”
ISSUE 40 THEFINTECHMAGAZINE 41
The strongest link: Ultimately, every form of asset will meet at a crossroads in a chain
TOKENISATION
Blockchain is fundamentally changing the way global finance operates. The challenge now is interconnectivity Andrew McCormick has watched the banking industry’s opinion of blockchain go through three distinct stages, and the third one has arrived rather suddenly. “Ten years ago, it was this novel idea, where large institutions were wondering, what is this?” says McCormick, who joined Chainlink Labs in June as Head of Institutional and Market Development after running eToro’s US business. “A couple of years ago, it became more like ‘this sounds interesting, what can we do in this space?’ And then, probably 12 to 24 months ago, that conversation changed rapidly to ‘we want to build, and we want to build now!’” For McCormick, the clearest signal came when the market turned. “Last fall, the prices of digital assets went
42 THEFINTECHMAGAZINE ISSUE 40
down, but the building only went up,” he says. “To me, that was a really big signal that this is no longer just about the hype, the memes, the excitement, the price, but the infrastructure.” The change was visible on the show floor at Sibos, Swift’s annual gathering of the banking world, in September. “It’s interesting going from there to a crypto conference,” McCormick says. “In crypto there are a lot of t-shirts and jeans, and Sibos is all suits.” The suits, it turns out, wanted to talk. “We had so many people coming to our booth asking ‘how can we use Chainlink to build on the blockchain?’” The evidence goes well beyond one busy stand. The same institutions are starting to show up at crypto conferences, too, showing how the industries are converging. Momentum is gathering.
Sergey Nazarov, Co-founder of Chainlink
Andrew McCormick, Head of Institutional and Market Development at Chainlink Labs
In March, the SEC approved Nasdaq’s proposal to let Russell 1000 stocks and major index ETFs trade in tokenised form. In June, The Clearing House (TCH), owned by a consortium including J.P. Morgan Chase, Bank of America, Citi and Wells Fargo, was reported to be building a shared network for tokenised deposits, due as soon as the first half of 2027. In late September, Coinbase, Mastercard, Shopify, Stripe and Visa put more than $1billion of launch liquidity behind Open USD, a stablecoin with reserves held at BlackRock and BNY. And at the end of October, DTCC switched on its tokenisation service, with 20 firms including Barclays, Morgan Stanley and UBS signed up. “For years, Chainlink and other digital asset entities and networks have been talking about tokenisation,
FFNEWS.COM
blockchain, stablecoins. Now it’s happening,” says McCormick. “The pilots to production, it’s happening.” The numbers are still small, but they are growing fast. McCormick puts the market capitalisation of tokenised assets at around $5billion, up from a few billion a couple of years ago and a couple of hundred million before that. Citi has estimated that tokenised securities could reach about $5.5trillion by 2030. What really matters, in McCormick’s view, is who is doing the building. “Major US institutions like the DTCC, the New York Stock Exchange and Nasdaq, are all taking time out from their day-to-day business and saying, ‘hey, blockchain technology is the future. We are going to the government to get approval to make sure we can offer products on the blockchain and tokenise assets’,” he says. “If those kinds of institutions are moving into this space, all the others will follow.” Chainlink Co-founder Sergey Nazarov says this is precisely how he thought things would unfold. “I expected pretty much every institution in financial market infrastructure (FMI) would need a chain,” he says. “You’re seeing many FMIs, banks, spin up their own chains, right? TCH has a chain, Swift has a chain, DTCC has a chain. If you talked to people three years ago, that wouldn’t have seemed likely.”
Major US institutions like the DTCC, the New York Stock Exchange and Nasdaq, are all taking time out from their day-to-day business and saying, ‘this technology is the future’ Andrew McCormick, Chainlink
These are not science projects, Nazarov adds. They have ‘real budgets and real teams and real owners’, with support at managing director level. “So everyone’s going to have one. There’s going to be a tonne of different chains.”
Beyond payments Much of the early talk about blockchain in banking focussed on payments, and with good reason. McCormick’s case for instant settlement is hard to argue with: “Instead of transferring money and waiting a day, two days, over a weekend or three days for a holiday, people are able to move money instantaneously.”
FFNEWS.COM
The bigger change is that the money itself becomes programmable. “With automation, you can programme what you want to do in advance and it can move in real time,” McCormick says. That opens up parts of finance that payments never touched. Take collateral, which McCormick calls the ‘lifeblood’ of securities markets, with trillions of dollars lent every day. “Today, how it works is that people get on telephones, send emails to lots of possible counterparties, asking them for six, five, four per cent,” he says. “If something is relying on a phone call and it’s a weekend or it’s night-time, there’s a lot of risk there.” Smart contracts, he argues, can automate those agreements and put every available rate on a single screen. The aim is ‘not to displace the existing arrangements and networks and firms, but to give them a better tool to manage risk’. As a former regulatory lawyer, McCormick has a view on the role of compliance in all of this. “I don’t think compliance will ever be an accelerator, in the sense that it is going to advance product development,” he says. “But set your compliance requirements once through smart contracts and you can make sure that they’re actually applied. And you’re not relying on a human to look at every single thing manually. The human is still involved, but they’re getting a lot of help.” Crucially, banks do not have to tear anything down to get there. Through Chainlink’s partnership with Bottomline, McCormick says, a bank already sending payment instructions over Swift ‘can do the exact same thing now’, with settlement moved on chain, ‘so that user is getting their money in seconds rather than days’. Banks, he says, don’t need to throw away years of controls, governance, history and processes. But there’s a catch, isn’t there? If everyone is going to have a chain, then everyone is going to have a slightly different chain, and financial services has seen this kind of splintering hold it back before. Each previous wave of technology, from proprietary messaging formats to core banking systems that refuse to talk to one another, has left behind its own islands of data and liquidity. Nazarov thinks the silos are already forming inside the banks themselves. Stablecoins, tokenised deposits and even central bank digital currencies are, to him, all just ‘different forms of on-chain cash’. Tokenised equities are another category, and on-chain
commodities will be a third. Each lands on a different desk. “If you’re in payments, you’re not so worried about tokenised equities, you’re worried about tokenised cash,” he says. “If you’re in the markets group and you’re working on the security side, you’re worried about tokenised equities.” What most institutions have not yet grasped, he argues, is that these assets will inevitably collide. “Once you have enough of an asset on a chain and enough of another asset, they necessarily will interact. People will buy more tokenised equity with tokenised cash. They’ll both be used as different types of collateral and different loan agreements,” he says. “I don’t think people fully understand this next stage yet. There’s a lot of fragmentation right now, and that fragmentation is only going to grow.”
Once you have enough of an asset on a chain and enough of another asset, they necessarily will interact. I don’t think people fully understand this next stage yet Sergey Nazarov, Chainlink
This is, of course, what Chainlink is purpose-built to fix. The clue is in the name. If the future of finance is hundreds of institutional chains, somebody has to link them, and Chainlink is filling that role because, without the plumbing, tokenisation risks recreating the old fragmentation on new rails. Not everyone is moving at the same speed. A Broadridge survey in July, reported by Forbes, found that 84 per cent of North American financial executives saw tokenisation as strategically important, but only 26 per cent said their firms were actually in production. Strategy decks are still running some way ahead of the systems behind them. McCormick is not worried. “I think 2027 is going to see a massive explosion, in a good way,” he says. Nazarov goes further. Once enough assets are on chain and interacting, he predicts, the shift will seem so obvious that nobody will remember doubting it. “It’ll be just like, duh, obviously that is what happens,” he says. “And at that point, it’ll be truly unstoppable.”
ISSUE 40 THEFINTECHMAGAZINE 43
LENDING A HAND SME FINANCE
Small businesses in the Middle East and South East Asia aren’t getting the credit facilities they deserve – and banks aren’t seeing the profit from them. Tuum has a blueprint that could help both
As financial institutions across the Middle East and South East Asia race to modernise, banking technology provider Tuum sees an opportunity to transform how smaller businesses access finance. According to Regional Senior Executive Manzar Zaidi, the growing influence of superapps is driving a new era of SME lending – one in which, he believes, banks can still play a big part. Smaller businesses encounter familiar obstacles when seeking finance through traditional routes. Lengthy applications, limited credit histories, inflexible lending criteria and unsuitable products all contribute to their frustration. For financial institutions, the challenges in overcoming them are often technological. Legacy systems make it expensive and time-consuming 44 THEFINTECHMAGAZINE ISSUE 40
to introduce products, automate credit decisions or respond to changing expectations. For Tuum, addressing these shortcomings is central to its expansion into the region. A solution is also key to boosting wider economic growth. According to the Asian Development Bank’s Asia Small and Medium-Sized Enterprise Monitor 2025, SMEs make up 99.8 per cent of businesses and account for 67.6 per cent of employment across 26 Asia-Pacific economies, based on data through 2024. Yet their contribution to economic output averages 38.7 per cent, underlining the importance of improving productivity, investment and access to finance. Tuum is pursuing opportunities across Asia-Pacific through partnerships to improve those metrics, but Zaidi says regional dynamics differ markedly. In the Gulf, transformation is driven largely by national economic strategies and established banks. Saudi Arabia’s Vision 2030 aims to increase SMEs’ contribution to GDP from 20 to 35 per cent, pressuring banks to develop more responsive lending services. The financing landscape is changing, too. According to Saudi Central Bank figures, outstanding credit facilities to micro SMEs reached SAR489.2 billion in the first quarter of 2026, up 28 per cent year-on-year. Banks accounted for approximately 95 per cent,
Manzar Zaidi, Regional Senior Executive at Tuum
demonstrating their importance even as digital lenders and embedded finance providers seek a greater role. The challenge here is making credit faster and easier to access. South East Asia presents a different picture. Across Singapore, Malaysia and Indonesia, fragmented SME populations and digital marketplaces are already reshaping financial services. “The Gulf relies on top-down, sovereign mandates like Saudi Vision 2030 driving highly capitalised legacy banks to modernise quickly,” Zaidi explains. “South East Asia operates bottom-up, driven by a fragmented SME base and dominant digital marketplaces demanding embedded finance capabilities.” In both regions, traditional core banking systems place constraints on SME lending. Banks introducing products can face lengthy development cycles, expensive system changes and manual processes. And it’s this that Tuum seeks to address. “Banks regret sticking with their legacy core instead of modernising because they suffer slow product launches, bear heavy costs for every regulatory change, and lose lucrative SME merchants to agile digital challengers,” says Zaidi. For banks wary of rip-and-replace, Tuum argues that phased modernisation offers an alternative. FFNEWS.COM
Its modular, API-first cloud-native platform manages accounts, payments and lending alongside existing core systems. It allows banks to introduce SME lending capabilities without immediately replacing their entire infrastructure. For example, an established bank could launch a dedicated SME lending proposition while retaining existing infrastructure, introducing further capabilities progressively. Zaidi says this can generate revenue sooner, reduce subsequent launch costs and clearly demonstrate the business case before wholesale migration. “A traditional bank can realistically launch its first SME lending product in a few months rather than years,” he says. While Gulf banks confront legacy modernisation, APAC institutions must also compete for SME customers with digital platforms. In several South East Asian markets, superapps, marketplaces and payment ecosystems have become important entry points for SMEs seeking finance. “Traditional banks should compete by adapting their products to integrate directly into these digital ecosystems rather than forcing SMEs into standalone banking apps,” Zaidi argues. An Indonesian marketplace, for example, could offer sellers working capital loans within their existing commercial journey, with the financial product supplied by a bank. This creates opportunities for banking-as-a-service (BaaS) and embedded finance, but raises questions about who owns the customer relationship. Zaidi expects banks to fulfil both customer-facing and infrastructure roles. “A bank retains the ultimate regulatory and risk relationship, while platforms own the distribution and user experience,” he says. Banks need more than APIs (application programming interfaces). Core systems must deliver products through external partners while preserving control over pricing, risk and the ledger. Fast onboarding and configurable products are essential. Tuum believes its architecture can offer all this, allowing distribution through banks’ own channels or third-party platforms.
Partnerships for progress Partnerships are central to Tuum’s plans for international expansion. In December 2024, it announced a collaboration with Audax, a digital banking technology provider incubated within Standard Chartered Ventures. Initially focussed on the Middle East, the partnership combines Tuum’s core banking infrastructure with Audax’s digital banking FFNEWS.COM
capabilities, supporting incremental modernisation and BaaS. The relationship also forms part of Tuum’s APAC strategy, where it has not established the same direct presence as it has in the Gulf. Zaidi points to APAC’s fragmented regulatory landscape, differing data-hosting obligations and Islamic finance frameworks as reasons for working through partners. The company’s longer-term ambition is to capture demand for phased core modernisation among established APAC banks. A direct presence in Singapore or another regional market remains possible, but Zaidi says investment would depend on securing a critical mass of live customers. No timetable has been confirmed. Another partnership, announced in September 2025, addresses SME lending more directly. Tuum’s collaboration with Abwab.ai combines AI-powered credit decisioning and
Banks regret sticking with their legacy core because they suffer slow product launches, bear heavy costs for every regulatory change, and lose lucrative SME merchants to digital challengers alternative data with its lending infrastructure, targeting banks and non-bank lenders across the Gulf Cooperation Council. The proposition is to help institutions assess businesses with limited conventional credit histories while automating loan origination and servicing. Zaidi says the companies are exploring architectures to reduce SME credit decisioning times from 14 days to under three minutes. Still in development, it nevertheless illustrates the improvements being targeted. He sees similar potential in South East Asia, where marketplace transactions and e-wallet payments could provide additional information about smaller businesses’ financial health. Tuum would manage the lending lifecycle, while credit assessment partners and data sources could be adapted to individual markets. The challenge for lenders will be translating these capabilities into faster decisions without compromising credit quality, transparency or regulatory compliance.
Finance that fits An ambition shared by the Gulf and parts of South East Asia involves supporting Islamic banking alongside conventional products. For institutions operating across Saudi Arabia, Malaysia and Indonesia, Sharia-compliant SME finance involves more than replacing conventional interest charges with alternative calculations. Islamic financing can also require different contractual structures, asset-based arrangements and profit-calculation mechanisms. Core systems must accommodate each jurisdiction’s governance and compliance requirements, too. Zaidi argues that a flexible calculation engine is vital, enabling banks to manage trade-based or asset-backed financing structures. Tuum’s approach is to support conventional and Sharia-compliant products on one platform while maintaining appropriate separation between their financial arrangements and accounting treatment. Malaysia and Indonesia have established national frameworks for Sharia governance, while arrangements across the Gulf differ by jurisdiction and institution. Banks therefore need technology capable of accommodating local requirements. Zaidi sees Sharia-compliant asset-based lending, combined with digital onboarding and AI-assisted credit decisioning, as a promising opportunity for SME finance – subject to individual suitability assessments for individual jurisdictions with their different contract structures and suitability requirements. Tuum’s modular approach has attracted industry recognition, including its positioning as a Leader in QKS Group’s 2025 SPARK Matrix for Retail Core Banking Systems across EMEA (Europe, the Middle East and Africa) and APAC. But for banks considering modernisation, recognition is only part of the equation. Implementation timelines, regulatory readiness, delivery risk and measurable commercial returns will determine whether a new platform justifies investment, while for SMEs, faster credit assessments and more flexible products matter only if they translate into improved access to finance. For Tuum, success in the Gulf would mean providing core lending infrastructure to major established banks. In APAC, the ambition is to enable financial products across diverse digital ecosystems. Ultimately, it wants to see small business owners in Riyadh and Jakarta applying for finance and receiving the funds they need that same day. ISSUE 40 THEFINTECHMAGAZINE 45
HELLO PAYMENT RAILS
The Clearing House in the U.S. is about to offer so-called One-Leg-Out 24/7 cross-border payments processing over a familiar rail. Here, it’s joined by Form3 to tell us about the technology challenges and what comes next
While consumers and businesses increasingly expect transactions to complete in seconds, cross-border transfers still involve multiple intermediaries, extended settlement times and uncertainty over when funds will arrive. But given the gargantuan task of replacing correspondent banking, what if financial institutions could make better use of existing infrastructure? That’s the proposition behind One-Leg-Out (OLO), an approach combining established correspondent banking arrangements, supported by Swift messaging, with domestic instant payment networks. Rather than requiring instant payment systems in different countries to connect directly, OLO enables the first or final domestic stage of an international transaction to use a domestic real-time rail. While OLO doesn’t make every stage instantaneous, it could remove significant friction, particularly outside conventional banking hours. With stablecoins and tokenised deposits attracting increasing attention, it’s likely that the future of international payments will depend as much on connecting existing systems like this more intelligently as it will on developing completely new infrastructure. In the U.S., The Clearing House’s RTP® network is preparing to support these 46 THEFINTECHMAGAZINE ISSUE 40
transactions, providing round-the-clock domestic clearing and settlement. Form3, meanwhile, provides cloud-native payments infrastructure across multiple markets. Here, they tell us why they believe OLO is a sensible step forward.
THE FINTECH MAGAZINE: Rather than replacing existing correspondent banking systems, OLO proposes connecting them with domestic instant payment networks. How significant a breakthrough could this be and why now? PAT ANTONACCI, THE CLEARING HOUSE: It drives what we’re looking for from an instant payment environment – moving that from the domestic to allowing it to be delivered cross-border. Whether it’s the first leg leaving the U.S. or the last leg coming into the U.S., it’s about facilitating that cross-border component and settling dollars in real time, leveraging the rails that we have, giving real-time finality, settlement, reliability and trust.
One-Leg-Out really drives what we’re looking for from an instant payment environment – moving that from the domestic to allowing it to be delivered cross-border Pat Antonacci, The Clearing House MIRIAM SHERIL, FORM3: Domestic instant payments have transformed expectations around speed and availability, yet international transfers still encounter delays caused by banking hours, weekends and intermediaries. OLO promises to eliminate at least some of those obstacles by connecting cross-border flows with real-time infrastructure. Form3 is a global company. We facilitate domestic payments in the UK, Europe, the U.S. and now Canada. So, One-Leg-Out is really going to help bridge all those. There will always be a use for wires and the Swift network, but when it comes to lower-value payments, removing that friction is going to be huge and help drive OLO adoption globally.
TFM: What difference could this make for customers and where will limitations remain? PA: Today, cross-border settlement doesn’t happen in real time. It’s driven either on the wire side, which isn’t 24/7, or through international ACH, which is next day. This drives the ability to settle with finality on a 24/7 basis around the world. MS: The 24/7 aspect is really critical. If anyone has tried to get money across the ocean, you know if you do anything on Thursday, no money is going anywhere until Monday. OLO isn’t a perfect solution that removes all friction. But the small pieces it is removing, like 24/7 availability, are huge. This is still supporting correspondent banking, and it’s one leg of the payment, but a payment is only as slow as its slowest piece, right? As long as we speed up this one, someone else will speed up the next. TFM: Connecting international correspondent banking flows with always-on payment networks presents considerable challenges for banks. What needs to change behind the scenes and is the industry ready? MS: This is about connecting systems that are running 24/7 across the globe. Outdated software, solutions and operations are just not going to cut it. You need teams and technology that are fully running all the time and fully resilient. You need to think about multiple clouds because you can’t start having something go down in one market if you have one leg going into another. From a technology perspective, this has to be cloud computing, multiple clouds and APIs. Some of the terms we’ve always talked about aren’t optional anymore. They’re mandatory. PA: One major component where we’re seeing a process change and a need for fresh technology is screening. Today, because these payments happen on the wire or ACH (automated clearing house) network, they’re screened next day or after the fact. Now you’re going to need to screen them at the same FFNEWS.COM
The clock is ticking: Banks face pressure to make cross-border payments faster, cheaper and more predictable
five-second rate. That real-time approach really changes the paradigm of how you’re operating today. For banks, modernising cross-border payments isn’t simply about speed; it’s also about reducing costs, improving transparency and delivering a better customer experience. Yet introducing new capabilities demands investment alongside existing infrastructure commitments. TFM: How strong is demand for OLO and where could it deliver the greatest commercial value? MS: There isn’t a single conversation I’ve had recently that doesn’t ask me about One-Leg-Out. Is it real? How would you support it? Banks using us in multiple markets especially are asking, ‘how can you make this easier for us?’ and ‘how can we reduce fees?’. Cross-border is painful today. It’s very expensive, which means banks have to charge their end users. For banks, this is about end-user experience and reducing costs. Being able to tell customers that their transactions will move much faster, even though they’re still going via correspondent banking, is really important. PA: Banks have the opportunity to offer this as a service, expanding the same use cases they already have in real-time payments into the cross-border space. But they shouldn’t implement this just because it’s something new. They need to look at the business case for their end customers. FFNEWS.COM
TFM: Stablecoins and tokenised deposits promise faster, more efficient cross-border payments, while OLO builds on established banking infrastructure and compliance frameworks. Are these competing approaches or will banks ultimately need both? PA: Stablecoins and tokenised deposits are definitely going to help support cross-border payments, but there are compliance and regulatory aspects, on- and off-ramps and fees associated with that.
Being able to tell customers that their transactions will move much faster, even though they’re still going via correspondent banking, is really important Miriam Sheril, Form3 One-Leg-Out makes 24/7 settlement possible on the banking rails themselves. I imagine most banks will end up wanting to support both. MS: I think there is a role for both. I think there is also competition. Stablecoin, to me, was solving cross-border. That was probably the main use case where I’ve seen a lot of fintechs offering solutions because it tackles something that isn’t solved for today. Now, One-Leg-Out transactions are also starting to solve that same problem. However, stablecoin solves certain things that One-Leg-Out doesn’t, and One-Leg-Out solves other things from a risk and compliance perspective that stablecoin doesn’t.
So they will both exist, but they also will both compete. And that just helps the whole industry. TFM: Five years from now, instant payment networks, correspondent banking, stablecoins and digital assets could all be competing for transaction volumes. Will greater choice create further fragmentation rather than genuine interoperability? PA: I hope we don’t see that it’s created a huge amount of fragmentation, with lots of closed loops doing their own thing. If, in five years, we’ve met the demand for speed and transparency while maintaining trust and interoperability, then that would be success. MS: I think it’s going to be completely agnostic to the end user [what rail is used]. When I want to send money somewhere, I’m not going to know or care how it’s going. There will be providers doing intelligent routing behind the scenes, looking at the payment, the use case, the necessary speed and budget, and just sending it. Is it going to go instant payment One-Leg-Out? Is it going to go stablecoin? Is it going to go to the wire system because speed isn’t important? I think we’ll end up in a world where that routing happens on the backend, while at the front end, from a user perspective, from a supplier perspective, from a company perspective, they will absolutely not know about it.
Pat Antonacci, Chief Product Officer at The Clearing House
Miriam Sheril, U.S. Head of Product at Form3
ISSUE 40 THEFINTECHMAGAZINE 47
FINTECH
MAG A Z I N E
WHEN AI AGENTS HOLD THE KEYS... AGENTIC AI
A new autonomous entity in the payments chain is reframing everything we thought we knew about trust and accountability
Our recent roundtable discussion on security, control and recovery in the agentic economy couldn’t have been more prescient, given events that unfolded on the Binance platform days later. There’s no evidence to suggest that agentic AI perpetrated the $6.3billion heist – attackers spent a long time grooming an engineer using textbook social engineering techniques. But once the trap was sprung and they were inside the system, they did manipulate an internal AI assistant to gain control of the crypto exchange, using the tool as a ‘springboard’, according to the company’s own report, to compromise Binance’s automated withdrawal and signing infrastructure. Recorded before the largest cryptocurrency hack in history hit the headlines, our roundtable experts from CoinCover, a digital asset security and cryptocurrency recovery company, BasedAI, a decentralised blockchain and commercialisation layer for open-source 48 THEFINTECHMAGAZINE ISSUE 40
AI, and Fireblocks, a digital asset infrastructure and cybersecurity platform, talked to Ali Paterson about how to engineer for the worst while planning for the best.
Anthony Yeung, Chief Commercial Officer at CoinCover
Josh Goodbody, Co-founder and COO of BasedAI
Matthew Foyle, Developer Relations Lead at Fireblocks
THE FINTECH MAGAZINE: When an AI agent holds and moves money for someone, what does that actually look like and how much of it is live today? JOSH GOODBODY: A couple of years ago this felt very speculative, but it’s now really clear in the data that agents are going to be making payments for themselves as well as for their owners. We saw more than 100 million transactions this year over x402 [using web requests to enable instant, zero-protocol-fee stablecoin microtransactions]. The dollar value was relatively low, I think between $15million and $20million. But the predictions are big: one McKinsey study estimated that $3trillion will be moved by agents by 2030. And because agents are starting to move money, it’s opened a Pandora’s box of questions. Who’s responsible when things go wrong? How do you insure these transactions? How do you build guardrails for them? The question for anyone building an agent will be how to keep control of it, how to understand it, and how to future-proof what you’re implementing now.
In control?: In the absence of regulation, we rely on banks for security and trust
ANTHONY YEUNG: I think a lot of people still don’t understand that there are two types of agentic payments: machine-to-machine and agentic commerce. Agentic commerce still uses traditional fiat rails and that’s arguably more structured because there’s a precedent for how Visa, Mastercard et al handle that. But the machine-to-machine world is new. From guardrails to infrastructure, so much is still being figured out, although I think we all believe that it will very quickly become a significant proportion of commerce. MATT FOYLE: There are two main architectural decisions that are becoming important for developers as we introduce a new kind of actor that has some level of authority to move assets. The first is whether you give agents their own identity or whether they inherit some form of existing identity. That has a technological cost because we’ve built all of our identity frameworks for humans. The second decision: is where do you put the authority and accountability. FFNEWS.COM
we’re seeing them figure out which bits of their stack to open to agents. Recently J.P. Morgan said they’re not going to let an autonomous agent without a human owner have access to their payments infrastructure. We’ve also seen Stripe open up its Link infrastructure, with, I think, a 38-fold increase in transactions over that network originating from agents. So these questions of who is responsible are becoming really important. Users who deploy agents on our infrastructure want to buy services from third parties, whether that’s a dataset, API access or anything else, and they want to do it at machine speed. That opens up a Pandora’s box, because they don’t always know who created that service. If someone advertises access to data from any given country, the person offering the service isn’t necessarily the person who created it. So permissionless, autonomous agentic transactions are going to throw up some big issues around responsibility and accountability. I think we’ll see a lot of legal and regulatory questions as transaction sizes increase. There’ll be a grey area for a while.
Is it at the level where an agent generally gets a credential that allows it to access a wallet to perform a certain task (although that credential may also be the key itself). Is that secure enough? Or do you put permissions further downstream? In crypto, there’s a signing stage where we can inject a policy engine.
What worries us most is that vendors see the opportunity in embedded wallets and it’s ‘go, go, go’, forgetting that we need to put guardrails in place Anthony Yeung, CoinCover
You can do both: scope the agent based on its credential, then have a policy engine on the signing layer at the end. When agents attempt to use virtual debit cards, that’s a combination: it issues a credential that can be scoped along with spend limits. But then think about everything a bank does behind the scenes to decide whether to let that payment through, how to recover the funds, how to communicate. I think we’ll all converge on building that same kind of inference layer. FFNEWS.COM
TFM: When the thing pressing send is an agent, what new failure modes appear: prompt injection, hijacked agents or an agent confidently getting it wrong and saying ‘it’s all good’? Which of these worries you most? AY: Regulators, auditors and insurers are all asking providers what happens if everything goes wrong. What happens to all the wallets and all the funds? When it comes to remittance especially, this is genuinely people’s hard-earned salary, not someone buying a token. These are real people trying to send funds to another country, and if that fails, it has catastrophic impacts on people on the ground. Embedded wallets are also now coming up a lot more and what worries us most is that a lot of vendors aren’t thinking sufficiently hard about this. They see the opportunity and it’s ‘go, go, go’, forgetting that we need to put guardrails in place. JG: When an agent can take action for you at machine speed, without the biases or the challenges humans have in gathering all the right information, money will move at a speed we haven’t seen before. So whether it’s banks, payment providers or service providers,
The predictions are big: one McKinsey study estimated that $3trillion will be moved by agents by 2030 Josh Goodbody, BasedAI
TFM: The whole point of the agent is that it’s autonomous, but you also want it aligned to you, with you having overriding control. How do you reconcile that? MF: There are three parts to this. There’s the model’s ability to reason that an action is a good one. Then there’s the human in the loop, deciding whether that action is reasonable to take, bearing in mind risk, responsibility and the framework your organisation works within. And then there’s the action itself: you sign something and it moves on whatever rails it can. I have an open question at the moment about where the real power of agent payments lies. Is it in trusting an agent to move money for you, or to decide that money should move in a certain direction? I think in one way we’re too cautious, and in another we’re not cautious enough. If you ask people whether they’d give their agent a wallet if there was no risk of failed recovery, often the answer is no because they don’t trust the model to reason its way to the correct decision. If you don’t trust that, you’ve already taken away the two parts after it. ISSUE 40 THEFINTECHMAGAZINE 49
FINTECH
MAG A Z I N E
But do you really not trust a wallet or an agent to spend funds? I think we implicitly do today. We buy tokens, we buy credits and inherently accept a level of risk in the way we use the latest models. AY: I came from the payments space, so my view is that Visa and Mastercard could have a big role to play in building trust with agentic commerce. Mastercard has Agent Pay and Visa has the equivalent. As those products evolve, you could get to a world where they act like they do in traditional e-commerce, where 3D Secure gives you a liability shift if something goes wrong. Visa and Mastercard could play the same role they play in e-commerce payments today, mediating [agentic] disputes. I think that helps drive trust, and will probably drive a lot of the use cases and volume. A lot of the people who start using this technology won’t even realise it’s agentic payments, as long as they see the Visa or Mastercard logo stamped on it. TFM: My 11-year-old has an agent that checks merchants’ websites every day for Pokémon cards. I’d never let that agent buy anything, though. That would be a car crash. So, where is the line between useful and dangerous? JG: That’s a great example of agents finding things for you that you’d never be able to find at human speed. When we ask our customers at what point they’re going to give their agent a wallet, though, they broadly fall into two buckets. Users with regulatory obligations typically have the least appetite. Those without are much more inclined to take some measured risk. They see it as freedom of choice: ‘if I want to give an agent a bit of spending money, to buy something that will add value to my business, I’ll let it do that. It won’t affect my customers or any regulatory obligations, because I don’t have any. So I’ll experiment’. One of the service providers we use in our business is Composio, which lets agents connect to thousands of applications on the internet. Of the 3,000 it makes available, more than 1,000 let agents make autonomous payments, which to us is a clear sign of huge demand. TFM: Crypto transactions are final and agents move at machine speed. So when it does go wrong, what does recovery look like and who is on the hook? AY: It’s still quite unclear. We mostly deal with enterprise businesses and when we speak to customers, their view is: whether I’ve issued 5,000 wallets or 100,000 against the 50 THEFINTECHMAGAZINE ISSUE 40
10 million users on my platform, I can’t afford any problems with this product, because it damages trust. So ultimately, it’s businesses who are on the hook, until the right regulations are in place to define who’s liable. On recovery, we’ve been doing this for a long time, helping major financial institutions around the world make sure their institutional wallets are backed up. People understand that if you have a non-custodial wallet, you need to do something to protect those keys. But I don’t think that’s translated into the embedded wallet space yet. People haven’t clocked that it could scale very quickly and those funds could be lost quickly. I think they’re just saying ‘we’ll trust the infrastructure’. And there’s no reason you Crypto transactions: Payments are final
Anthropic recently hired a team of legal and regulatory experts in the U.S. to try to create a framework for machine-to-machine disputes. I think the first few big disputes will teach us a lot about how this looks in the future. MF: When it all goes wrong is the point at which we all run up against reality. There will always be a point of failure, and there’s no band-aid for that. You’re only as good as your weakest point. So logic tells you to work incrementally down until it’s no longer a good payoff. To use an analogy: if you have an API and you want to define how much uptime you’ll guarantee, people normally get to 99.999 per cent, five nines, and say ‘if we had to make sure our API was unavailable for less than five minutes a year, we’d need to replicate our infrastructure on the moon’. So I’m very curious how far we can get without over-engineering, or without suffering so much that it’s not worth it. AY: Regulation takes time and it’s our responsibility as an industry to put the technology in place – keep providing the technology and a platform for businesses to have those controls that they can adjust to their risk appetite. If we make sure we give people those controls and that functionality, the ‘who’s on the hook?’ question gets answered in parallel.
When it all goes wrong is the point at which we all run up against reality Matthew Foyle, Fireblocks
shouldn’t trust a provider like Fireblocks, but what people forget is that single points of failure still exist. You still have to think about the ‘what if’? JG: A lot of people are falling back on the traditional payment rails and how those deal with disputes and contractual obligations. In most jurisdictions, I think, the agent owner would be on the hook for a transaction: they created it, they gave it rules to operate within, they funded it with their money, so ultimately they’re responsible. There will be chained transactions, where an agent has used an intermediary who pays on your behalf, and it will be really interesting to see that play out legally and from a regulatory perspective. At some point there will have to be new rules and regulations for autonomous machine-to-machine transactions and the big players are already thinking about this.
TFM: What has to be true in the next 12 to 18 months before institutions will let agents touch real money at scale? MF: Some kind of governance framework and a combination of platforms, or one platform, that gives you end-to-end observability and accountability, at the very least. Then you can form a mechanism to adapt your organisation to its risk appetite. JG: Institutions won’t allow agents to move money unless there’s clear ownership of who made the decision. If there’s a human on the hook, institutions will let it happen. That’s the litmus test for them, I think. AY: Whether there’s actual regulation in place is one thing, but it all falls back on the bank: they’re the one on the hook, deciding whether to give you your money back because something’s gone wrong. And they can’t make that decision without the insight to help them. FFNEWS.COM
OPEN HOURS INSTANT RAILS
Three years after its launch, the U.S. instant payment rail FedNow® has more than 1,900 institutions on board and a world of use cases it never predicted It’s a sunny Saturday afternoon. You’ve headed to the car dealership in downtown Chicago, found your new ride and shaken hands on the price. There’s just one problem. The bank that would fund your loan so you can drive away today is closed. It shut its doors on Friday evening and won’t be open again until Monday morning. The dealer’s unhappy too, because a sale that can’t be funded on the day is a sale that might not happen. Three years ago, the U.S. Federal Reserve launched the FedNow Service, a real-time, instant payment infrastructure that allows banks and credit unions to 52 THEFINTECHMAGAZINE ISSUE 40
send and receive funds 24 hours a day, seven days a week, 365 days a year. Auto loans weren’t the primary use case that the Fed expected when it designed the service. But with 15 to 20 million new cars and trucks being purchased in the U.S. every year – 80 per cent of which are financed – it’s overtaken demand for the transactions the Fed did anticipate by solving a real issue for many Americans. Three years in, instant payments are growing rapidly, and things are only just getting started.
FEDNOW AT THREE Amy Burr, Executive VP and Chief Product & Relationship Officer at Federal Reserve Financial Services (FRFS), describes FedNow as ‘the fastest-growing instant payments rail in the country’. She’s referring to the number of institutions, rather than transaction volume. The Real Time Payments (RTP) network, operated by The Clearing House, still processes a greater volume of transactions despite having a smaller participating base of around 1,300 financial institutions.
Amy Burr, Executive VP and Chief Product & Relationship Officer at Federal Reserve Financial Services
But, as of today, FedNow has signed up more than 1,900 financial institutions, including seven of the country’s 10 largest banks, giving it reach across more than half of U.S. checking and savings accounts. It’s open to any bank or credit union to participate and that broad access is important for smaller, regional banks, which serve many small and medium-sized businesses underpinning the American economy. “We have the ability to reach more than half of the depository accounts in the US, including both individual consumers and businesses, and we’re adding institutions every day,” Burr says. “We’re unlocking new use cases to help increase the value that FedNow provides. The use cases that we thought would be the dominant ones when we were seeking approval are nowhere near what we anticipated.” Automobile sales were one of those unexpected bonus balls. The gig economy boom has driven another use case. Earned wage access, which allows workers to instantly receive money for work they have completed, was a timely introduction. FFNEWS.COM
treasury controls: businesses have to be more diligent in ensuring payment instructions are accurate before funds leave their accounts.
SECURE AND RESILIENT
Currently estimated to be worth $1.5trillion, the gig economy employs around 76 million people in the U.S. – 12 million more than three years ago – and for workers whose income arrives irregularly, getting paid in real time can make a tangible difference. “The gig economy was just a tiny glimmer in the economy’s eye when we were writing the use case for FedNow,” says Burr. “But it’s so gratifying to know that folks who need to be paid can be paid in real time through the FedNow service enabled by their banks.”
THE $10MILLION CEILING FedNow’s transaction limit was raised from $1million to $10million late last year, opening the door to larger business-to-business payments. Previously, businesses making sizeable transfers would typically have relied on alternatives such as the automated clearing house (ACH) system or wire transfers. FedNow offers a different combination of speed and availability, allowing participating institutions to settle payments instantly, around the clock. The higher transaction ceiling means businesses can not only potentially settle obligations faster but also improve working capital management. There is, of course, a consequence to that. Higher-value, instantaneous transfers demand robust FFNEWS.COM
that. Cross-border payment isn’t just an airline paying Airbus for a plane,” Burr says. “It’s also me sending a remittance to a parent who lives thousands of miles away in another country. Cross-border payments matter for enormous things and tiny things that are enormous to the people who are involved.” FedNow currently handles only domestic transfers, but reach could extend through cross-border transaction support that would instantly process the domestic leg of incoming or outgoing cross-border payments. Subject to regulatory approval, Burr said it has the potential to bring significant benefits to consumers and businesses by enabling round-the-clock domestic processing of international payments. She points out that making one leg of the transaction instant does not make the entire international payment instantaneous. For money to move around the world as readily as it moves domestically, the systems connecting different countries will need to work together more seamlessly. But it’s a big step in that direction.
Instant payments place new demands on financial institutions and their clients. Traditional payments may allow time to spot errors, investigate suspicious instructions or intervene before funds arrive. Instant settlement dramatically reduces that window. “It’s not just about [being] fast. Fast is important, but reliable, accurate, and certain are also essential,” Burr says. FRFS is developing tools to help financial institutions and corporates manage that risk. One is payee name verification, which lets a bank check whether the name on an account matches the intended recipient in the payment instruction. Originally available through FedACH, the tool is being made available through an API to FedNow users, helping institutions assess potential risks before sending a transaction. The aim is to reduce the likelihood of payments being misdirected or sent to the wrong account. The service complements ONE DIRECTION FedNow’s network intelligence API, introduced FedNow is part of a wider push to extend earlier this year, as part of a wider effort to give U.S. payment services. The Federal Reserve participating institutions better information is also considering longer operating hours with which to assess payments. for Fedwire Funds Service, which handles Preventing fraud and misdirection large-value payments. errors is only part of the picture. It currently operates 22 hours Payment infrastructure must a day, five days a week also remain resilient as – longer than almost any It’s so gratifying to threats evolve, particularly comparable central know that folks who as automation and AI bank service. Following need to be paid can be agents create new ways public consultation, the paid in real time through for transactions to be Fed is working towards the FedNow service initiated, potentially at six-day operations in enabled by their banks greater scale and speed. 2028 or 2029. Amy Burr, Federal Reserve “There’s never been Extended hours would Financial Services a point where we’ve been reduce weekend payment done with resiliency, and there’s delays, particularly for international no new threat on the landscape,” Burr says. transactions involving multiple systems. “The form factor may change. The speed at The aim is consistent standards and settlement which those threats are coming may be in central bank money, enabling payments increasing. But, at the end of the day, security around the clock, around the world. and resilience are table stakes in any So, whether you’re a car buyer awaiting environment we operate in.” a Saturday loan, a small business paying workers at the end of their gig, a company THE LONG GAME settling a multimillion-dollar invoice or a family The next frontier for FedNow is international sending much-needed money abroad, the payments, where the demand for speed is FRFS appears to be catching up with our increasingly difficult to reconcile with systems always-on lives – meeting the expectation that still depend on multiple intermediaries that money should move when needed, not and operating schedules. just during banking hours. “We tend to think about big global trade Twenty-four hours a day, 365 days a year, finance when we think about cross-border the U.S. central banking system is becoming payments. But there’s so much more to it than the Fed that never sleeps.
ISSUE 40 THEFINTECHMAGAZINE 53
Acing the PAYMENTS
payments of tomorrow AI and tokenisation in all its forms will transform payments – but you still need to decide the best gameplan for delivery, says BNP Paribas’ Bruno Mellado THE FINTECH MAGAZINE Many say we’re now in a multi-rail reality. From a treasurer’s point of view, are more rails a gift or a headache? BRUNO MELLADO That’s an excellent question! More rails in payments means you have more options. But what’s happening right now is that we’re adding new ways to move liquidity from one part of the world to another, and that adds cost, because you have to build those rails. Where institutions like BNP Paribas have to excel is in integrating this behind our own offering, so clients get a best-in-class payment experience, whether they’re buying securities, selling assets, paying a supplier or collecting payments from their clients.
54 THEFINTECHMAGAZINE ISSUE 40
It’s all about the client use case. Nothing really works on its own unless you look at where the client’s needs are coming from. A set of experts, project managers and product managers are in contact with all the different providers to understand what’s mature, where there’s scale, and where there are interesting benefits for our clients. Then we integrate that behind our overall digital capabilities. That’s going to be even more important as digitalisation goes further. Agentic e-commerce and other trends will require us to provide different solutions, depending on the use case: who’s getting paid, or who’s trying to collect money for their business. In the end, treasurers expect simplicity, that’s for sure. And that’s what we need to deliver in this new world of options. TFM BNP Paribas is involved in Project Agorá, the project run by the Bank for International Settlements (BIS) and the Institute of International Finance (IIF) to explore how tokenisation and programmability can improve wholesale cross-border payments. It successfully completed its first real-value transactions this year using atomic settlement over
Bruno Mellado, Global Head of Payments and Receivables at BNP Paribas
blockchain. What has being part of the project taught you? BM Agorá is a great experience. We have central banks, commercial banks and some network operators around the table, defining how the payments infrastructure will work tomorrow and how liquidity will be transacted, in a way that keeps today’s economic principles in place, even when you move to tokenised assets. This forum has managed to define how the regulatory landscape fits tokenisation, how central banks want to operate, and how commercial banks can stay relevant in a world where funds move 24/7 across the globe, and where some use cases need commercial bank money and others need central bank money. What Project Agorá was trying to achieve with atomic settlement was a situation where you don’t have to think about the payment getting to its destination any more. If the money isn’t in your account, it’s simply because it’s in your beneficiary’s account. That’s the goal. In the live transaction we did with Agorá, we could see that pre-validation is essential for that: all conditions have to be met before the liquidity moves.
FFNEWS.COM
Tomorrow’s world will include tokens of different types, but they’ll serve different use cases. It’s a challenge, but it’s an opportunity to rethink how to bring the right payment method to the right client case. TFM Where is AI genuinely changing payments and receivables today? BM I think we’re at a very early stage of the AI revolution, to be honest – we’re in a kind of honeymoon period. What we need to understand is how payments will be decided by agents. That’s the name of the game. That requires a whole method and infrastructure to make sure we can prevent fraud and protect our customers. In my opinion, a whole industry will evolve around making agents perform well when making decisions on behalf of those who hold the mandate to make a payment. It’s very early and very exciting. But we’ll need to ramp up a lot of our technology so this can be a safe and convenient payment experience for anyone wanting to buy or sell anything in the future.
Processes in banks and institutions have to become 24/7, too, to truly deliver a perfect atomic settlement experience. That’s the road ahead for most of our institutions in the coming years: making sure everything works around the clock. TFM How do you see banks dealing with tokenised assets and stablecoins side by side? BM I’m quite convinced that tomorrow’s financial system will include tokenised assets and cash. Some of these will be liabilities of banks, as today, and some will be liabilities of stablecoin issuers. So, in the end, you’ll have to compare the counterparty risk, the cost of liquidity and the performance of the payment, all within the safety requirements that are so important for most banking institutions.
Nothing really works on its own unless you look at where the client’s needs are coming from Bruno Mellado, BNP Paribas
FFNEWS.COM
TFM Do you sense a collective will to achieve this? BM We see AI everywhere, as well as tokenisation. Those two topics are taking up a lot of space. What’s interesting is that these trends are happening across the board, from securities to payments, corporate payments to bank payments. I can certainly confirm that, with the amount of transformation ahead of us, the attitude and willingness of many of the institutions and technology providers is about how we can advance together in tomorrow’s tech-driven payments environment. The commitment is there to make the right choices and work in the right direction. You don’t choose where you’re going to play tennis on your own, you go where your friends are playing tennis. It’s the same in payments. We can only pay where we find counterparties available. And here we’re setting the expectations of where we’ll meet tomorrow to deliver the best payment experience to customers.
ISSUE 40 THEFINTECHMAGAZINE 55
MENA & APAC
From follower to leader: Saudi Arabia’s payments market grows up The Kingdom has transformed its infrastructure, its regulatory approach and consumer payment habits, taking just a few years to achieve what other countries spent generations building. So what next for this precocious payments child?
When Jeff Parker first started doing business in the Gulf Cooperation Council countries, cash, physical debit cards and frequent trips to a bank branch were the norm. That was less than 10 years ago. “The region was very much watching what was happening in the rest of the world and seeing how it could bring some of that innovation there,” says the CEO of Paymentology, the UK-born card issuing and processing platform. “It was somewhat playing catch-up with the US and Europe.” Today, the GCC’s payments industry is among the most advanced in the world. “It feels like the region, and Saudi Arabia specifically, has gone from being a follower to a leader,” says Parker. Saudi Arabia’s payments market is certainly moving at an impressive pace. According to the Saudi Central Bank (SAMA), electronic payments accounted for 85 per cent of retail transactions in 2025, up from 79 per cent a year earlier and 70 per cent in 2023. The government has also designated 2026 the Year of Artificial Intelligence. 56 THEFINTECHMAGAZINE ISSUE 40
Saudi Arabia hasn’t invented most of the payment technologies it uses, but it has adopted them faster than most. And now it’s finessing them, says Ahmed Gaber, Co-founder and CEO of CoorB, a payments and digital banking infrastructure company operating in Saudi Arabia, the UAE and Egypt, with Saudi National Bank among its clients. “The technology has been here for a long time. We are improving what’s available for the market, and we’re refining it,” he says. “Saudi Arabia was in transformation mode. Now it has moved from transformation to refinement and maturity.” Both Gaber and Parker are helping build the Kingdom’s payments infrastructure, and they
believe the next phase of its payments story will be shaped less by customer-facing apps than by the systems behind them. Gaber, a former Visa regional director, agrees with Parker’s assessment of the region’s progress and says AI has accelerated the pace. “Literally, I leave Dubai for a week and I come back and I see new product launches, new companies started, new technologies kicking off,” he says. And less and less of that is reliant on imported technology. “There are many Saudi, UAE, Gulf Cooperation Council and Egyptian companies who are able to develop technologies that were not available in the Middle East before,” says Gaber. “That will make a big difference for this region in the future.” “When I first started doing business here, it was actually quite unusual to find Western businesses operating in Saudi,” agrees Parker, whose company has offices in Riyadh. “I feel now it’s a lot more open, a lot more competitive.” Much of the credit for that, in his view, goes to the regulator. FFNEWS.COM
“On the payment side, the Saudi means there’s a huge opportunity in Over the past six to 12 months, Central Bank (SAMA) is much more open helping legacy players adopt the Paymentology has navigated regulatory now to driving and supporting growth, practices that allow them to compete change while migrating its regional as opposed to being [just about] over the next few years. infrastructure from Oracle to Google governance and control,” he says. “It Gaber, meanwhile, predicts Cloud Platform. Despite this, at the still has that role, but it’s more about a ‘massive upgrade and change and time of the interview, it had just gone innovation – how we can use payments consolidation’ of the Saudi payments live with a regional bank and its first technology to grow the economy.” market, noting the mounting pressure transactions were expected that week. In fact, Money20/20 Middle East, on the national payments system, “Mastercard said it was the fastest the region’s biggest fintech show, is which all sits around the local payment ever implementation in the GCC,” says co-organised by Fintech Saudi, an switch, mada. Parker. “It was just under six months, initiative that was launched by SAMA “What was built in the last five to 10 full end-to-end.” and the Kingdom’s Capital Market years, in my opinion, won’t be enough The constraint to growth, he adds, Authority. On its watch, the number to carry the load for the next 10 to 15,” is rarely the technology. “The challenge of fintech firms operating in Saudi he says. “I believe that the next two is how do you orchestrate all of those Arabia has grown 30 times in seven years will reform the Saudi payment together,” meaning the client, the card years, according to an analysis by landscape again and again. Saudi is scheme and every partner in between. J.P. Morgan, and the local industry ready for this change. And the bar just keeps rising. has received $65billion in foreign “The cost of money transfer will “It’s almost impossible to meet the direct investment. go down. The cost of the transaction expectations. And even if you meet SAMA’s regulatory guardrails, might go down as well.” the expectations, then it will become however, are not considered quite so Paymentology intends to leverage business as usual, and then you are progressive. There is no single its global scale to keep up with required to beef up your offering,” statute governing AI that evolution. It raised says Parker. in financial services. $175million in May and, Both he and Gaber believe that Saudi Instead, regulated by Parker’s count, has constant reinvention has favoured Arabia was in transformation firms must navigate around 400 clients in smaller players. mode. It has moved its Cyber Security some 70 countries. Gaber contrasts the present with from transformation Framework, “One of our secret ‘the old days where we had to sign to refinement the National sauces is the fact that with a multi-billion-dollar company or and maturity” Cybersecurity we’re global,” he says. software provider’. Now, he says, ‘some Ahmed Gaber, Authority’s Essential “But fundamentally, startups are having a big piece of the CoorB Cybersecurity Controls the only reason you can cake because of their agility, and they and the Personal Data be successful anywhere is if are trusted because they are thinking Protection Law, alongside outsourcing you actually understand the the same way you are thinking’. and cloud services rules, including local market.” To succeed on Saudi’s approval requirements for hosting That starts with people: terms, they have outside the Kingdom. “They have to understand also invested in It feels like the region, Saudi Key stakeholders argue that the rapid the regulation, they offices and people Arabia specifically, adoption of AI across Saudi Arabia’s have to be in the right in the market. has gone from financial system has exposed significant time zones, they Paymentology being a follower to regulatory gaps. have to speak the client, Tabby, is a leader” right language.” a good example of Jeff Parker, More than technology Then comes the that. Tabby began as Paymentology That hasn’t held back providers from technology. “There’s lots of a BNPL player, splitting refining payments services. regulation around how you host purchases into four “It’s all about digital experiences the data, where you process the interest-free payments. and differentiation,” says Parker. transactions. You have to integrate into It has since added a card, longer “How do we use the technologies and mada, obviously, as a local payment instalment plans and Tabby Cash, data to really deliver real-time, instant, switch. But if we didn’t do any one of a spending account, launched in the personalised experiences?” those things, then we wouldn’t be able UAE this summer. Saudi Arabia, Those experiences, he argues, are to win business here.” however, is now Tabby’s main market. often credited to the wrong layer. “We’re AI, he adds, has helped in building On the opening day of Money20/20 probably biased because we’re from the technology – although coding was in October, Tabby confirmed a Series F the infrastructure side,” says Parker, but never the hard part. funding round, valuing it at $6.5billion. more nimble models of business are now “The moat, the real complexity, is Zarik Nabi, Tabby’s Chief Commercial ‘seeing how much better, how much how do you wrap around the services Officer, traces the company’s origins faster they can ship products. And that’s and the people and the knowledge to a post-Covid market still heavily all driven from the back end’, which – that takes years to build up.” reliant on cash on delivery (COD). FFNEWS.COM
Jeff Parker, Chief Executive Officer at Paymentology
Ahmed Gaber, Co-founder and Chief Executive Officer of CoorB
Zarik Nabi, Chief Commercial Officer at Tabby
ISSUE 40 THEFINTECHMAGAZINE 57
FINTECH
MAG A Z I N E
“Tabby was initially started with a very simple premise: can we replace COD and settle to the retailer?” he says. Today, customers expect speed, transparency and efficiency as standard. “Fintech has helped educate the customer. That’s not something special; it should be the norm,” adds Nabi. Keeping up with customers like Tabby, Parker argues, takes discipline at the platform level. “Even if a customer wants something different, we will build it, but we’ll make it available for everyone. And we start with configuration as the baseline,” he says. “But I think as soon as you go away from that, you’re on the first step to legacy.”
The agentic question Parker and Gaber diverge somewhat on AI’s role in all of this. Parker sees it as the biggest force ahead, with agentic AI taking embedded finance to the next level. “I think agentic is really what transforms embedded finance,” he says. “If the agent can operate on your behalf, can actually execute the payment and understand your intent, I think the opportunities for embedded finance are extremely interesting.” He expects banks to retain ‘a crucial role in the overall proposition, but almost sitting behind some of the brands that maybe will come to the forefront’. Gaber is more cautious. Banks, he points out, are wary of AI for good reason. Some are exploring neuro-symbolic approaches, which combine neural networks with symbolic reasoning and which he understands to be
will be the final beneficiary. As for those that less prone to hallucination and manipulation cannot keep up, Gaber takes the metaphor to than agentic models. His bigger concern, its logical conclusion: “I think also some fintechs though, is the one that runs through the rest might not be eligible for dating anymore.” of their conversation: the infrastructure. Parker’s hopes for the coming years extend “Many banks are rushing into developing beyond the technology. AI solutions,” he says. “But while they are “I’m hopeful there’s going to be a lot more doing that, they are also changing the cooperation between [countries in] the region architecture and the infrastructure, which is and systems are going to become a lot more very difficult to change again in the future, interoperable,” he says. especially if you do it in a rush. In fact, during Money20/20 in September, “You don’t need to be number one, you don’t the central banks of Qatar and Saudi Arabia need to be the best now. Just watch carefully announced the start of acceptance of mada before investing too much, because now the cards in Qatar and Qatar’s Himyan cards race, as I see it, is a little bit unhealthy.” in the Kingdom. It is a striking note of restraint in the Year Parker acknowledges that geopolitics of AI, particularly from someone who may intervene when it comes to otherwise sees Saudi Arabia as a his ambition for the region: leader. But regulators are still We look for “But I would like to think in feeling their way, too. partners who are five years’ time there would AI governance here rests better than or at least be genuine connectivity on a patchwork of principles, as good as us. between the GCC.” advisory frameworks and Paymentology is Ten years ago, when draft policies. The National the name that stood out ” Crown Prince Mohammed bin Cybersecurity Authority Zarik Nabi, Salman launched Vision 2030 consulted only this summer on Tabby for the Kingdom, aimed at guidelines covering generative diversifying its economy and and agentic AI. transforming the infrastructure on which it Gaber also sees the relationship between runs, no one could have predicted the pace of banks and fintechs entering a new phase, change in payments. So, it’s understandable which may determine new frameworks. why Gaber is wary of making predictions. “The relationship now between fintechs “It’s very tough to guess what will happen and banks, I believe, has reached the marriage even after five months, let alone five years. stage. It’s not dating anymore,” he says. I have no clue how it will look,” he says. “There are fintechs who are really running When it comes to the surprising Kingdom very important pieces in the banks.” of Saudi Arabia, it really is a case of ‘watch If those fintechs can keep pace with the this space’. banks’ ambitions, the end customer, he says,
TABBY AND PAYMENTOLOGY
FROM SPLIT-IN-FOUR TO SHARE OF WALLET Tabby started life in 2019 as a simple BNPL proposition in the UAE. It expanded to Saudi Arabia a year later and, in September 2026, a Series F round valued the startup at $6.5billion. The ambition, says Chief Commercial Officer Zarik Nabi, is to deepen the relationship with the customer and grab more share of wallet. That has translated into a card, longer instalment plans and Tabby Cash, a debit and prepaid product now live in the UAE, which is designed for a big section of the customer base that doesn’t meet credit requirements. Paymentology is the processor behind Tabby’s card programme. 58 THEFINTECHMAGAZINE ISSUE 40
“When we look for partners who can power our next generation of products, we always look for those that are either better than us or at least as good as us,” Nabi says. “Paymentology is the name that stood out.” Nabi judges partners by the same standards customers apply to Tabby: speed, reliability and transparency, from ‘the smallest piece of technology documentation to pricing to the way we deliver the service’. “We don’t expect it to never go wrong,” he also says. “We just expect when it does happen, we work together as partners to fix it.” For Paymentology CEO Jeff Parker, reliability comes first. “If our clients do well, we do well,” he says. “So for me, the
number one priority is it has to work. It has to work all the time and it has to work very quickly and efficiently.”
FFNEWS.COM
FINTECH
MAG A Z I N E
AGENTIC COMMERCE
Building trust in the agentic age As AI moves from answering questions to executing transactions, the banking industry faces a fundamental shift, says Temenos Kaue Tozzi, Global Head of Product Strategy & Partnerships at Temenos
It’s helped institutions navigate the rise of digital banking, cloud computing and real-time payments – and watched them cede market share to challengers as the financial services space diversified. But with the emergence of agentic AI, there’s a real opportunity for banks to recapture value across the payments ecosystem, according to Kaue Tozzi, Global Head of Product Strategy & Partnerships at banking tech giant Temenos. “We’re going to see an explosion in volume as these [agentic] payments become more frequent, more common and smaller,” Tozzi predicts. “It’s going to shuffle the playing field for a lot of financial institutions around the world.” To be prepared for that, he says, banks need an investment strategy that doesn’t weigh them down with expensive proprietary tech. Rather, they should focus on what they know best: trust and execution.
Small steps, big implications Early adoption of agentic commerce, Tozzi believes, will concentrate on predictable, low-value transactions where the consequences of an incorrect decision are limited: “It’s going to be the small, predictable, low-risk use cases first. Things like your daily coffee or ordering me my takeout for dinner.” But as confidence grows, agents will increasingly manage complex purchases and execute higher-value transactions. When consumers delegate responsibility to intelligent systems at this level of autonomy, prescribed operating boundaries, liability and FFNEWS.COM
security will become critical. Because, while Temenos’ AI solutions provide reasoning customers might welcome relief from the logs and supporting information, including tyranny of consumer choice, preferring to SQL (structured query language) queries where delegate information gathering and financial relevant, enabling institutions to understand execution to a machine, that convenience how information was retrieved and decisions must be balanced with control. Customers generated. The objective is to make AI-powered must retain ultimate authority and remain banking efficient, safe and auditable. protected, say Tozzi. And Temenos argues that “It’s critical that every institution delivering the underlying purpose of banks therefore any AI tooling for its end customers is also remains consistent, even as the payments building that trust and delivering a product experience changes dramatically. that feels fair,” adds Tozzi. “Throughout their entire history, banks always played one role, which is the role of A race for relevance trust in the ecosystem,” Tozzi says. Agentic commerce is already technically “When there were physical goods, they feasible. Right now, autonomous transactions built vaults. When we moved into mobile and can take place using existing infrastructure, digital banking, they invested in cybersecurity. sometimes without the customer’s bank And now, in the age of AI, they’re going to recognising an agent’s involvement. That’s invest in AI agent infrastructure that’s going why it’s so important that banks seize the to keep their customers safe.” moment, says Tozzi. While Temenos identifies three components Integrating contextual intelligence, real-time of effective AI agents – logic, context and execution and trusted customer experiences tooling – Tozzi believes banks should leave the could significantly strengthen their competitive development of reasoning capabilities to others. positions. The alternative is to risk losing “What banks need to invest in is the other two customer relationships and commercial items on the list: context and tooling,” he says. opportunities, as they have in the past. Context enables agents to make decisions “Agentic commerce is going to take off, grounded in customer and institutional data. whether these financial institutions are That requires sophisticated data ready for it or not,” Tozzi says. Agentic housing and retrieval-augmented But if they adapt, the outcome generation technologies. Equally AI is going will be in their favour. important is translating “When we saw instant payments to shuffle intelligence into action. An agent come on the scene, everybody the playing unable to initiate an immediate was worried. Is it going to field for a lot cannibalise ACH (automated transaction is of limited practical of financial clearing house) volume? Is it going use to customers. “You want that payment to institutions to cannibalise wire volume? settle instantly. You want that “The reality is, payment volume around the information to be retrieved skyrocketed across the board world immediately. So banks have to because consumer behaviour invest in API event-driven architecture,” fundamentally shifted,” adds Tozzi. Tozzi explains. For Temenos, that means equipping financial This reinforces the importance of the institutions with the flexible, intelligent flexible banking infrastructure that Temenos infrastructure to remain relevant. builds for its clients, connecting intelligence The technology is emerging. Consumer with operational execution, while putting behaviour is evolving. And the race to define accountability, explainability and regulatory the future of agentic banking is already oversight at the core. well under way. ISSUE 40 THEFINTECHMAGAZINE 61
TRADTOK:
TOKENISATION
WHY BANKS MUST LEARN TO BANK BOTH WAYS The new norm isn’t a choice, but a symmetry of transaction methods Mick Fennell, Business Line Director of Payments at Temenos
“The future of banking is tokenised – or, at least, a significant proportion of the future of banking is tokenised.” Mick Fennell, Business Line Director of Payments at Temenos, corrects himself. He won’t put all his digital eggs in one data basket just yet, because, despite the noise around stablecoins, central bank digital currencies (CBDCs) and tokenised deposits, old and new systems will likely coexist, with customers expecting their bank to handle both traditional and next-generation currency simultaneously and seamlessly, for some time. “It’s what I like to call TradTok banking, which is traditional and tokenised together. A bit like TikTok, but more important,” he says. “Customers will look for organisations who can bring together both traditional and tokenised finance, traditional and tokenised banking products,” he says. “It’s a new way of managing the products we already provide.” Smart contracts and distributed ledgers simply let banks tokenise what they already trade ‘and put them in a more real-time, more transparent environment’, says Fennell, who traces the transition through three stages. Tokenisation 1.0 ran from roughly 2010 to 2017, and revolved around blockchain and Bitcoin. Tokenisation 2.0 introduced wallet providers, exchanges and the regulation that put guardrails around them. “Now we’re in Tokenisation 3.0. Those guardrails are in place, and we’re starting to 62 THEFINTECHMAGAZINE ISSUE 40
see traditional banks asking, ‘where can I play here?’,” says Fennell. Eventually, the answer will be ‘almost everywhere’, he predicts. Payments will come first, but tokenised trade finance, letters of credit, guarantees and lending will follow. “Whatever we have within banking will be available to be tokenised, put on a blockchain, and used in a more real-time, transparent way,” Fennell says. There is more than one type of tokenised asset, of course. Fennell identifies four so far: public money in the form of CBDCs, private money in the form of stablecoins, bank money in the form of tokenised deposits, and crypto, which Fennell describes as having ‘no real fixed abode, no collateral behind it’.
IT’S TRADITIONAL AND TOKENISED TOGETHER. A BIT LIKE TIKTOK, BUT MORE IMPORTANT “Which are banks going to bet on? Which are they going to allow their customers to bet on?” he asks. “That’s one of the key roles the bank will play for their customers – to be the gatekeeper for which digital currencies and processes they support.” Thus far, it’s tokenised deposits that are leading the field. They are ‘really starting to move the needle’, says Fennell. That’s understandable, as key jurisdictions allow them to be held on a bank’s balance sheet and used within current regulatory frameworks, albeit restricted by where counterparty banks reside. Fennell sees a ‘trickle-down effect’ as global Tier 1 institutions’ use of tokenised deposits is copied by other tiers. The plumbing, however, is still catching up.
“Right now, there is very little infrastructure in the world for us to process tokenised deposits,” Fennell says. New networks are appearing, from Cari and Keystone in the US to Great British Tokenised Deposits in the UK and Swift’s new ledger, where a proof of concept has centred on tokenised deposits. But there are a number of stepping stones and building blocks that are still evolving.” What’s clear to him is that the end state will not be a single currency or chain. “The future is multi-currency, multi-rail, multi-chain,” says Fennell. A payment instruction might arrive in fiat and settle in a tokenised deposit, or even a stablecoin or a CBDC, and that switch needs to be seamless, real-time and wrapped in the same protections customers get with fiat today. For the customer, it all lands in a digital wallet that Fennell likens to ‘a digital bucket’, holding fiat, tokenised deposits, stablecoins, CBDCs and identity information. The bank will remain the gateway to all of it, and that is where Temenos comes in. “Our job is to build out the interoperable platforms and services that enable the banks to launch those into the market,” says Fennell. That means API-first, cloud-native, event-driven platforms, built for volumes heading only one way: up by around 10 per cent a year globally and more than 15 per cent in some markets. Over the next three to five years, Fennell expects tokenisation to ‘start to become relatively normalised’. And that promises to map neatly onto the G20’s goals for payments: lower cost, wider access, greater speed and more transparency. “The nirvana, the goal, is that,” says Fennell. “Our job now is to deliver on it.” FFNEWS.COM
Where Money’s At
The euro account with a 4% p.a. reward
p.a. loyalty reward on your
Сashback on card
24/7 SEPA Instant transfers —
Monthly
balance, paid
purchases*
euros arrive in seconds
subscription fee**
monthly in euros*
A euro IBAN account, a credit-grade payment card and as many wallets as you need — in one app Euro IBAN account Credit-grade payment card SEPA Instan³ transfers
Multiple wallets Apple Pay, Google pay Rewards & cashback
Get started at blackcat.app Authorised and regulated by the Malta Financial Services Authority
* The bonus payment is a part of the loyalty program provided by Baltic Technology Solutions OÜ. Detailed terms and conditions can be found at baltictechsolutions.com/loyalty-program-terms-and-conditions. Cashback applies to card purchases only. ** Standard service and transaction fees may apply. See the tarif schedule on blackcat.app. ;blackcat is issued by Papaya, Ltd. Papaya, Ltd. is licensed by the Malta Financial Services Authority as an Electronic Money Institution (EMI). Registration number C55146. Client funds are safeguarded in accordance with applicable legislation. Funds held in e-money accounts are not covered by the Depositor Compensation Scheme.