BBJ Editor-in-chief: Robin Marshall • Editor: Bence Gaál • Sales: Erika Törsök • Contributors: Annamária Bálint, Mihály Kovács • Lists: BBJ Research (research@bbj.hu) • News and press releases: Should be submitted in English to news@bbj.hu • Layout: Zsolt Pataki • Cover image: apghedia / Shutterstock.com • Publisher: Tamás Botka, Business Publishing Services Kft. • Address: Madách Trade Center, 1075 Budapest, Madách Imre út 13-14. • Telephone: +36 (1) 398-0344 • Advertising: AMS Services Kft. • CEO: Balázs Román • Sales: sales@bbj.hu • Circulation and subscriptions: circulation@bbj.hu • www.budapestbusinessjournal.com • ISSN 3141-7833 • © 2026 Business
HUNGARY’S ECONOMY ENTERS A NEW PHASE AS MARKETS AWAIT DELIVERY FROM GOVERNMENT
Hungary entered the second half of 2026 with stronger economic growth, rapidly easing inflation and markedly improved financial market sentiment. The political change triggered by the April election has raised expectations of closer EU ties, renewed access to frozen funds and a credible path toward euro adoption. Yet, with the budget deficit elevated and the recovery still heavily dependent on consumption, the new government now faces the harder task of turning political optimism into sustainable growth.
Hungary’s economic outlook has changed substantially since the start of 2026. Gross domestic product expanded by 1.7% yearon-year in the first quarter, accelerating from 0.8% in the final three months of 2025 and exceeding expectations. On a seasonally and calendar-adjusted basis, output rose 0.8% from the previous quarter, compared with growth of only 0.2% in Q4.
The improvement is particularly notable following two years of nearstagnation. Full-year GDP growth amounted to only around 0.4-0.5% in both 2024 and 2025, with economic activity constrained by weak investment, soft European demand and a prolonged industrial downturn.
The first-quarter data suggest that Hungary is gradually emerging from this period of weakness, although the composition of the recovery remains uneven. Domestic demand, rather than exports, has been the principal driver.
Services contributed 1.4 percentage points to first-quarter GDP growth, led by professional, scientific, technical and administrative activities. Industry added a further 0.2 percentage points as manufacturing began to stabilize. Construction remained a drag, with value added down 4.3% year-onyear, while agriculture made only a marginal positive contribution.
Household consumption has emerged as the clearest engine of growth. Actual final consumption
by households rose 4.9% year-onyear in Q1, while household final consumption expenditure increased by 5.5%. Government consumption was also up 5.4%.
By contrast, net exports subtracted an estimated 4.5 percentage points from growth. Export volumes declined by 1.8%, while imports increased by 4.1%, reflecting both the recovery in import-intensive domestic demand and continued weakness in important European export markets.
POLITICAL RESET CHANGES MARKET NARRATIVE
The economic improvement has coincided with a fundamental change in Hungary’s political landscape.
The April 12 parliamentary election produced a landslide victory for the opposition Tisza Party, led by Péter Magyar. The party secured more than two-thirds of parliamentary seats and ended 16 years of uninterrupted Fidesz government. Voter participation reached its highest level since the early 1990s.
The new administration took office promising closer alignment with the European Union, institutional reforms and a credible path toward membership in the euro area.
Its most immediate economic priority has been the release of EU funds frozen over rule-of-law
RATINGS AGENCIES
GIVE HUNGARY TIME, BUT FISCAL TEST LOOMS
Hungary’s post-election market rally and the new government’s pro-EU stance have given the country something of a grace period with investors and credit rating agencies, but the room for maneuver remains limited by weak growth, wide budget deficits and rising public debt.
Since the Tisza Party’s landslide election victory in April, the three major rating agencies have all kept Hungary’s investment-grade sovereign ratings in place. Fitch Ratings affirmed Hungary at “BBB” with a negative outlook, Moody’s Ratings completed a periodic review of the country’s Baa2 rating, and S&P
CEO BOARDROOM PANEL
WEIGHS HUNGARY’S FISCAL, EU FUNDS AND EURO OUTLOOK
The fifth anniversary edition of the BBJ ’s CEO Boardroom Meeting brought together senior figures from Budapest’s business and diplomatic communities for a discussion of Hungary’s post-election economic environment. Panelists Károly Radnai of Andersen in Hungary and László Radványi of PwC Hungary discussed investor sentiment, the budget, EU funds, euro adoption, competitiveness and labor market challenges.
Around 40 high-level guests from Budapest’s business and diplomatic circles began their day on Tuesday, June 2, at the CEO Boardroom Meeting, a networking and content event organized by the Budapest Business Journal. Hosted by Matild Palace, a Luxury Collection Hotel, Budapest, with Spago Budapest by Wolfgang Puck providing a specially tailored gastronomic breakfast experience, the event also marked the fifth anniversary of the series.
The milestone was celebrated with prosecco and reflected the cooperation developed over the years between the BBJ, Matild Palace and Spago Budapest. When the first CEO Boardroom Meeting was held in June 2021, it was the first business event hosted at Matild Palace, before the hotel had officially opened. Since then, the format has combined networking with a roundtable discussion of current economic topics.
This edition’s panelists were Károly Radnai, managing partner of Andersen in Hungary, and László Radványi, country managing partner of PwC Hungary. The discussion was moderated by Robin Marshall, editor-in-chief of the Budapest Business Journal , and covered the mood around the
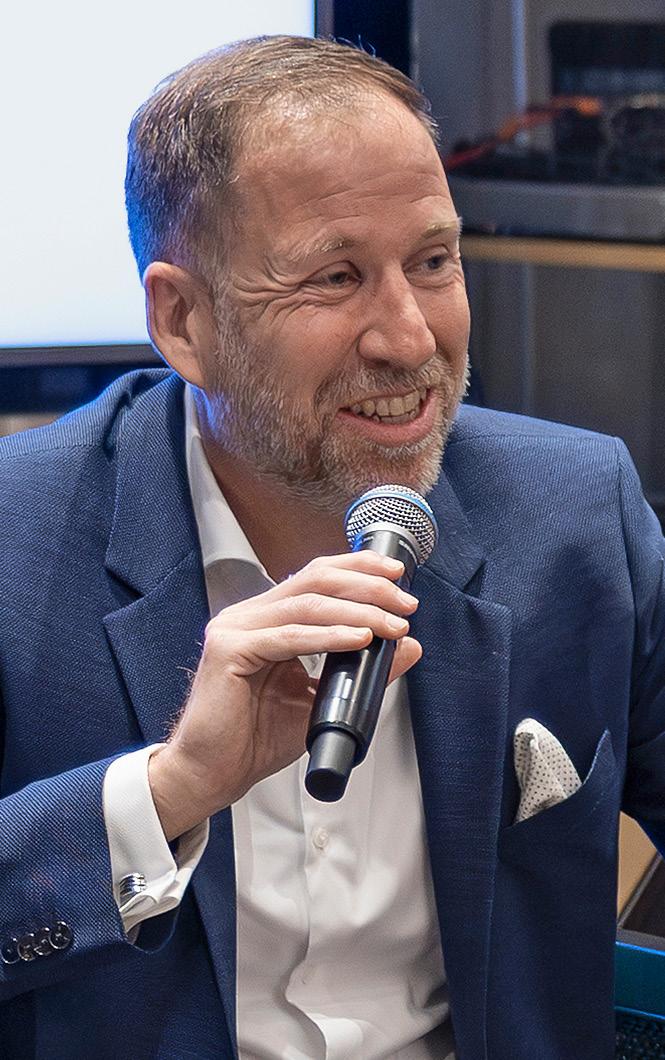
new government, the state of the budget, taxation, EU funds, euro adoption, competitiveness and labor market policy.
BUSINESS MOOD IMPROVES AFTER ELECTION
The discussion opened with the change in sentiment following the April election. Radványi said he was optimistic about what he had seen so far, not only in
domestic political communication but also in business conversations involving PwC’s international network, investors and advisers.
“Yes, I feel really optimistic about what I experience happening,” Radványi said. He referred to discussions with PwC network firms, international investors, private equity groups and independent economic analysts advising the firm’s global partnership. He said there was “a lot of positive vibes” and “a lot of interest coming in.”
He added that the important question is whether the current momentum can be sustained.
“The big question for me is if we’re going to be able to sustain the momentum, if this is going to be more tangible, executable, and not just a good political vibe,” he said.
Radnai also described a clear change in international reactions after the election. He said he received numerous congratulations from colleagues around the world on election day. He said the reaction reflected “an unprecedented emotion” in business circles and a sense of relief.
László Radványi, PwC Hungary
COMPANIES SEE IMPROVED OUTLOOK BUT WARN HUNGARY MUST PROTECT COMPETITIVENESS
Business sentiment in Hungary improved markedly following the April 12 parliamentary election, according to the latest economic survey by the German-Hungarian Chamber of Industry and Commerce (DUIHK). Companies are more optimistic about their own prospects, investment plans and the wider economy, but remain concerned over energy prices, labor costs and Hungary’s ability to compete for capital and skilled workers.
Hungarian companies have become significantly more optimistic about the economic outlook, although the improvement in sentiment comes with equally significant expectations regarding competitiveness, labor policy and the wider business environment. The latest economic survey by the German-Hungarian Chamber of Industry and Commerce (DUIHK) found a clear improvement
in corporate expectations following the April 12 parliamentary election. However, the results also underline that improved sentiment alone will not resolve the structural challenges facing businesses operating in Hungary.
The chamber conducted its regular annual survey among member companies and other foreign-owned businesses in March and April.
As data collection for the broader international survey coordinated by the Association of German Chambers of Industry and Commerce had to close 10 days before the Hungarian election, DUIHK carried out an additional rapid survey immediately after the vote. The resulting beforeand-after comparison revealed a sharp shift in sentiment.
Before the election, 24% of surveyed companies expected their business situation to improve during 2026, while 27% anticipated deterioration. Following the vote, 35% expected better business results and only 19% foresaw worsening conditions. Similar improvements were recorded in companies’ assessments of the wider Hungarian economy and in their investment intentions.
Dirk Wölfer, author of the report, said the clear election result had visibly improved business expectations. However, he cautioned that the stronger indicators had largely brought Hungary back toward the regional average rather than placing the country
INVESTOR CONFIDENCE RETURNS, BUT HUNGARY FACES A TOUGHER COMPETITIVENESS TEST
Hungary continues to offer international investors a strategic location, an established industrial base and deep integration into European value chains, but the factors determining investment decisions are changing. Predictability, skilled labor, energy costs, innovation and regulatory stability are increasingly shaping how companies assess the country, while chambers of commerce see renewed opportunities to strengthen dialogue between business and policymakers.
In this Market Talk, we asked leaders of four international business chambers about investor sentiment, the sectors offering the greatest opportunities, the factors driving investment decisions and the steps needed to improve Hungary’s longterm competitiveness. Participants include Barbara Zollmann, managing director of the German-Hungarian Chamber of Industry and Commerce (DUIHK); Ákos Janza, president of the American Chamber of Commerce in Hungary (AmCham); Gáspár Balázs,
Image by Maha26
THE NEW LANDSCAPE OF INVESTMENT IN HUNGARY: A BUMPY ROAD TO A RESHAPED MARKET
Hungary’s investment landscape has changed dramatically over the past three decades, shaped by shifting sources of foreign capital, state intervention, energy transition and the growing weight of regulation. In this article, Viktória Szilágyi, partner and co-head of energy, and Szabolcs Mestyán, partner and head of banking & finance, capital markets and aviation at Lakatos, Köves and Partners Law Firm, examine how the market has been reshaped and what legal and financial reforms could help Hungary remain attractive to long-term investors.
AI COULD HELP HUNGARY BREAK THROUGH ITS PRODUCTIVITY CEILING
Artificial intelligence could generate at least EUR 15 bln in automation-driven value creation for Hungary by 2030, equivalent to around 6-7% of GDP, according to analysis by the McKinsey Global Institute. The opportunity is significant, but the report and a subsequent business panel made clear that the impact will depend less on the technology itself than on how companies, workers and the state integrate it into everyday operations.
Hungary’s economy has reached an inflection point. After more than a decade of growth supported largely by rising employment and wage increases, the country can no longer rely primarily on adding more workers or extending working hours to sustain its development. The next phase of growth will have to come from a more difficult source: a lasting improvement in productivity.
Image
HUNGARY’S BANKING SECTOR LOOKS TO GROWTH, DIGITALIZATION AND GREEN FINANCE
Hungary’s banking sector enters the next phase of the economic cycle from a position of strong liquidity and capital, but lenders are still navigating a complex environment shaped by macroeconomic uncertainty, changing regulation, digital competition, sustainability expectations and shifting client demand.
In this Market Talk, we asked senior banking executives about the current operating environment, corporate and retail lending trends, digital transformation, key risks and the role of banks in supporting Hungary’s green transition. Participants include Zsolt
Fáy, founder and chairman of MagNet Bank; Balázs Toldi, head of corporates division at UniCredit Bank; Zsolt Barna, chairman and CEO of MBH Bank; Péter Csányi, CEO of OTP Bank; Peter Roebben, CEO of K&H Bank; and Krisztina Bogdán, country manager of ING Bank Hungary.
How would you assess the current operating environment for banks in Hungary, and how has market sentiment changed over the past year? Krisztina Bogdán: In one word: hopeful. The operating environment for banks in Hungary has definitely become more constructive with the elections, although uncertainty remains. The banking sector is generally wellcapitalized, liquid and resilient, so the main constraints today are less about banks’ own balance sheets and more about the macroeconomic environment, regulation and client-side demand. Banks expect that dialogue between the government and the banking sector can be rebuilt on a more predictable basis, which would support confidence.
At the same time, geopolitical risks, slower European growth and volatile industrial demand continue to influence decision-making. Overall, banks are ready to finance viable opportunities, but activity remains selective and closely linked to the quality of clients, projects and long-term strategic relevance.
Zsolt Barna: After four years of actual stagnation, the Hungarian economy has finally returned to a growth path in 2026. While external uncertainties remain, business sentiment has become noticeably more positive, particularly among companies planning new investments.
From the banking sector’s perspective, fundamentals remain strong. Despite the sector’s high tax burden, profitability remains stable, banks are wellcapitalized and liquidity is ample. At MBH Bank, we continue to see healthy demand in retail banking, supported by rising household incomes, while corporate lending is also showing some early signs of recovery as business confidence gradually improves.
Loan portfolio quality remains stable and continues to improve, keeping risk costs under control. Overall, Hungarian banks, including MBH Bank, are well