The Brighton Buzz Today, Mother’s Day is celebrated with flowers, cards, and brunches, but the origin of Mother’s Day was more than a single day event.
Mother’s Day can be traced back to Anna Jarvis, an American woman who sought to honor her own mother, who was a peace activist during the American Civil War. Her mother, Ann, organized “Mothers’ Day Work Clubs” to improve sanitary conditions and reduce infant mortality. After the war, she worked to mend divided communities, bringing together mothers from both sides of the conflict.
When she passed, her daughter Anna was determined to create a national day to honor the sacrifices mothers made for their children. In 1908, she organized the first official Mother’s Day celebration. The event was deeply personal and reflective, emphasizing gratitude, remembrance, and the emotional bond between mother and child.
President Woodrow Wilson officially proclaimed Mother’s Day a national holiday, to be celebrated on the second Sunday of May. From there, the tradition spread internationally, with many countries adopting their own versions of the holiday—sometimes on different dates, but with a similar spirit of appreciation. To all the mothers in our communities, and everywhere…
Happy Mother’s May (Day),
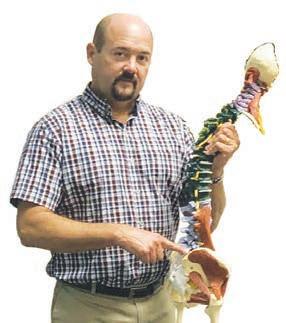
Apnea
Underdeveloped Mouth and Jaws
• Underdeveloped upper jaw
• Narrow palatal dental arch
• Crowded/ crooked teeth
Which may often lead to
• Underdeveloped lower jaw
• Teeth grinding
• Crossbite
• Tongue-tie Where it may begin
Nasal and Dental Abnormalities
• Nasal dysfunction and structural abnormalities
• TMJ dysfunction
• Bony growths in the oral cavity
• Nasal resistance and obstruction
• Swollen tonsils/ adenoids
• Dry mouth
• Mouth breathing
• Narrow palatal dental arch
• Obstructive sleep apnea (OSA)
• Crowded/ crooked teeth
• Upper airway resistance syndrome
• Teeth grinding
• Improper tongue position
• Crossbite
• TMJ dysfunction
• Bony growths in the oral cavity
• Nasal resistance and obstruction
Many Debilitating and Chronic Comorbidities
Breathing and Sleep Disorders
• Mouth breathing
• Cardiovascular disease
• Hypertension
• Fibromyalgia
• Bedwetting
• ADD/ADHD
• Excessive drowsiness And may often lead to . .
• Obstructive sleep apnea (OSA)
• Upper airway resistance syndrome Which may often result
TAX DEDUCTING YOUR HOBBY?
Is Your Side Gig a Business or a Hobby?
Lisa Price Senior Accountant
Do you have a side activity generating income—or losses—on your tax return? If you’re deducting losses on your Form 1040, it’s critical that your activity qualifies as a business in the eyes of the Internal Revenue Service.
e IRS often challenges money-losing ventures, reclassifying them as hobbies. Why it matters: under the Tax Cuts and Jobs Act (still impacting 2024–2026 fi lings), hobby expenses are not deductible, while business losses generally are. So what determines business vs. hobby? e key is profit motive —your intent to earn a profit. e IRS evaluates several factors:
• Operating in a businesslike manner (separate accounts, accurate records, strategic changes)
• Expertise or use of qualified advisors
• Time and effort invested
• Expectation of asset appreciation (common in real estate)
• History of income vs. losses (occasional profits help your case)
• Success in other ventures
• Your fi nancial situation (consistent losses with substantial outside income may raise flags)
• Degree of personal enjoyment (activities with high recreational value face more scrutiny)
No single factor is decisive—the IRS looks at the full picture.
Current planning insight: With increased IRS enforcement and continued limits on miscellaneous deductions, documenting your intent and operations is more important than ever. Clean books, a written business plan, and evidence of efforts to improve profitability can make the difference.
If your side activity is consistently losing money, it’s time to reassess—either strengthen your business position or adjust expectations.
Need help protecting your deductions or turning your side gig into a profitable business? Pricewise Business Solutions can guide you.
Back in Balance CHIROPRACTIC Massage & Laser
(Part 4 of 6)
Thestorybook marriage was over, Mary had lost her job, and with the extra time at home she discovered her husband’s infidelity. Mary’s father had died seven years ago and left her a substantial inheritance. Not believing that her husband could do such a thing, Mary had simply combined the inheritance with the other marital assets. Unfortunately, in the divorce there was no way to distinguish the inheritance from the marital property. Being unable to determine the difference, the judge divided all of the assets between Mary and her unfaithful husband. To add insult to injury, half of Mary’s inheritance was awarded to her ex-husband.
But the outcome didn’t have to be this way. If Mary’s father had done a thorough estate plan, he would have left the inheritance to Mary in trust. Mary would control the trust, but the trust would help her keep the inherited assets separate from the marital assets. If Mary used the assets inside the trust for her benefit, but did not draw them out of the trust and spend them, she could have easily identified the inherited assets in the divorce. As a result, the inherited assets would not have been divided in the divorce.
Estate planning can and should be more than avoiding probate and saving taxes. A properly designed estate plan can provide many additional advantages that protect your family. Most of these protections are ignored in cookie-cutter form-driven estate plans. Individuals should look closely at all of the benefits a properly designed estate plan can provide to them while they are alive, and provide to their families after their death. After all, when is it okay that your child’s ex-spouse receives the inheritance you left to your child?
If you have questions about effective estate planning, we encourage you to gain more knowledge about available planning options by visiting www.EstatePlans atWork.com to sign up for a complimentary small
educational workshop.
Who’s Kicking Your Cat?
O ered by: Colorado Karate Club
I’m sitting in my office when Jake’s dad walks in with a big smile. He was so excited to tell me how Jake is doing at home. Not only is Jake listening the first time his parents ask him to do something, but he’s also being kind to his cousin. e boy who once struggled to share is now happily sharing toys and helping out. at conversation made my week. Hearing stories like Jake’s reinforce the belief that the work that we do here goes well beyond the dojo walls.
You see, improvement like that doesn’t stop with Jake. It spreads. Jake’s cousin benefits. Jake’s parents are happier. His cousin’s parents feel it too. And when families are happier, it shows up everywhere, at work, in relationships, in the community. One small change in a child can spread outward in ways we’ll never fully see.
But this cascading effect works both ways.
One of my favorite Zig Ziglar stories is called “Who’s Kicking Your Cat?” A boss gets a speeding ticket on his way to work and storms into the office fuming. He snaps at his sales manager. e manager, now irritated, barks at his secretary. She goes home and yells at her son.
e boy, annoyed, sees the family cat stroll by and gives it a swift kick. Ziglar’s point is simple: Wouldn’t it have been easier for the boss to just kick the cat himself and spare everyone else? en he asks the deeper question: Who’s kicking your cat? Or, even more important, whose cat are you kicking?
Our actions, good or bad, spread outwardly in ways we rarely get to see. A bad mood can travel from one person to the next like falling dominoes. But the opposite is also true. When Jake learns respect, patience, and self-control on the mat, those same qualities show up at the dinner table, in the backyard with his cousin, and in the way his parents interact with each other. Happier kids make happier homes. Happier homes make stronger neighborhoods. e positive wave keeps moving, often to people we will never meet.
More than four decades ago, my own Sensei, Luis Chiock in Lima, Peru, passed those same lessons on to me and to hundreds of other students. And I have watched thousands of students walk through our doors here in Colorado. Yesterday, as I watched our older students in the instructor-training program, I caught a glimpse of something great: those lessons will keep traveling long after I’m gone, through my students, through their students, and into families I will never meet.
So here’s the choice we all get to make every single day: Will we pass along frustration, or will we pass along kindness? Will we kick someone’s cat down the line, or will we be the person who brightens their day, lifts their week, and maybe even changes the course of their life?
You may never see the full effect of your smile, your patience, or your encouraging words. But trust me, it’s there. And that invisible, farreaching effect is what makes every human interaction so important and meaningful.
Sensei Willy Strohmeier Colorado Karate Club
Valuable Resources
Avoiding Tax Scams
Offered by T. Lloyd Worth, Worth Wealth Management
What are Tax Scams?
Tax scams involve bad actors — who impersonate the IRS, tax professionals, or government entities over the phone, through text, online, or by email — and are designed to trick you into providing sensitive information or sending money for taxes, penalties, and fees you don’t owe.
According to the Internal Revenue Service’s Criminal Investigation Team, they initiated 1,409 tax crime investigations and identified $5.5 billion in tax fraud in 2023. Tax scams peak the highest during tax season, therefore it is crucial to remain vigilant and verify the legitimacy of any communication or request related to taxes.
Tax Scam Methods
There are many methods cybercriminals use for tax scams, and they often deploy creative tactics to deceive their victims. The methods listed below are not the only methods a cybercriminal can use.
Fake Tax Refund: A new scheme that involves bad actors mailing letters impersonating the IRS. The letter may claim that there is a notice in relation to an unclaimed tax refund.
IRS Call: Impersonation phone calls also known as vishing may occur, where callers will pose as IRS agents and use fake credentials in hopes of stealing taxpayer funds or personal information. These scammers may know a lot about their victims and will intimidate them into making a hasty decision.
Phishing email: Scammers will send several email alerts attempting to trick people into thinking their emails are legitimate notices from the IRS. These phishing emails will seek information related to refunds, filing status, confirming personal identity, and late payments.
How to identify and deal with Tax Fraud:
Tax scams become increasingly popular during tax season, but here are some ways to identify them:
• Use caution with unsolicited communications. contact via traditional mail. Be wary of unexpected calls, emails, or texts claiming to be from the IRS or any tax authority, especially if they require immediate payment or threaten legal action.
• Verify sources. If you receive any communication claiming to be the IRS or a tax professional, verify its legitimacy by navigating to the official website or contact a verified phone number.
• Be alert of phishing attempts. requesting sensitive or financial information. Legitimate organizations like the IRS will not ask for this information via email or phone.
• Resist scare tactics. Scammers will often use intimidation or urgency to bait victims into making a rushed decision, not in their best interest. We recommend you take your time, thoroughly evaluate requests, and verify all urgent requests.
• Secure personal information.
Security numbers and financial details to prevent identity theft and tax fraud.
• Educate yourself Stay informed on the latest tax scams used by fraudsters. More awareness allows you mitigate risks and attacks.
Additional Considerations
If a scammer accessed your accounts…
If a scammer has access to financial information…
If a scammer has your social security number…
If you have questions about this or any personal financial issues, please reach out to Worth Wealth Management at Lloyd.Worth@LPL.com.
Boosting
Back-to-School Success: Why Summer Neurofeedback Can Help Kids Thrive
Assummer begins, many parents look for ways to give their children a strong start for the upcoming school year. Neurofeedback training—a non-invasive method designed to improve how the brain functions is a great option!
Neurofeedback uses sensors placed on the scalp to monitor brainwave activity while a child watches a screen, listens to music or plays a game. e system provides real-time feedback, helping the brain learn to regulate itself more efficiently over time.
Summer is an ideal time to begin. Without the demands of homework and busy schedules, children can attend sessions consistently—an important factor in effectiveness—and build skills before academic pressures return.
For children with ADHD, neurofeedback has shown evidence of improving attention, impulse control, and focus in some clinical studies. It is often used alongside behavioral strategies.
Neurofeedback may also support children experiencing Anxiety disorders, Depression, and Insomnia—all of which can negatively impact academic performance, mood, and classroom behavior. Some research suggests improvements in emotional regulation and sleep patterns.
Children with learning difficulties may benefit as well, with potential gains in attention span, working memory, and processing speed. Even children without specific challenges may see “peak performance” benefits, including better focus, resilience, and mental stamina.
Neurofeedback is considered safe and medication-free, but it requires commitment which is why summer is the PERFECT time!
Locally, families in Brighton have access to a unique resource: Christy Kennedy M.S., BCN the only board-certified neurofeedback practitioner serving the area, offering specialized training tailored to each child’s needs. Ready to get started? Contact Integrated Wellness Associates at 720-317-3022 to schedule a consultation and learn how neurofeedback can support your child’s success this school year.
Who You’re Going To Call
Offered by: Forrest Hough - Edward Jones
Key takeaways
• Despite their tax advantages, just 14% of adults include a 529 plan in their education savings strategy, according to a 2025 Edward Jones and Morning Consult study.
• 529 funds cover college, vocational programs, registered apprenticeships and can be used towards K-12 education.
• In addition to tuition, 529 funds can pay for students’ day-to-day needs like internet, computers, qualified room and board, and certain K-12 tutoring costs.
A 529 education savings plan might sound like something only families with college-bound kids need. But the versatility of a 529 account may surprise you, whether your child heads to a four-year university, a trade school or elsewhere.
1. What are the tax benefits of a 529 education savings plan?
Earnings in a 529 plan grow free from federal taxes, and withdrawals used for qualified education expenses are also federally taxfree. While 529 contributions are not federally deductible, many states allow a deduction on your state return.
Despite their tax advantages, just 14% of adults include a 529 plan in their education savings strategy, according to a 2025 Edward Jones and Morning Consult study. Instead, most families rely on traditional personal savings accounts.
2. Can a 529 be used if my child doesn’t attend a traditional college?
Beyond four-year colleges, you can use 529 funds for community colleges, graduate schools and vocational programs. Apprenticeships in fields like plumbing, electrical work and welding qualify too, provided they are registered with the U.S. Department of Labor.
If your child earns a scholarship, you can withdraw up to that amount from your 529 account without penalty, though earnings may still be taxable.
3. What does a 529 plan cover beyond tuition?
Qualified costs for 529 plan withdrawals include books, supplies, computers, internet access and educational software. For students enrolled at least half time, room and board also qualify, including off-campus housing up to what the school sets as its cost of attendance.
Recent changes in the law expanded 529 plan qualified expenses. Some new eligible expenses include certain testing fees, instructional materials, academic tutoring, and educational therapies for students with disabilities.
For K-12, you can use up to $20,000 from your 529 account per year for tuition, certain tutoring and curriculum materials.
4. What if I don’t use all the money in my 529 account ?
If one child doesn’t need the 529 funds, you can transfer that account to a sibling, another qualifying family member or even yourself. You can also use 529 funds to pay up to $10,000 in student loans, roll them into a Roth IRA for the beneficiary up to $35,000 (subject to certain limits and criteria) or roll them into a disability savings account (ABLE account) for the beneficiary or a family member.
With so many options for investing, withdrawals and redirecting the money, a 529 plan is one of the more flexible tools available for families thinking about education costs. A financial advisor can walk you through the details and help you choose a plan that fits your overall financial strategy.
Join us for a virtual event on May 29th at 12:00pm, to learn about 529 College Savings Plans and discover how to take advantage of matching dollars for your child’s future education. Contact our office to RSVP and receive the virtual link.
Make
your
financial future a priority
The market may change often, but your important financial goals probably don’t.
Brighton: The power of personal attention working for you.
We believe the best way to build and preserve your financial future is by taking a long-term approach to investing. That’s why we don’t follow investment fads.
What matters most to you matters to us.
No matter what your path forward looks like, I’ll work with you every step of the way to develop thoughtful, tailored strategies, so you can see the road ahead and move along it with confidence.
We’ll help you identify and define your unique financial goals. And then we’ll tailor investment strategies that help you work toward those goals.
Our single focus is helping you achieve what’s most important to you. And you’ll be backed by our entire team each step of the way.
Let’s prepare for your future together.
720-769-9203 Let’s prepare for your future together.
21 N 1st Ave Suite 290
Brighton, CO 80601
We can help get you started.
Tim Roberts, CFP®, CEPA®, CRPC™ Financial Advisor
21 N 1st Ave Suite 290
Brighton, CO 80601
303-659-2301
Who You’re Going To Call
65 and Employed: What You Need to Know About Medicare
Turning 65 once meant retirement, but today, many of us are still working, thriving, and not quite ready to step away from our careers. With that milestone comes an important question: what to do about Medicare. It’s easy to assume you can delay enrollment without consequence, but the reality is more nuanced. Your decision can have financial and healthcare implications, so it’s worth understanding how your current coverage fits into the bigger picture.
If you are self-employed it is likely you need to follow strict enrollment timelines and sign up for Medicare, please call us for guidance.
If you’re covered through your job (or a spouse’s and they currently work), you may be able to postpone Medicare, but only if the employer has 20 or more employees and you are on that group coverage with RX benefits also. In that case, your work plan may remain primary. If your employer is smaller, Medicare typically becomes primary at 65, making enrollment necessary. Missing your enrollment window when required could result in lifelong penalties, so understanding your situation is key.
Turning 65 while still working puts you in a position of choice—but also responsibility. Reviewing your health coverage and your known needs, speaking with your HR department, and understanding Medicare’s rules can help you avoid costly missteps. With the right information, you can keep working confidently while making smart decisions about your healthcare future.
If you have questions, give me a call. ere is no obligation and my service is never a cost to you.
Brighton Roofer
Insurance Accepted • Self Pay Discounts Offered
Financing Available • Independent, Multi-line Dealer • HSA and FSA Cards Accepted
• Comprehensive Hearing Evaluations and Screenings
• Tinnitus Evaluations & FDA Approved Tinnitus Solutions
• Hearing Aid Cleaning/Maintenance, Modification, Repair, and Service
• Ear Wax Removal, Hearing Protection, and other Ear Health Products
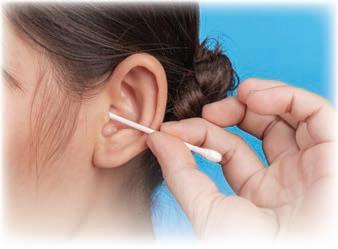
Recently a patient came in with his wife for a routine hearing aid and ear cleaning appointment. After looking into his ear canal, I asked him when he last used a Q-tip to clean his ear. He said he had used one that morning. His wife asked how I knew he had used a Q-tip, and so I showed her some of the signs that indicated he had used a cotton swab to clean his ear.
Using my video otoscope, I was able to show them on the monitor what I was seeing. I pointed out the two most obvious signs. e fi rst was a hematoma (bruise) next to the eardrum. e second was significant wax impacted near the eardrum, while there was nothing in the outer portion of the canal where earwax is produced. ey were both surprised by the location of the bruise and that he had actually pushed the Q-tip so close to the eardrum (within a few millimeters.)
Earwax is completely normal and natural and not necessarily a sign of poor hygiene. If everything is working normally, the ear will produce two excretions that make up earwax. e fi rst is sebaceous, an oil that is secreted from glands that are found in the ear, as well as throughout the body. e second is cerumen, which is excreted from glands found only in the ear, typically in the outer portion of the ear canal. ese excretions, along with fi ne hairs, protect the ear canal from foreign materials such as dirt, dust or bugs. As new skin cells grow, dead skin sloughs off and combines with the wax. e skin in the ear canal grows outward away from the eardrum and carries wax to the opening of the canal. (Some individuals have a condition where the skin grows the opposite direction, which causes the wax and dead skin to build up on the eardrum.) As the combination of substances
migrates to the canal opening and into the concha, or bowl of the ear, it can then be wiped or washed out. It is not unusual to have to clean wax from the concha on a daily basis.
In some cases, the wax does not work its way out of the canal as it should. is may happen because the ear canal is too narrow, wax production is excessive, the earwax is exceptionally sticky, or the wax is pushed back into the canal by foreign objects such as a Q-tip. In addition, protective earplugs, earphones or even hearing aids can prevent the wax from migrating outward, or push it back into the canal.
When wax does not work itself out of the canal as it should, it can block the ear canal. is blockage will cause some level of hearing loss, ranging from mild to total conductive hearing loss depending on the amount, composition and location of the wax. Water can become trapped around and behind the earwax, which can lead to an external ear infection from bacteria or fungus.
ough over the counter products exist for wax removal, we recommend never putting anything into the canal until the condition and contents of the canal can be verified. If you experience sudden hearing loss, have your ears checked immediately. Sudden onset hearing loss from earwax impaction is reversible, while sudden onset loss from other causes is often permanent if not reversed with immediate medical care.
Retiring this Summer?
O ered by:
A
lot of people look at summer as the perfect time to retire. You’ve put in A LOT of years with an employer and you’re ready to do what YOU want to do, whenever YOU want to do it. I say go for it!!
When you are looking to retire from a career that has offered you Health Benefits, Life Insurance, 401K Retirement Investment options, and maybe even Long Term Care Insurance, you face retirement with so many questions. How are you supposed to do it all alone?
e great news is, you don’t have to navigate the craziness alone.
Let’s start with your Health Insurance and we will cover the rest in the following summer articles. If you are 65 or older, you are eligible for Medicare. You may already have Medicare Part A. When you retire, you will need to apply for Medicare through Social Security. at’s right, Social Security will administer your Medicare Application. ey verify you worked the qualifying quarters in the US and are entitled to Medicare.
If you already have Part A, there is a form to apply for Part B – CMS Form 40B. If you do not have Part A, you can either do an online application on ssa.gov or you can call and schedule an appointment with your local SSA Office and do the application over the phone.
If you are over 65, you will need a form completed by your employer to show that you have been on a creditable Employer Group Health Plan since turning 65. is form is called “Medicare Request for Employment Information” (CMS Form L564). You can download this form and the Part B Application with a simple Google search – just be sure you are on cms.gov before you download.
Send the CMS L564 form to your HR Department so they can get you the correct information. Once you have the form completed, you can apply for Medicare. Be sure to match the employment dates and health plan coverage dates the employer inputs to what you put on your Medicare application.
If this all sounds like a foreign language, don’t stress, I can help. Please call or text my assistant to schedule a free appointment: 720-665-6015
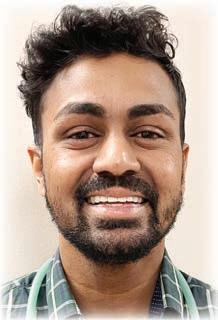
Welcome, Dr. Philip!
O ered by: Premier Pediatrics
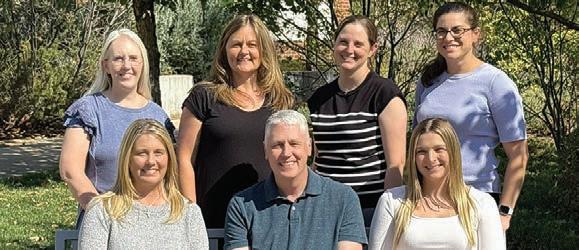
Premier Pediatrics is excited to welcome our newest physician, Dr. Georgie Philip! Dr. Philip joins the Premier Pediatrics team April 20, 2026.
Dr. Philip is originally from the Chicagoland area and moved to Colorado in 2021 for his wife’s doctoral program in school psychology.
He has a passion for connecting with patients and colleagues in a perceptive and practical manner. He is focused on growth & development, infection prevention and control, and providing equitable care for everyone in his community.
He has received multiple honors throughout his career including employee recognition, teaching, and research awards.
His personal interests include exploring new restaurants, spending time with his wife and little guy, traveling with them all over the world, and staying involved in his affirming church.
To schedule an appointment with Dr. Philip or one of our other providers, please contact us at 303-655-1685 or at premierpediatrics.us
The purpose of the Advisory Board is to advise and assist in the needs and operations of SCAAC. The Board meets Tues. May 19 and June 16 at 1:00 p.m. Members are: Dennis Gibbons, Peggy Jarrett, Lou Ellen Bromley, Dan Buckner, Karen Swaithes, Steve Yarish, Bill Alsdorf, Heidi Storz, Gayle Shibao, Barbara Spakoski, Janet Olivieri, and Randy Thornton. Visitors are welcome.
Charitable Contributions
Together we can continue to enhance the great programs and services offered for seniors and active adults in the Brighton area. Your financial support will be recognized on the donor wall at Eagle View. All donations are tax deductible. Make donations payable to: Brighton United Senior Citizens, 1150 Prairie Center Parkway, Brighton, CO 80601.
Donor Opportunities for Wall Recognition:
Friend: $100 - $499
Memorial: $100+
Sponsor: $500 - $999
Benefactor: $1000+
Outreach & Referral
Do you need help and are unsure where to turn?
Evon Benitez will assist you with completing forms and finding needed services. You’ll need to make an appointment to see Evon as she’s often meeting with others. To make an appointment, call Evon at 303-6552079. Leave a message.
MAY
HAPPENINGS
Medicare & Health Insurance Counseling
Get one-on-one help with Medicare or under-65 health insurance from the licensed team at Headwaters Health and Wealth. To schedule an appointment, call Nina at 303-655-2079, or contact the team at 303-887-8584 for general questions. Appointments are recommended; drop-ins are welcome as availability allows.
9:00 - 11:30 a.m.
Free 1st and 3rd Wednesdays
Deadline: Mon. before
Hair Sparkles
Silk hair tinsel adds weeks-long sparkle to clean, straight or slightly wavy hair at least 4” long. Book at the front desk and pay Rosalie Farrer directly (cash only).
Thursdays & Fridays
$32 for 30 minutes
Deadline: 2 days ahead
VOA Lunch
1150 Prairie Center Parkway, Brighton, CO 80601
303-655-2075 I evacinfo@brightonco.gov www.brightonco.gov
Hours: Monday - Friday 8:00 a.m. - 4:00 p.m.
A hot, nutritious lunch is provided by Volunteers of America, Mondays and Thursdays at 11:30 a.m. Please reserve your meal in advance. For Mondays, reserve the Thursday before; for Thursdays, reserve the Monday before. Call Eleanor at 303-655-2271 between 10:00 a.m. - 2:00 p.m. Mon. & Thurs. to make a reservation.
Daily meal donations are appreciated.
$2.50 Donation per meal if age 60+
$8.50 Mandatory charge if under 60
Medical Equipment Loans
Basic medical equipment is available to loan out. Items may include wheelchairs, front wheel and seated walkers, canes, crutches, toilet seat risers, commodes, and bath benches. There is no guarantee what will be available at any time. Call 303-655-2075 for information.
Senior Wellness Clinic
The Clinic focuses on health promotion and disease prevention for seniors 55+. Operated by Visiting Nurses Association (VNA), services include foot care, health checks, and blood pressure checks. The fee for foot care is $40 payable at the time of your appointment. Foot care may be covered by Kaiser with pre-approval. Reduced fee available upon approval. Call 303-655-2075 for appointment.
Tech Tuesdays
Need help with your laptop, tablet, or smartphone? We will do our best to help you become more comfortable using your device. Schedule an appointment with Calvin at 303-655-2187.
Community Resources
Do you need help and are unsure where to turn? We will assist you with completing forms and finding needed services. You’ll need to make an appointment. To make an appointment, call Nina Banks at 303-6552079. Leave a message.
Transportation
Via Mobility - provides specialized transportation within the City of Brighton. Via can take you to medical appointments, grocery shopping, and Eagle View, to name just a few of the places you can go in Brighton. New Via users - call 303-447-2848 ext. 1014 to get started. To schedule rides, call 303-447-9636. Free rides to and from Eagle View to seniors living in the Brighton Via service area are provided by funding from the Senior Advisory Board.
FlexRide
This is an RTD service. Call 303-299-6000 for reservations. The driver will pick up and deliver you anywhere within Brighton, Mon - Fri. 6:00 a.m.7:00 p.m. Cost is the local RTD bus fare.
Zoom Membership
You will need to purchase a Zoom membership for each newsletter in order to participate online. Purchasing a membership will give you access to all SCAAC’s programs that are being offered on Zoom for two months. Only Zoom members will receive the E-Blast with Zoom links. To register, see page 2 on the registration sheet. Cost: $20 for two months. May & June Membership - $20 Deadline: Ongoing
Grumpy Old Men!
Drop in for coffee and easy talking about being an old guy. Let’s talk about relationships, health, money, cars and current events. Facilitated by Don O’Malley, an old guy who used to work as a counselor and loves Hank Williams Sr., Tony Bennett, and Led Zepplin.
Fridays - 8:15 a.m.
Free
Kindness Counts
This group is about spreading a little kindness throughout the community. Each month we pick a project. Call Ashleigh at 303-655-2076 for information.
Wed. May 13 - 11:00 a.m.
Duplicate Bridge
In Duplicate Bridge, teams of two compete using set hands to earn points by outplaying others. Play with the same partner for a two-month challenge - highest scores earn recognition! Facilitator: Bobbi Jo Unruh. 11:30 a.m. - 3:30 p.m.
Wed. May 13 & 27
$10 (2 wks)
Deadline: Mon. May 11
Book Club
Books are chosen at the previous meeting. If you were unable to attend, call the front desk for the title. Please read the book beforehand to prepare for discussion. Books can be found at libraries, bookstores, etc. Facilitated by Gayle Wudarczyk.
Wed. May 13 - 1:00 p.m.
Free
Deadline: Mon. May 11
Affordable Housing
Join Shawn Weiman as he introduces Brighton’s Housing Authority’s role in affordable housing, explains the difference between affordable housing vs. housing that is affordable, and gives a brief overview of the existing and upcoming affordable housing developments in Brighton.
Wed. May 13 - 1:30 p.m.
Free
Deadline: Mon. May 11
Bunco
Bunco is an easy and fun game of dice. Enjoy an afternoon of fun, laughter, and prizes.
Thursdays - 1:15 p.m.
May 14 & 28
$4 (each)
Deadline: Wed. before
CEMETERY OFFERING
Community Living
Hometown Dumpster Rentals
[EAGLEVIEW Continued from page 34]
MAY HAPPENINGS (Cont’d)
Louis Armstrong
EVAC & Zoom
Louis “Satchmo” Armstrong, a New Orleans-born jazz trumpeter and vocalist, shaped 20th-century American music over a five-decade career and played a key role in improving racial relations.
Presenter: Paul Flanders.
Thurs. May 14 - 1:30 p.m.
$4.00
Deadline: Tues. May 12
Learn the Truth about Reverse Mortgages
Are you 62+ and own a home or are looking to buy a home? You may qualify for a Reverse Mortgage to alleviate a principal and interest payment, gain extra retirement income, or buy your dream home. Learn about your options.
Instructor: Jackie Hahn.
Thurs. May 14 - 2:00 - 3:00 p.m.
Free
Deadline: Tues. May 12
Almost Heaven, West Virginia
This month we’re headed to West Virginia, the scenic “Mountain State” and birthplace of the first official Mother’s Day celebration in 1908. Explore its history, hike the Appalachian Trail, and learn about local favorites like pepperoni rolls and cathead biscuits - plus pick up some unique West Virginian slang.
Presenter: Travels with Toni.
Fri. May 15 - 1:30 p.m.
$5.00
Deadline: Wed. May 13
Feathered Friends: American Kestrel
Meet REF’s newest (and youngest!) ambassador - a male American kestrel. Learn about this colorful year-round hunter, its decline in parts of the U.S., and how you can help support nesting in your yard.
Tues. May 19 - 1:00 p.m.
$5.00
Deadline: Fri. May 15
Please visit www.brightonco.gov for a complete listing of all offerings.
Rain or Shine - Play Sudoku any time!
udoku is one of the most popular puzzle games of all time. As a logic puzzle, Sudoku is also an excellent brain game. If you play Sudoku daily, you will soon start to see improvements in your concentration and overall brain power. Start a game today and make it a part of your daily brain workout!
The goal of Sudoku is to fill in a 9×9 grid with digits so that each column, row, and 3×3 section contain the numbers between 1 to 9. At the beginning of the game, the 9×9 grid will have some of the squares filled in. Your job is to use logic to fill in the missing digits and complete the grid. Don’t forget, a move is incorrect if:
• Any row contains more than one of the same number from 1 to 9
• Any 3×3 grid contains more than one of the same number from 1 to 9
• Any column contains more than one of the same number from 1 to 9
Community Living
Solution to Suduko
How to Price Your Home in a Buyer’s Market
Pricing your home well has always mattered. In today’s market, it may be your single greatest advantage.
e Denver Metro real estate market is showing real momentum heading into spring 2026. Closed sales jumped in March, days on market dropped to just 16 days, and homes are closing at just over 99% of list price. at’s not a sluggish market. It’s a market finding its footing. But that doesn’t mean every home sells itself. With new listings climbing and buyers who are more thoughtful and informed, how you position your home from day one carries more weight.
Start with the Right Data
A smart pricing strategy begins with recent, truly comparable sales, not active listings or aspirational pricing. Focus on homes similar in size, condition, and location that have actually closed.
From there, layer in current conditions. More homes are entering the market this spring, giving buyers more choice and more leverage. Pricing should reflect that reality. Positioned thoughtfully relative to the competition, a well-set price can create stronger interest, expand your buyer pool, and support more competitive offers.
6
2
8
Timing and Positioning Work Together
Even the right price needs support. Professional photography and thoughtful staging help buyers understand the value being presented. e first two weeks on the market are especially important. Showing activity during that window is one of the clearest indicators of whether pricing is aligned. If traffic is lighter than expected, adjusting early helps preserve momentum before a listing begins to sit longer than intended.
It’s also worth recognizing that the market isn’t uniform. Detached homes in strong locations continue to perform well, while condos and townhomes are seeing more resistance, often tied to HOA costs and insurance. ese factors should be considered when establishing a pricing strategy.
Pricing and Market Response
Homes priced in line with current market conditions tend to attract more interest and move through the process more efficiently. Properties that are priced above market expectations may take longer to sell and may require adjustments over time.
Buyers are attentive to how long a home has been on the market, and pricing changes can influence perception. Entering the market with a well-supported price helps maintain consistency and encourages stronger engagement from the outset.
A Steady, Informed Approach
Pricing a home in an active, evolving market isn’t guesswork. It’s a strategy built on local insight and informed decision-making. A Berkshire Hathaway HomeServices Forever Agent SM can help you interpret the data, understand your competition, and position your home for today’s conditions.
If you’re considering a move, having that perspective can make the process more straightforward and more predictable. To start the conversation, call 303-905-8850 or visit BHHScoloradorealestate.com
O ered by: Scott and Lora Nordby, Berkshire Hathaway
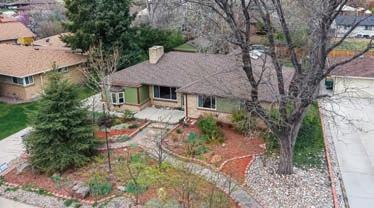
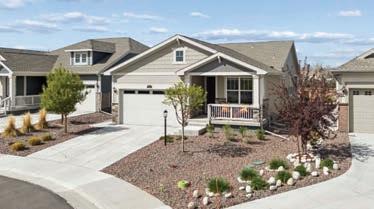
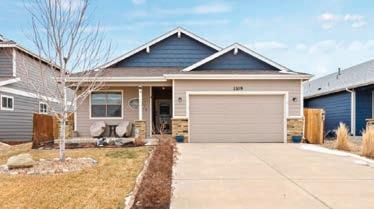
$715,500
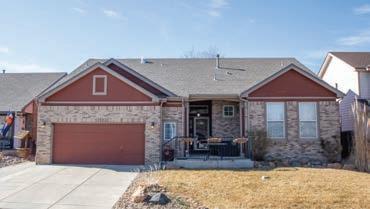
3 Bed | 2 Bath | 2,126 Sq Ft 545 Estes Street, Lakewood, CO Greg Kitzmiller 303-960-5489
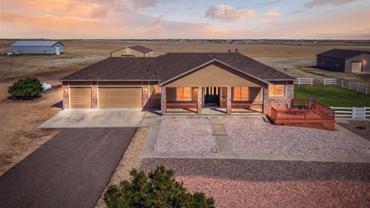
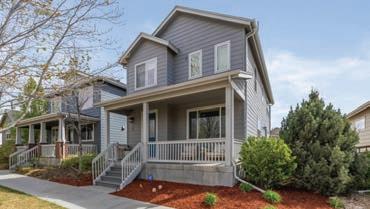
5 Beds | 3 Bath | 3,420 Sq Ft 555 S 17th Avenue, Brighton, CO Beth & Dan Cochran 303-548-5568 BRIGHTON $635,000
$440,000
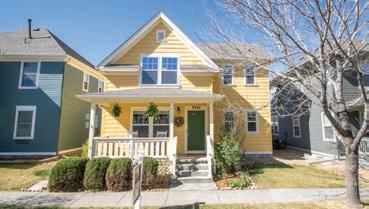
3 Beds | 2 Bath | 2,076 Sq Ft 9264 E 108th Place, Henderson, CO Beth & Dan Cochran 303-548-5568
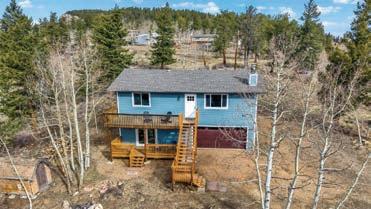
$442,500 3 Beds | 4 Bath | 2,542 Sq Ft 74 S 45th Ave, Brighton, CO Deanna Gamboa 720-422-9320 BRIGHTON $510,000