

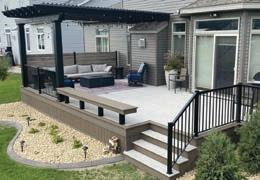
Hot Summer Ahead –Is Your Yard Ready?
Dawa Sherpa Publisher The Brighton Buzz

Dawa Sherpa Publisher The Brighton Buzz
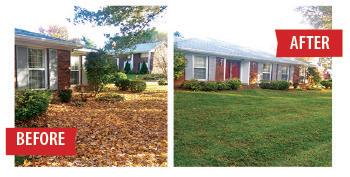
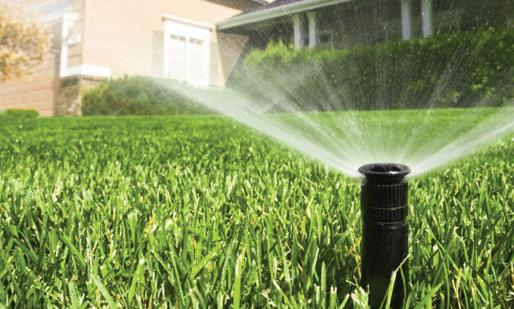
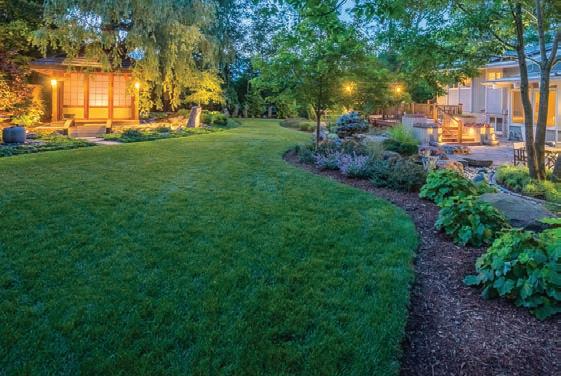
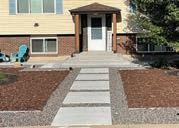
Last spring I spoke of our family’s desire to spruce up our yard, and in my humble opinion, I think it was a success. But this spring, with the extremely dry winter we have experienced, outdoor water use will no doubt be limited. I love a green lawn, but as you can imagine, it’s one of the least sustainable elements in a Colorado yard. It demands frequent watering, struggles in heat, and often conflicts with water restrictions.
As you would expect, when watering in drought conditions — how you water matters more than how often. Most of us know that watering in early morning or evening to reduce evaporation and avoiding watering during heat, wind, or rain is a good practice. Using mulch to retain soil moisture and regulate temperature is another simple step. And, I’ve been told to consider prioritizing trees and new plants that are hardest to replace when deciding your water usage.
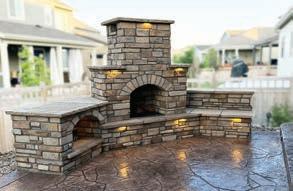
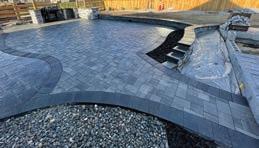
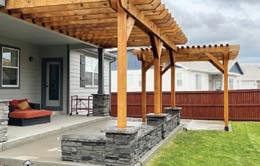
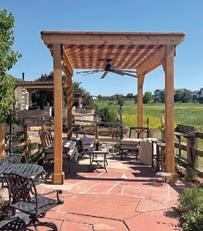
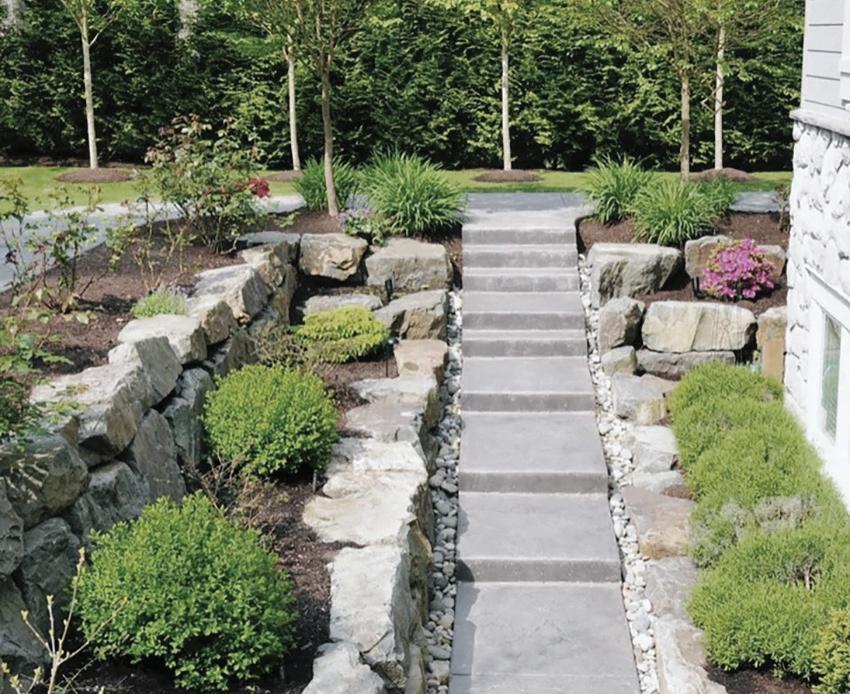
For those who may be considering long-term changes to your landscape toward more drought tolerant plants or even xeriscaping, look no further than our pages, as we offer many local businesses who can help you achieve and maintain the results you want. It’s not too early to get ready for the hot summer ahead.
Happy Spring,



O ered by: Premier Pediatrics
Premier Pediatrics is excited to welcome our newest physician, Dr. Georgie Philip! Dr. Philip joins the Premier Pediatrics team April 20, 2026.
Dr. Philip is originally from the Chicagoland area and moved to Colorado in 2021 for his wife’s doctoral program in school psychology.
He has a passion for connecting with patients and colleagues in a perceptive and practical manner. He is focused on growth & development, infection prevention and control, and providing equitable care for everyone in his community.
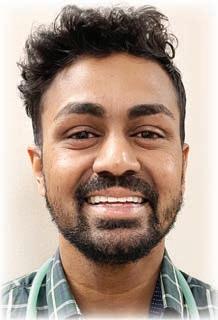
He has received multiple honors throughout his career including employee recognition, teaching, and research awards.
His personal interests include exploring new restaurants, spending time with his wife and little guy, traveling with them all over the world, and staying involved in his affirming church.
To schedule an appointment with Dr. Philip or one of our other providers, please contact us at 303-655-1685 or at premierpediatrics.us.

Filing a tax extension can be a strategic move for taxpayers who need additional time to prepare an accurate and complete return. By submitting IRS Form 4868, you receive an automatic six-month extension to file—moving the deadline from April to October. This added time can reduce stress and improve accuracy, but it’s important to understand both the advantages and limitations.
One of the key benefits of filing an extension is the ability to avoid errors. Taxpayers with more complex financial situations—such as business owners, freelancers, or those with multiple income streams—often need extra time to gather documentation and ensure everything is reported correctly. An extension allows for more thorough tax preparation, helping to reduce the likelihood of missed deductions, IRS notices, or the need to file amended returns.
However, it’s critical to remember that an extension to file is not an extension to pay. Any taxes owed are still due by the original filing deadline, typically April 15. If payment is not made on time, penalties and interest may accrue—even if you’ve filed an extension. Estimating your tax liability and submitting a payment with your extension can help minimize these additional costs.
There are also potential drawbacks, including the temptation to delay. Without a clear plan, some taxpayers may push filing off until October, creating unnecessary last-minute stress. Additionally, postponing your return may delay financial decisions that rely on finalized tax information.
If you’re considering filing an extension, the team at Pricewise Business Solutions is here to help. We’ll guide you through the process, ensure your estimates are accurate, and prepare your return with confidence. Contact us today at 720.949.7733 to stay compliant, reduce stress, and make the most of your tax strategy.



Bill and Jane’s daughter had struggled since the accident. She was only 13 when it happened, but after 10 years it was clear she was permanently disabled. Now 23, she is dependent upon government assistance for her survival and medical care.
Bill and Jane thought they did not need estate planning. Why not just put everything in joint tenancy, because “it is simple and may avoid probate.” inking about their disabled daughter, they sought guidance from a counseling-oriented attorney who took time to learn more about them, their estate, and their goals. eir primary objective was to protect their daughter after they died. e attorney worked with them to put together a plan that would place their savings, life insurance and home in a trust for their daughter, upon the second death. is would prevent the assets from disqualifying their daughter from the benefits she is receiving from government programs. As a result, the inheritance can pay for the things government programs do not cover, providing additional comfort to their daughter.
Estate planning can, and should, be more than avoiding probate and saving taxes. A properly designed estate plan can provide many additional advantages that protect your family. Most of these protections are ignored in basic estate plans. Individuals should look closely at all of the benefits a properly designed estate plan can provide to them while they are alive, and provide to their spouses and their families after their death. Does your estate plan address these types of issues?
If you have questions about effective estate planning, we encourage you to gain more knowledge about available planning options by visiting www.EstatePlans atWork.com to sign up for a complimentary
educational workshop.


e Way of the Dragon was my favorite movie as a kid. My brothers and I would play out the fighting scenes, throwing flying kicks on my parents’ bed like we were Bruce Lee and Chuck Norris. at is, until one amazing, high flying kick ended with a loud crack… followed by the thump of the bed collapsing onto the floor. Whoops!
A couple of bricks bought us a few weeks before my parents discovered the damage, but to our surprise it wasn’t a big deal. Instead, a few weeks later we were enrolled in Karate.
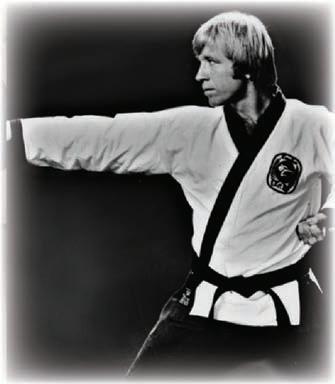
But that movie didn’t just break the bed. It helped launch a journey.
I credit Chuck Norris, Bruce Lee, and e Way of the Dragon with inspiring my brothers and I to start karate. Like so many others, we were drawn in by the action, but what stayed with us was something deeper. e Discipline, the structure, the respect.
Most people remember Chuck Norris for the fight scenes, the roundhouse kicks, and the larger-than-life persona. But beyond the action figure image, was a man defined by discipline, humility, and faith.
Chuck Norris didn’t just train, he committed. He showed up, did the work, and held himself to a higher standard. at kind of discipline builds more than skill, it builds character.
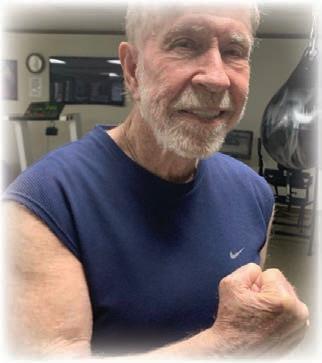
What set him apart even more was his humility. Despite his success, he carried himself with quiet confidence, respecting his teachers and staying grounded in his values. In a world that often rewards ego, he modeled strength without arrogance.
And his faith gave it all meaning. For Norris, martial arts wasn’t just about fighting, it was about becoming a better person and using your life to serve something greater. at’s the part that stayed with me.
As a kid, I loved the action. But as a karate school owner today, I see what really matters. e kicks may get students in the door, but it’s the lessons in discipline, respect, and confidence that keep them growing.
Today, when I watch my students line up on the mat, some nervous, some excited, I’m reminded that legacy isn’t built through fame, but through impact. It lives in the people you influence.
In every student who learns to focus, to persevere, to lead. at legacy endures.
So, heroes in fact, never die, they just step back, and let the rest of us, those who they inspired, to carry on their torch.



Independent, Multi-line Dealer
HSA and FSA Cards Accepted
• Comprehensive Hearing Evaluations and Screenings
• Tinnitus Evaluations & FDA Approved Tinnitus Solutions
• Hearing Aid Cleaning/Maintenance, Modification, Repair, and Service
• Ear Wax Removal, Hearing Protection, and other Ear Health Products
Recently my daughter was practicing a piano piece to perform at a talent show. Instead of playing on a regular piano however, she was playing on a portable electronic keyboard that she was going to have to take to the performance. She had become frustrated because when she pressed the keys some of the notes sounded distorted. She did not completely understand why, but explained to me that she had fi gured out how to fi x the problem by connecting an external amplifier to the keyboard instead of using the internal speakers.
I asked her if she had been turning the volume up all the way when she was playing. She said she had regularly maximized the volume in the past because it sounded better. I went on to explain to her that by doing so, at some point the excessive energy going through the system had blown one or more of the speakers. She gave me a quizzical look and asked what I meant. I explained to her a little about how speakers work and how turning the volume up too loud can destroy the speaker’s ability to produce the correct sound. I told her that in my younger years it was common for speakers in cars, stereos or televisions to be “blown out” from teenagers turning the volume up too loud.
evaluation we determined she had a severe hearing loss and she very reluctantly got hearing aids.
During a follow up visit, she expressed that she was both happy and upset; happy because she could better hear and understand her family and friends, but upset that she could not understand the television. I suggested that the problem may be with the TV speakers (because I knew how bad her hearing was and the only way she would have been able to hear the TV without hearing aids would be to turn up the volume full blast.)
She left the appointment upset, thinking that there was no way there was anything wrong with the television speakers. At the next appointment she said her son had confi rmed the speaker on the television was blown out. She admitted she had been maximizing the volume every time she watched (yet even as she did so she didn’t think she had a hearing problem!) After getting a new television, she was fi nally happy she could hear the TV, but not so happy to have to buy a new one.
I then related a story to her about a patient who had come in to get her hearing tested at the insistence of her son. It was obvious just by talking to her that she had significant hearing loss, but she denied having any problem with her hearing. After a comprehensive hearing
is is just one example of something being damaged because of untreated hearing loss. In addition to blown speakers, I have also witnessed countless relationships that have been damaged due to miscommunication that could have been avoided by using hearing aids. I have also seen the physical and mental destruction of cognitive decline and dementia related to untreated hearing loss. Treating hearing loss helps. Treating it sooner rather than later is most effective and minimizes long term damage.
by: Jen Roberts - Edward Jones
Everyone needs an emergency fund. Financial experts recommend it, and we’ve all experienced surprise expenses: a costly car repair, a broken water heater or unexpected medical bills. Despite our best intentions, building a financial cushion can feel impossible. After rent or mortgage, groceries, utilities and everyday expenses, it seems there’s nothing left to save.
If this sounds familiar, you’re not alone. Many Americans struggle to maintain emergency savings. But building those savings doesn’t necessarily require massive lifestyle changes or windfalls. With a strategic approach and realistic milestones, you can create the financial safety net you need.
Start small and build momentum. Traditional advice suggests saving three to six months of total expenses. It’s excellent goal but can feel overwhelming when you’re starting from zero.
Instead, begin with a more achievable target, such as $500 or a full month’s worth of expenses. The key is to get started and contribute consistently.
Even a few hundred dollars can provide meaningful protection and help you avoid relying on credit cards or high‑interest loans. This initial milestone can cover many medium sized emergencies. Once you reach the first milestone, work toward one and a half to two months of expenses, then the full three to six months.
Find money you didn’t know you had. Building your emergency fund doesn’t always require cutting expenses. If you’re employed, set up automatic transfers from your paycheck into a separate savings account. Cancel subscriptions you rarely use, shop around for better insurance rates and take advantage of sales whenever you can.
Consider saving windfalls like tax refunds, work bonuses or birthday money. If your budgeted expenses come in lower than expected — perhaps your health care costs or home maintenance needs were less than anticipated this month — save the difference in your emergency fund.
Have a dedicated account for your fund. Keep your emergency savings in a separate account from your regular checking, so you’re less tempted to use the money for non emergencies. Choose an account that’s easily accessible and without penalties and, while you shouldn’t invest emergency money in stocks or bonds, look for an account that earns interest.

Balance competing priorities. Building an emergency fund is important, but it shouldn’t come at the expense of other crucial financial goals. If you’re carrying high interest debt or missing out on your employer’s retirement contribution matches, address those priorities first, while still building your emergency savings.
Ultimately, you’ll want to balance your emergency fund with other goals. To determine an emergency savings target, consider your personal risk for unexpected expenses, your job security and family circumstances. You may need three to six months’ worth of savings, or possibly some other amount. If this step feels overwhelming, ask a financial advisor to help you come up with a suitable plan.
The path to financial security requires progress rather than perfection. Begin where you are, use what you have and take one small step at a time. That first $500 might feel modest, but it represents the freedom to handle whatever life throws your way.
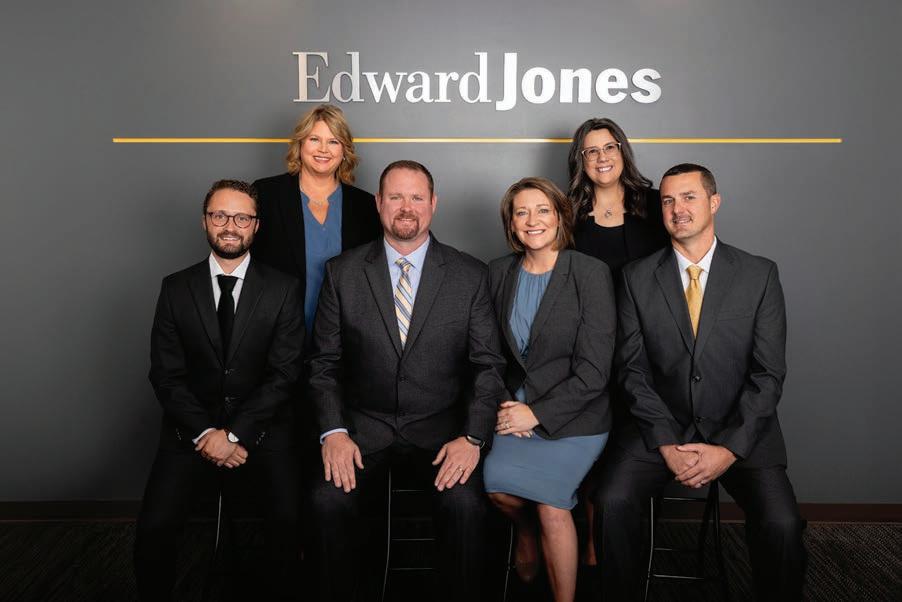
What matters most to you matters to us.
We’ll help you identify and define your unique financial goals. And then we’ll tailor investment strategies that help you work toward those goals.
What matters most to you matters to us.
We’ll help you identify and define your unique financial goals. And then we’ll tailor investment strategies that help you work toward those goals.
Our single focus is helping you achieve what’s most important to you. And you’ll be backed by our entire team each step of the way.
Our single focus is helping you achieve what’s most important to you. And you’ll be backed by our entire team each step of the way. Jen
21 N 1st Ave Suite 290 Brighton, CO 80601 303-659-2301

Offered by: Headwaters Health and Wealth LLC - Lisa Asmussen
Retirement brings more freedom—but it also brings a surprising number of decisions. Between Medicare, taxes, insurance, and retirement accounts, it can be hard to know where to start.
One of the simplest ways to stay organized during your first year of retirement is to make a few important phone calls. ese quick annual check-ins can help prevent expensive surprises later.
1. Your Medicare Advisor - Many people don’t realize Medicare Supplement plans can be reviewed and shopped any time of year. e months outside the busy fall enrollment season are often a great time to check for potential premium savings while keeping the same standardized coverage. It’s also wise to review your prescription drug coverage at the same time, especially if medications have changed.
2. Your Tax Advisor Retirement - often changes how income is taxed. Social Security, retirement withdrawals, pensions, and required minimum distributions can all affect your tax situation. A quick conversation can help prevent surprises when tax season arrives.
3. Your County Tax Office - Homeowners in Adams and Weld Counties may qualify for senior property tax relief or exemptions. Many retirees don’t realize these programs exist, and a short call could lead to meaningful savings.
4. Your Retirement or Financial Advisor - During your working years the focus is on building savings. In retirement, the strategy shifts to turning that nest egg into steady income that can keep up with inflation while limiting risk.
5. Your Insurance Agent - Retirement often changes daily routines. You may be driving less, traveling more, or spending more time at home. A quick review of your home and auto policies can sometimes uncover discounts or improved coverage. Retirement should feel simpler, not more complicated. A few thoughtful phone calls early on can help make sure your healthcare, finances, and insurance are working together the way they should.
ose small conversations today can help prevent big surprises tomorrow—and help you enjoy retirement with more confidence.




Offered by:
I write a lot about Medicare when it comes to being of retirement age. Every once in a while I like to check in with those of you who might actually be on Medicare due to a Disability.
ere are a few different scenarios with Medicare for people who qualify for Social Security Disability. e first is the most broad. In this category, anyone who is entitled to monthly Social Security or Railroad Retirement Board benefits on the basis of disability is automatically entitled to Medicare after receiving disability benefits for 24 months. People who are automatically enrolled in Medicare may keep or refuse Part B coverage. In most cases, if someone does not enroll in Part B when first eligible, they will have to pay a lifetime late enrollment penalty on the Part B monthly premium once enrolled
Heads up: Rules are different for disabled federal, state and local government employees who are not eligible for monthly Social Security or RRB benefits.
Individuals whose disability is ALS, are entitled to Medicare the 1st month they are entitled to Social Security or RRB disability cash benefits. ere is no waiting period.
SSA rules do not allow for child disability benefits to begin earlier than age 18. erefore, Part A entitlement can never begin before the month the person attains age 20 (or age 18 if the individual’s disability is ALS).
Another category is for those with End-Stage Renal Disease (ESRD). Individuals are eligible for premium-free Part A if they receive regular dialysis treatments or a kidney transplant, have filed an application for Medicare, and meet one of the conditions outlined in the link at the end of this article. ere are also different time frames for when Medicare coverage will start from the 1st month of transplant to the 3rd month of dialysis. (See link) Please note, when diagnosed with ESRD, you must apply for Medicare.
If you are on Medicare due to Disability and covered on an Employer Group Health plan, pay close attention to the rules. If the Employer has less than 100 employees, Medicare is Primary Payer and you must have Part A and B for the Employer Coverage to pay properly.
ere is A LOT of information and fine print not included in this small article about becoming eligible for Medicare Parts A and B. Here are a couple links for full details:
https://www.cms.gov/medicare/enrollment-renewal/original-part-a-b https://www.ssa.gov/disabilityresearch/wi/medicare.htm
Because this becomes overwhelming, please reach out. I am always happy to help answer your questions. 720-665-6015 call or text to schedule a time to chat.
www.JenniferBellBenefits.com






Senior Advisory Board
The purpose of the Advisory Board is to advise and assist in the needs and operations of SCAAC. The Board meets Tues. Apr 21 at 1:00 p.m. Members are: Peggy Jarrett, Lou Ellen Bromley, Dan Buckner, Karen Swaithes, Steve Yarish, Bill Alsdorf, Heidi Storz, Gayle Shibao, Barbara Spakoski, Janet Olivieri, Randy Thornton, and Dennis Gibbons. Visitors are welcome.
Charitable Contributions
Together we can continue to enhance the great programs and services offered for seniors and active adults in the Brighton area. Your financial support will be recognized on the donor wall at Eagle View. All donations are tax deductible. Make donations payable to: Brighton United Senior Citizens, 1150 Prairie Center Parkway, Brighton, CO 80601.
Donor Opportunities for Wall Recognition:
Friend: $100 - $499
Memorial: $100+
Sponsor: $500 - $999
Benefactor: $1000+
Do you need help and are unsure where to turn? Evon Benitez will assist you with completing forms and finding needed services. You’ll need to make an appointment to see Evon as she’s often meeting with others. To make an appointment, call Evon at 303-6552079. Leave a message.
Grumpy Old Men!
Drop in Friday mornings for coffee and conversation about life as an old guy relationships, health, money, cars, and what’s going on in the world. Facilitated by Don O’Malley, former counselor and fan of Hank Williams Sr., Tony Bennett, and Led Zeppelin. Fridays - 8:00 a.m.
Free Continuing Your Journey with Diabetes
Learn about the progression of diabetes, potential long-term complications, and why blood glucose may become harder to manage over time. This program focuses on staying within target ranges, understanding your ABCs, and reducing the risk of complications.
Presenter: Maritza Orozco-Reyes, Adams County Health Department.
Thurs. Apr 9 - 1:00 - 3:00 p.m.
Free Deadline: Tues. Apr 7
1150 Prairie Center Parkway, Brighton, CO 80601
303-655-2075 I evacinfo@brightonco.gov www.brightonco.gov
Hours: Monday - Friday 8:00 a.m. - 4:00 p.m.
A hot, nutritious lunch is provided by Volunteers of America, Mondays and Thursdays at 11:30 a.m. Please reserve your meal in advance. For Mondays, reserve the Thursday before; for Thursdays, reserve the Monday before. Call Eleanor at 303-655-2271 between 10:00 a.m. - 2:00 p.m. Mon. & Thurs. to make a reservation.
Daily meal donations are appreciated.
$2.50 Donation per meal if age 60+
$8.50 Mandatory charge if under 60
Basic medical equipment is available to loan out. Items may include wheelchairs, front wheel and seated walkers, canes, crutches, toilet seat risers, commodes, and bath benches. There is no guarantee what will be available at any time. Call 303-655-2075 for information.
The Clinic focuses on health promotion and disease prevention for seniors 55+. Operated by Visiting Nurses Association (VNA), services include foot care, health checks, and blood pressure checks. The fee for foot care is $40 payable at the time of your appointment. Foot care may be Kaiser covered with pre-approval. Reduced fee available upon approval. Masks required for everyone. Call 303-655-2075 for appointment. Clinic hours: 9:00 a.m. - 2:30 p.m.
Fridays: Apr 3, 10, 17
Monday: Apr 13, 27
Friday Feast
A fan favorite returns! Join us this month as musician
Dan Kenny takes the stage for another great performance. Enjoy a delicious meal featuring baked spaghetti, salad, chips, and a cookie.
Fri. Apr 10 - 12:00 noon
$8.00
Deadline: Wed. Apr 8
Feathered Friends: Gyrfalcon
Joining us this month is the largest species of falcon in the world, the gyrfalcon. This arctic bird is a rare visitor to Colorado and perfectly at home on the snowy tundra, and the wild, rocky shores of far northern countries such as Iceland, Canada, Norway, and the state of Alaska.
REF’s gyrfalcon is the rarest color, the black morph native to the Labrador cliffs of Canada.
Tues. Apr 14 - 1:00 p.m.
$5.00
Deadline: Fri. Apr 10
Active Minds: UNESCO World Heritage Sites
SCAAC & Zoom
Established in 1945, the United Nations Educational, Scientific and Cultural Organization (UNESCO) is a specialized agency within the UN with a mission to promote peace through education. As part of that
Need help with your laptop, tablet, or smartphone? We will do our best to help you become more comfortable using your device. Schedule an appointment with Calvin at 303-655-2187.
Feel great with a massage by our certified therapist, Laurie Lozano Maier. She has over 12 years of massage therapy experience. Call 303-655-2075 to make a onehour appointment. Pay Laurie at the time of service - check or cash.
Tuesdays and Wednesdays $60 for 1 hour
Deadline: Two days ahead
Via Mobility - provides specialized transportation within the City of Brighton. Via can take you to medical appointments, grocery shopping, and Eagle View, to name just a few of the places you can go in Brighton. New Via users - call 303-447-2848 ext. 1014 to get started. To schedule rides, call 303-447-9636. Free rides to and from Eagle View to seniors living in the Brighton Via service area are provided by funding from the Senior Advisory Board.
This is an RTD service. Call 303-299-6000 for reservations. The driver will pick up and deliver you anywhere within Brighton, Mon - Fri. 6:00 a.m.7:00 p.m. Cost is the local RTD bus fare.
mission, UNESCO oversees the selection and legal protection of World Heritage Sites, locales judged to “be of outstanding value to humanity.” Join Active Minds as we trace the origin and extension of World Heritage Sites and take a tour of a few highlights.
Wed. Apr 15 - 1:30 p.m.
$5.00
Deadline: Tues. Apr 14
Parkinson’s Support Groups
Drop in and connect with Parkinson’s Association of the Rockies for a welcoming, supportive community. Wednesdays are for individuals living with Parkinson’s and their care partners; Thursdays focus on care partners and loved ones sharing resources and support.
Wed. Apr 15 - 2:00 - 3:30 p.m.
Individuals with Parkinson’s Thurs. Apr 16 - 2:00 - 3:30 p.m.
Care Partners and Loved Ones
Free
Roosevelt vs. Lindbergh
SCAAC & Zoom
Whether or not America was going to join the British fight against Nazi Germany in 1940-41 was the question
[Continued on page 35]
[EAGLEVIEW Continued from page 34]
that captured national attention. President FDR said, “England is fighting our fight” while celebrity navigator Charles Lindbergh argued that the country should keep out of the European War. Presenter: Paul Flanders.
Thurs. Apr 16 - 1:30 p.m.
$5.00
Deadline: Tues. Apr 14
Northern Ireland
Northern Ireland isn’t just a region in Ireland - it’s an entirely different country. Although the two nations share an island and language, they differ culturally, religiously, and politically. Today we’re off to see the stunning Giant’s Causeway on the Antrim Coast and stop in Belfast to explore the Titanic Museum and remember the lives lost on the 114th anniversary of the Titanic’s sinking. Presented by Travels with Toni.
Fri. Apr 17 - 1:30 p.m.
$5.00
Deadline: Wed. Apr 15
Soil 101
Ever wonder what’s really going on in your soil and what it takes to grow a healthy landscape in Colorado? In this informative class, a CSU Master Gardener will explain why our soils can be challenging and how, with the right practices, they can thrive. Topics include Colorado soil types, proper amendments, and effective watering techniques to help your landscape perform at its best.
Wed. Apr 22 -1:30 p.m.
$5.00
Deadline: Mon. Apr 20
Answering Your Real Estate Questions
Linda Jones, Five Star Professional Realtor, and Connie Oller, Certified Mortgage Planning Specialist will discuss and answer your questions about real estate. Thurs. Apr 23 - 1:30 p.m.
Free
Deadline: Tues. Apr 21
Let Them Eat Cake
“On the eighth day God created whiskey to keep the Irish from taking over the world.” This is a whiskeysoaked cake that Toni simply could not stop devouring on her trip to Northern Ireland. Staying at the cozy Glenn Eireann B & B on the Antrim Coast, our hostess baked this scrumptious dessert - and gave me the recipe! Sláinte! (Cheers!). Instructor: Travels with Toni. Fri. Apr 24 - 10:30 - 11:30 a.m.
$21
Deadline: Fri. Apr 17
Learn how to earn gift cards and cash just by scanning your shopping receipts in this popular workshop on the Fetch Rewards app. We’ll cover how to download the app, scan receipts, earn bonus points,and redeem
rewards like Amazon, Visa, or Starbucks gift cards. Presented by Derek Taniguchi from Rescue Geek. Fri. Apr 24 - 1:30 p.m.
$5.00
Deadline: Wed. Apr 22
Retirement Investment Roadmap
This seminar will cover the types of investments available at Edward Jones. There will be a Q&A afterwards to discuss investments and how they can be used for retirement-aged investors. Presented by Forrest Hough, Financial Advisor.
1:30 p.m. Mon. Apr 27
$5.00
Deadline: Thurs. Apr 23
Movie: The Thursday Murder Club
Four retirees spend their time solving cold case murders for fun, but their casual sleuthing takes a thrilling turn when they find themselves with a real whodunit on their hands.
PG-13. 1 hr/58 min. Free, but please register. Thurs. Apr 30 - 1:15 p.m.
Deadline: Wed. Apr 29
Sudoku is one of the most popular puzzle games of all time. As a logic puzzle, Sudoku is also an excellent brain game. If you play Sudoku daily, you will soon start to see improvements in your concentration and overall brain power. Start a game today and make it a part of your daily brain workout!
The goal of Sudoku is to fill in a 9×9 grid with digits so that each column, row, and 3×3 section contain the numbers between 1 to 9. At the beginning of the game, the 9×9 grid will have some of the squares filled in. Your job is to use logic to fill in the missing digits and complete the grid. Don’t forget, a move is incorrect if:
• Any row contains more than one of the same number from 1 to 9
• Any 3×3 grid contains more than one of the same number from 1 to 9
• Any column contains more than one of the same number from 1 to 9
1
Offered by: Scott and Lora Nordby, Berkshire Hathaway HomeServices Colorado Real Estate
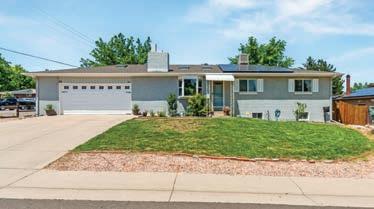
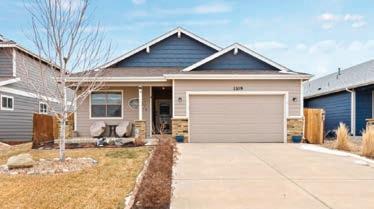
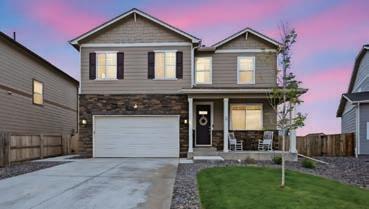
Ifyou’ve been waiting for a “reset” in the housing market, you aren’t alone. For many Coloradans, the last few years have felt like a whirlwind. Between fluctuating interest rates, rising property taxes, and the ever-increasing cost of homeowners insurance, the question on everyone’s mind is: “Will 2026 finally be the year home prices come back down to earth?”
e Reality of “Reversion to the Mean”
To understand where we are going, we have to look at where we’ve been. Between early 2020 and 2025, home values appreciated at nearly double their historical average—climbing roughly 9% annually compared to the traditional 4%. In economics, there is a principle called reversion to the mean. Simply put, when an asset experiences extraordinary growth, it eventually returns to its long-term average.
While we may not see a dramatic “crash,” we are seeing a significant “cooling.” Nationally, home price growth has slowed to under 1% year-over-year, and Colorado is following a similar path toward a more balanced, sustainable pace.
For the first time in years, the data suggests the “seller’s sprint” is transitioning into a steadier marathon. Several key indicators point to more breathing room for buyers:
• Growing Inventory: Unsold inventory is at its highest level since the spring of 2020. More homes on the market mean more choices and less pressure to waive inspections or overpay.
• Longer Days on Market: e median time a property sits on the market has increased. is “extra time” allows buyers to be more intentional and gives them more leverage during negotiations.
• e Affordability Gap: While wages grew by roughly 4.2% over the last year, they are still playing catch-up with the 49% surge in home prices seen since 2019. is has led many buyers to be more selective, causing sellers to be more realistic with their asking prices.
It’s important to remember that a home’s “affordability” isn’t just about the sticker price. Buyers today are navigating a “four-headed monster” of monthly costs:
1. Mortgage Rates: While rates are projected to settle into the low 6% range by late 2026, they remain the largest factor in monthly payments.
2. Property Taxes: Assessments have risen alongside home values, adding hundreds of dollars to monthly escrow accounts.
3. Insurance Premiums: Driven by labor costs and climate factors, insurance rates are projected to continue their upward trend through the end of the year.
4. Mortgage Insurance: For those putting down less than 20%, PMI and MIP remain a necessary—but added—expense.
e evidence is mounting: sales are slowing, inventory is building, and price reductions are becoming more common. While we may not see a universal drop in prices, the market is undoubtedly tilting back toward a healthy balance. For Colorado buyers, 2026 offers something we haven’t seen in a long time: leverage With more inventory and the potential for easing rates, the “musical chairs” of homeownership is finally slowing down, allowing you to find the right seat at the right price.
Navigating a shifting market requires more than just data—it requires a trusted partner who can turn that information into a winning strategy. Whether you are looking to capitalize on rising inventory as a buyer or need to position your home accurately in a competitive landscape, a Forever Agent SM at Berkshire Hathaway HomeServices Colorado Real Estate is here to provide the expertise and confidence you deserve. We are committed to your long-term success, offering guidance that extends far beyond a single transaction. Connect with us today at 303-905-8850 or visit BHHScoloradorealestate.com to start your next chapter with a partner you can trust.