
When the virus brought much of the world to a standstill, it was only natural that we thought that life would be radically and permanently altered but realistically, the world post-pandemic is unlikely to be that different from the one we knew before. So what will be COVID-19’s lasting impact? In this issue, we’re exploring some of the industries that may well have changed for good, from fashion (p.08) to cities’ prioritising pedestrians (p.30).
Some longer-term trends were accelerated by the pandemic. We became more reliant on digital services than ever in lockdown and it’s something that the industry noted. Islamic financial products and institutions are cropping all over the world (p.45) and many are using blockchain and fintech to revolutionise the way they do business (p.45). Taipei Fubon Bank has launched Taiwan’s first blockchain interbank transfer sandbox experiment (p.38).
Meanwhile, with a third of the world’s wealth under their control, women have become a sizable economic force. We spoke to Boston Consulting Group’s Anna Zakrzewski about managing the next decade of women’s wealth (p.40).
It would seem there is certainly a lot to be (cautiously) optimistic about and the recent global stock market gains are proof that many investors see a brighter economic future (p.22). If you know an organisation or individual who are working to make that future a reality and you think they deserve to be recognised, nominate them for an award!
Enjoy,
Sophie Rasbash
08
The Perfect Fit for Sustainability
An interview with Jess Fleischer, cofounder of innovative clothing tech company, Son of a Tailor.
16 Re-shaping the PostPandemic Future
How can business leaders build back better?
22 Investing in Optimism
After a turbulent few months, global stock markets are looking more positive.
26 Putting the investor first
Banner Asset Management is an experienced asset and funds manager, specialised in the Australian real estate market.
30
Travelling clean postpandemic
COVID-19 will have a lasting impact on the way we travel. How will cities and public transport respond?
38
Transforming the Customer Experience
Taipei Fubon Bank is using cuttingedge technology to deliver a better banking experience.
40
Managing the Next Decade of Women’s Wealth
An interview with Anna Zakrzewski, a Managing Director & Partner of Boston Consulting Group.
45 Boosting the Islamic Finance Sector with Blockchain
Both the Middle East and Southeast Asia are home to a growing number of Islamic fintechs.
48 What’s up with Swiss private banks?
An update from Jan Langlo, Director of the Association of Swiss Private Banks. 40
52 Collaboration for innovation
Innovation has been at the heart of Arca Fondi’s business model since its beginning. 54
Net-zero: Combining public and private investment
How can the UK deliver on its net-zero ambitions?
64
Over a decade of sustainability
Over a decade into their sustainability journey, Access Bank have aligned their corporate philosophy and sustainability strategy
71 Local Innovation, Global Recognition
Cornèr Bank (Overseas) Ltd’s product innovation and overall client satisfaction set the pace for financial services worldwide.
We celebrate the organisations innovating and driving the world of Investment!
74 The Rise of RoboAdvisors
The growing robo-advisor trend marks a shift in how business is done.











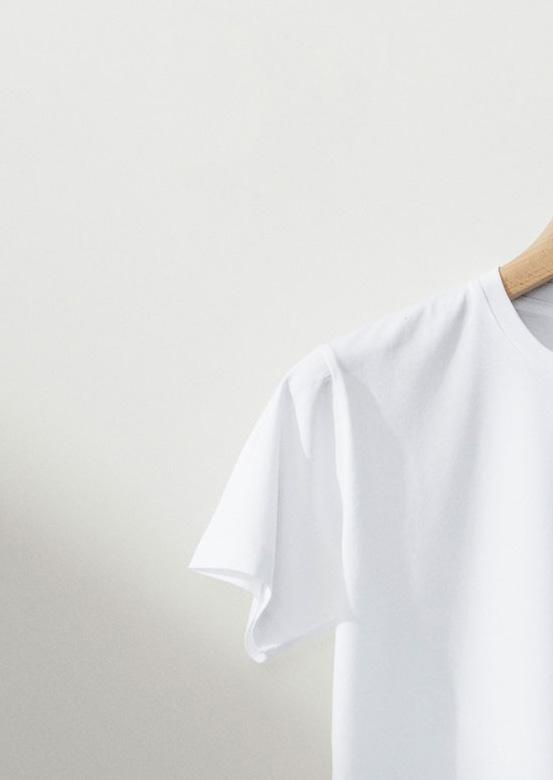
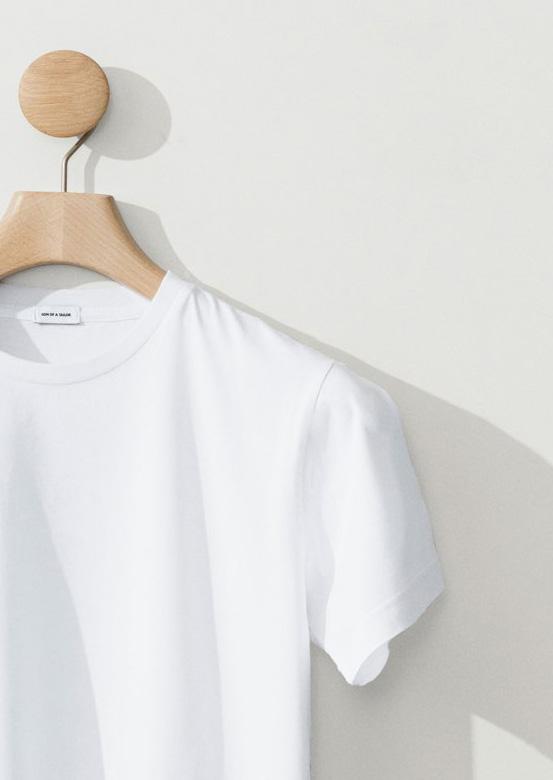
While we know that the majority of textiles end up in landfills, two Danish fashion entrepreneurs, Andreas Langhorn and Jess Fleischer, are tackling the problem of material waste upstream at the manufacturing stage. They developed an algorithm that creates a T-shirt tailored to your exact specifications. The result is Son of a Tailor, a clothing tech company with its sights now set on producing the world’s first 3D-knitted pullover. We spoke with co-founder, Jess Fleischer, about how they got started and what COVID-19 means for the fashion industry.
INSTEAD OF SEEING THE PURSUIT OF SUSTAINABILITY AS A BARRIER, SON OF A TAILOR CHOOSES TO SEE IT AS INSPIRATION FOR INNOVATION. WHAT KICKSTARTED YOUR REINVENTION OF TRADITIONAL PRODUCTION METHODS?
Jess Fleischer: Two things. First, I saw the need as a buyer of T-shirts. I was asking myself: why is it that the apparel item closest to your body did not come in more than five or six sizes? And then secondly, I had studied and worked intensely with manufacturing lines and supply chains and seen how things like customisation, technology and just-in-time mindsets had changed industries - except in fashion - here companies still mass-produced like we did 100 years ago and in an extremely unsustainable way.
HOW DID YOU GO ABOUT BUILDING AND TESTING YOUR IDEAL SIZE ALGORITHM?
I don’t really know. It was one of those magic start-up epiphanies. We were annoyed how much trouble customers had measuring themselves with a measuring tape. So we started acquiring torso measurement data and after a month, our Lead Developer, Jakob, suddenly said, “I think I am on to something”. He had found some initial unique relationships in the data. After six months of iterating with our customers, we had an algorithm that worked better than manual measurements. Today you just need to fill in your height, weight, age, and shoe size - for 96% of our customers, that provides a great fit.
THE SUCCESS OF THE KICKSTARTER THAT HELPED LAUNCH SON OF A TAILOR PROVES THAT PEOPLE ARE READY TO INVEST IN SUSTAINABLE CLOTHING. HOW DO YOU SEE THE FASHION SECTOR TRANSFORMING TO MEET CUSTOMER EXPECTATIONS?
The customer has come a long way in the last couple of years in terms of sustainability and they are demanding a change. We can actually see it in our marketing and customer support data! Unfortunately, the sector is not changing very quickly. Most brands still think that if they have sustainable cotton in some of their collections, they are fine. It’s sad.
HOW HAS COVID-19 CHANGED THAT? WHAT WILL BE ITS IMPACT ON THE FASHION INDUSTRY?
In relation to COVID-19, traditional fashion brands have experienced sudden changes in demand, many with a steep decline. This is painful for any business as there are fixed costs that need to be covered. But for fashion companies, it hurts all the more because they will have a ton of money bound in inventory that’s season-dependent. This is really bad for both their economy and the environment, as a lot of resources go into producing this inventory.
Considering that many of these companies have already had problems with overproduction, their rule of thumb is often “we better produce one item too many, than one item too few”. This leads to large amounts of resources going to waste, negatively affecting the environment.
COVID-19 has been a wake-up call for many of the big brands. This inventory insanity needs to stop. In 2018, H&M needed to liquidate $4 billion worth of stock - and that was in a year of economic growth! Supply chains have become too long and the topline growth targets too greedy. Still, many brands order their apparel more than six months before they will sell them. And they would commit to fabric long before that.
Besides that, there are substantial doubts about whether classic offline retail will ever go back to pre-pandemic levels. Many studies indicate that this won’t be the case, so fashion brands will be forced to provide a better online service, including better representation of their products, better sizing options and a much better understanding and service of the online customer. Take Hugo Boss and Ralph Lauren for example. Both have Trustpilot Scores of 1.9/5 - and they don’t even seem to care.
Consumer fashion has been shifting towards sustainability for quite some time, in the sense that brands are increasingly focusing on essentials that last longer as well as meeting the expectations of people who want to consume less. These are trends that, I am sure, will be further accelerated by COVID-19.
NOW YOU ARE EXPANDING TO JUMPERS AND LONG-SLEEVES. WHAT’S NEXT? DO YOU HAVE A SPECIFIC LONG-TERM VISION OR ANY EXCITING DEVELOPMENTS IN THE PIPELINE YOU CAN SHARE?
Let’s see. The Son of a Tailor product pipeline is not expanding super fast. We want to make sure that every launch is perfect and provides the perfect fit. But there are indeed many subcategories within t-shirts, jumpers and knitwear to come!
Any country heavily engaged in financial services bears a responsibility and commitment to the international community with which it is intricately involved, the financial institutions operating within its borders, the clients it serves and its citizens which rely on the sustainability of the industry for continued economic development. The Bahamas is such a country.
The Bahamas has always sought to provide superior financial products and services and a world-class client experience. It has proven itself to be nimble and responsive to global changes – always mindful of the need to adhere to international standards with respect to compliance, cooperation and transparency. This is complemented by the fact that The Bahamas is not only somewhere that offers bespoke private wealth management, it is also a beautiful place to live and work.
The Bahamas is the leading international financial centre in the Latin America and Caribbean region, respected for its expertise in fiduciary services.
The financial services sector has been impressively resilient and progressive in the face events such as hurricane Dorian, the current COVID-19 pandemic, international initiatives, and in midst of the continued and sometimes challenging evolution of the global industry.
None of these challenges has impeded the country’s financial services industry from conducting business and delivering bespoke solutions to meet changing and diverse client needs. Robust business continuity plans that are in place with all financial institutions have allowed business to continue both during hurricane Dorian last autumn and now as the world deals with COVID-19. The foresight evidenced by vigorous business continuity measures has clearly worked to cushion the implications of these events and reinforces why the country is seen by many as an ideal location for financial institutions and the services they provide to their international client base. This adaptability has been especially evident in the Bahamas’ response to international initiatives, which has ensured adherence with the highest standards of compliance with every internationally agreed standard of conduct.
The vital features at the heart of what distinguishes The Bahamas as an international financial centre of significance are: expertise, innovation and Location.
everything The bahamas offers is defined by these three words. Everything that comprises The Bahamas’ value proposition and continued success as a leading international financial services centre is guided by these distinguishing factors.
With a track record spanning more than 80 years in financial services, few jurisdictions offer the wealth management experience that The Bahamas has to offer. This heritage is the basis for the strong legal framework that has been cultivated for financial services, an investment climate that has been nurtured through years of maturity, and a stable and predictable business environment, anchored by the thousands of Bahamian wealth management professionals who work side-by-side with expatriate colleagues in the more than 250 financial institutions that call The Bahamas their home.
Market responsiveness has long been a part of The Bahamas’ DNA as a forwardthinking international financial centre and has been the basis of legislation creating innovative, client-centric products and services in a modern, compliant regulatory regime. Such innovation can be seen in the country’s evolving and often groundbreaking trust legislation. It led The bahamas to become the first common law jurisdiction to introduce foundations. It sparked the Bahamas Executive Entity and has thrust The Bahamas to the forefront of the investment funds industry with the introduction of SMART Funds and the Investment Condominium (ICON) fund.
With this innovative spirit, it should come as no surprise that the country’s once-dormant insurance business has re-emerged as a sought-after destination for captives.
The innovation experienced in the sector is fuelled by a progressive investment climate that seeks to place financial services in the context of development.
The unique geographical location of the Bahamas, just 50 miles off the coast of Florida and positioned as the gateway to the wider Americas, is an undeniable advantage for The Bahamas. Its proximity to the U.S., Central and South America places The Bahamas in an enviable position to serve both traditional and emerging markets and presents an opportunity to link commercial and financial interests.
In recent years, as more and more individuals have chosen to “follow their money” with respect to where they live and work, The Bahamas, with its tropical environment, has become the preferred choice for many who yearn for an excellent quality of life whilst being able to manage their financial affairs. Most importantly, individuals, family offices and institutions will find a warm welcome when they come to The Bahamas as the country is committed to using its natural resources and cultivated assets to create an environment that is attractive in terms of both business and leisure. Few competitive jurisdictions can offer the business and lifestyle combination The Bahamas provides naturally. Moreover, the strong regulatory regime that characterises the jurisdiction’s financial
services sector ensures that the integrity of The Bahamas as an international financial centre is maintained.
As a sovereign nation for more than 40 years, successive governments have consistently demonstrated the country’s commitment to international best practices, cooperation in the administration of justice, international tax transparency, anti-money laundering and the countering of financial terrorism initiatives.
Expertise, innovation and location are the pillars of financial services in The Bahamas. Combined, they form a compelling reason to consider The Bahamas as the place to do business and will continue to guide the jurisdiction’s pathway to be a provider of unparalleled financial products and client experience.
220m
Actively Managed certificates currently oustanding
An Institutional team created in 2014, grew from 2 to 6 highly qualified people, with diversified backgrounds, each in their own field, from trading to sales, from legal to operations.
offer a flexible and integrated trading setup in a one-stop shop
Structure products and bespoke solutions for all asset classes
Distribution and access to established network of institutional clients
1.3bn
Raised from institutional clients globally
70
Structured products sponsored in 3 years
Innovative and highly technological business leveraging on a solid and fully diversified network of institutional clients
Constant growth due to a sustainable business model and a flexible onestop shop approach
by Andia Rispah
COVID-19 is more than a health crisis of immense proportion, it’s a catalyst for an imminent restructuring of the global economic order.
It offers individuals and organisations a chance to reset and re-shape the world towards sustainability. here’s how business leaders can hasten this vital transition.
The COVID-19 pandemic has disrupted the global health and development community. The world’s attention has shifted to organisations fighting infectious diseases, health workers, delivery of social services, and protecting livelihoods.
however, this kind of work is complicated by challenges in terms of accessibility, supply chain logistics, safety, and financial stress. Every country has had to struggle with a lack of equipment and supplies to test and protect against COVID-19.
So how will the pandemic re-shape health and development institutions, priorities, and occupations? Every country will have to re-examine their supply chains for critical health and livelihood related products. There will likely be a surge in producing pharmaceuticals, equipment, and medical supplies locally. Countries without the existing capacity will want to develop the tools needed as soon as possible.
More countries will invest in research, therapeutics, vaccines, and nonmedical methods of prevention.
This could mean preventing deaths, economic losses, and livelihoods for millions of poor people around the world.
The COVID-19 pandemic has hit investment and global trade at an unprecedented speed and scale. Multinational companies faced an initial supply shock and later a demand shock as more countries ordered people to stay at home. Individual consumers, businesses, and governments struggled to procure the necessary materials and products.
The healthcare sector’s scramble for protective equipment laid bare the inherent risks of inventory and singlesourcing models driven exclusively by cost control. As Chinese factories were closing down, manufacturers struggled due to a lack of flexibility in their supply base.
It forced every country to confront the fragility of the modern supply chain. To reflect on its dependence on the rest of the world to maintain its way of living.
Now countries have the opportunity to design stronger, smarter, and more diverse supply chains.
Some will want to decentralise their manufacturing capacity and consider local production. Policymakers also have an opportunity to consider whether certain products need local or regional manufacturing.
Western countries relied on off-shore supplies for necessities, but now they can see the downside. Governments will certainly revise domestic manufacturing as part of their plan to build up strategic resilience after the current crisis.
Automation will be a crucial component in reviving domestic manufacturing. Advanced automation and robotics will drastically increase productivity in manufacturing processes. Automated manufacturing will replace low-skilled labour with new jobs and opportunities for digitally savvy workers.
The pandemic has made accessibility to reliable, real-time data an absolute necessity, especially when it comes to coordinating the right medical response. Data will become a more strategic resource across multiple facets of business and community.
This requires a significant investment in data connectivity, acceleration in developing the 5G networks and push for valuable insights into leading economic indicators. It means the manufacturing sector will significantly accelerate the deployment of industrial IoT. Such advancements include sensing, data visualisation, remote collaboration tools, and AI-based insights across their operations.
Data is a strategic asset to companies and a key factor in their competitive advantage.
After the Great Recession, McKinsey analysed the performance of publicly traded companies and found that only 10% were more resilient to the crisis than their peers.
The resilient companies had created financial and operational flexibility, cut costs, and built a growth foundation to capture market opportunities after the crisis.
They had invested in software technologies, which gave them greater predictability and efficiency - giving them a competitive edge. Recent advances in AI and IoT technologies have enabled tremendous efficiencies in predictability, capacity, availability, and flexibility of supply chain and manufacturing operations. Digitisation is a fundamental element for building sturdy chains. It makes the identification and recruitment of new suppliers far less time-consuming.
McKinsey found that companies that embraced these technologies earlier were already seeing a 7% growth in revenue over their peers.
COVID-19 has caused an economic and social downturn, but it will create a much deeper divide between companies who have just started to digitise and those further along in their digital journey.
Manufacturers still require people to work physically on-site; operators to run machines, and maintenance staff to repair and maintain them. Contactors and external vendors need to access the site to support operations. however, social distancing measures could render nearly 50% of on-site staff jobless.
Even as manufacturers face this dilemma, we will see the rapid adoption of remote diagnostic, collaboration, and management tools. It will lead to the emergence of a “virtual shift.” We’ll have a team of experts working remotely, guiding, and supporting the reduced “physical shift” of on-site personnel.
The threat of climate change has been gradually growing, with devastating effects for people and their livelihoods around the world. The COVID-19 crisis presents an opportunity to learn the lessons and reset ourselves on a more sustainable path and a new trajectory of sustainable employment.
It has emphasised the importance of investing in areas such as technology and innovation.
It is time to align sustainable solutions with funding in a way that can transform the marketplace.
Sustainable investment will boost economic growth and employment opportunities.
This pandemic has served to highlight that the world’s most vulnerable citizens suffer the most during times of global crises.
To repair lives after the pandemic requires billions of dollars to rebuild industries, supply chains, and create conditions for a resilient financial future. however, the global response to the COVID-19 outbreak also mirrors the approach that IFC uses to manage the climate crisis: that businesses, investors, and financial institutions must lead the way to a new, more sustainable economic model.
As the pandemic re-shapes the global financial system, and as companies evaluate their diminishing returns, investing in climate-friendly strategies could boost economic growth and create new jobs.
Most importantly, companies must place sustainability at the heart of their business and investment strategies to avoid the pitfalls of a business-as-usual high-carbon path. It’s a business plan that’s positive for the environment and good for people and profitability.
businesses should redirect finances into assets and investments that deliver concrete and measurable outcomes to rebuild economies to be more sustainable and resilient.
for innovation and sustainable finance to flourish, the private sector must make the most of these opportunities.
From history, we learn that a global crisis creates a fundamental shift that affects consumer behaviour, government policies, and behavioural sectors for years to come.
Countries must understand which part of their social, business, and political environment will change after the COVID-19 pandemic and invest accordingly to prepare for the new normal.
At the start of the COVID-19 crisis, stocks around the world were plummeting as people feared how the disease might impact the global economy. A few months on and millions of people are out of a job and businesses in the hardest-hit industries such as tourism and hospitality are struggling to survive. But in recent weeks, the stock market has been surprisingly positive. Could it be that investors are much more optimistic about the future than scientists?
Wall Street stocks rose sharply in early July, as bullish sentiment in China boosted investors’ optimism in markets around the world for a recovery from the coronavirus pandemic. Although the market is not currently at the record highs it was in midFebruary, it isn’t too far off. The S&P 500 is hovering around where it was last autumn.
“Investors seem to have decided that the past three months were just a bad dream that we’re waking up from,” Scott Clemons, chief investment strategist for private banking at Brown Brothers harriman, told the New York Times.
Following the Independence Day weekend, the S&P 500 rose 1.6% in New York, despite an increase in new COVID-19 cases across the country and roughly 30 million newly unemployed Americans.
The market’s behaviour can be explained in large part by the actions of the Federal Reserve, which has taken unprecedented measures to pump money into the economy and stabilise the markets. Since March, the Federal Reserve has created roughly $2.9 trillion, most of which has gone into financial markets. The federal government has said it would borrow a record-breaking $3 trillion from April to June, to support businesses during the pandemic. Such decisive steps have reassured investors.
Meanwhile, many american first-time investors have taken the plunge during quarantine - perhaps hoping to make the most of low share prices or simply trying to alleviate their boredom. At Charles Schwab, clients opened a record 609 000 new brokerage accounts, with almost half of them created in March alone. Online trading platforms and investment apps have also helped new investors buy into the markets.
Yet political tensions between the United States and China — the world’s two largest economies — remain high, potentially disrupting the American businesses’ recovery plans.
China’s yuan has strengthened to levels last hit in March and chinese financial markets have rallied as confidence builds that the country’s economy is well on its way to recovering from the COVID-19 pandemic.
As Bryce Elder, harry Dempsey, and Daniel Shane point out in the Financial Times, the front page of the state-run China Securities Journal promised investors a healthy bull market and the mainland Chinese stocks jumped accordingly. The CSI 300 index of Shanghai and Shenzhenlisted shares rose to 5.7% on Monday the 6th of June, the biggest daily rise since february last year. it closed at a five-year high, just 13% off its previous peak in June 2015.
These increases are a clear indication that the millions of individual investors are feeling optimistic.
The driving force in China’s equity markets, retail investors have been banking on the technology sector in particular.
Elsewhere in Asia, hong Kong’s hang Seng index added 3.8% to enter a technical bull market, defined as a 20% rise. Japan’s Topix added 1.6% while South Korea’s Kospi rose 1.7%.
In Europe, the regional benchmark Stoxx 600 closed 1.6% higher. London’s FTSE 100 added 2.1%, with financial and mining stocks being particularly bolstered by the wave of Chinese optimism.
In what seems to be a global trend, India has also seen a large number of new retail investors entering the market directly through stock exchanges. Many of these first-time investors are young, looking to invest in their future while protecting their savings. Their arrival on the scene has increased retail participation in the stock market to new heights. Non-institutional investors have increased their share to over a decade’s high of nearly 70%.
Even for investors who remain sceptical of the optimistic recovery predictions, there are plenty of interesting opportunities. Favourable policies in countries around the world - from lowering interest rates and the discount rate, thereby increasing the weight attached to post-pandemic earnings flows, to advantageous stimulus packages - are encouraging huge numbers of people to start investing. It helps that technology has made the markets more accessible than ever before.
The threat of a second wave looms large even before much of the world has recovered from the first. nevertheless, it would seem that the markets have rebounded from the lows of early March but some investors are now content to wait for more substantial proof of a recovery in corporate earnings. If this optimism proves to be unwarranted, a fear response could take over and everyone, not just retail investors, would face huge losses. But for now, many investors are anticipating a V-shaped recovery and are buying accordingly.
THE MANAGER
Banner Asset Management is an experienced asset and funds manager with a specialisation in debt and equity products in the Australian real estate market.
Since 2010, Banner has invested in a range of real estate and development opportunities, primarily in the larger population centres on the east coast of Australia.
Banner was started in 2010 by Andrew Turner, the CEO, and a small group of initial investors and chiefly invested the funds of its principals. It grew organically, to gradually wider circles of associates and their companies, family members and friends.
The range of investors has expanded to institutions, corporates, and other funds. All the original investors remain.
This organic and gradual growth guided and continues to guide the investment principles of ‘putting the investor first’, through responsiveness, preserving capital and earning a return.
Banner initially matched individual investors’ funds with individual projects though the Banner Wholesale Fixed Interest Income Fund. That master fund remains the flagship fund of the group. it has added pooled funds and opportunity funds to its product offering.
Banner is a registered provider of financial products in the highly regulated australian financial services and funds management sector.
It complies with strict legislative requirements, including capital reserves (net tangible assets), process and audit requirements. The head office is in Melbourne, with a sydney office, principals located and active in Japan and Singapore. Its investors are mostly located in Singapore, hong Kong, Japan, Europe and Australia.
The Banner funds have funded property projects valued at over AUD8 billion. A majority of Banner’s investors are nonresidents, and it is well-versed in dealing with the needs of off-shore investors.
The Australian property market has seen a near uninterrupted growth story of 40 years and in this environment property debt, as an alternate asset, has also grown. Where a stable and strongly performing property market is combined with a mismatch in the funding demand/ supply equation, opportunities present themselves to both individual and institutional investors.
Banner Asset Management saw the market dislocation in 2009 and has offered wholesale and professional investors access to the property debt. The mismatch of risk and reward has continued over the past decade due to events such as increased bank regulation, capital requirements, and government actions.
The underlying asset (predominantly residential property) has low volatility, has shown consistent growth over many decades, and has low to negative correlation with the equities market, making it a sound investment strategy and alternate asset.
Australia’s development funding market has been dominated by the big four trading banks. The banks have been reducing exposures to the market since the global financial crisis and that trend has continued since due to Basel III, increased APRA (regulatory) oversight of commercial lending and more recently the Royal Commission into the banks.
The reduced exposure of the major banks to property development has created an opportunity for private lenders to lend at good rates on secure development by very experienced developers -a very good risk and return trade-off.
Banner has nine active wholesale investor funds under management. Returns have been impressive with an average annual return to investors of circa 10% annum for its pooled funds and 10-15% per annum for its single asset funds, over the past decade. Equity, like returns, has been over 20% per annum for its opportunity funds. It also offers some direct property exposures.
‘Preserving capital’ refers to the role of the manager in ensuring that the value of the underlying asset is at least maintained, or improved, during the term of the investment. Preservation of capital value has three stages:
• 1. asset selection
• 2. rigorous processes
3. active on-going asset management
Asset selection relies upon an experienced and capable investment committee. It has members with property, funds management, financial, investment, development and legal backgrounds. and representatives The Banner investment committee considers the financial parameters of the proposal, the sponsors’ experience and commitment (including cash commitment), the project, location, quality of consultants, asset value and proof of proven demand for the end product. It is a complex process and, as asset selection is crucial, Banner adopts a multi-stage investment committee process for each proposal, to test and re-test all assumptions. No proposal is a ‘take it or leave it’ proposition – the investment committee will have a number of requirements which must be satisfied before approval will be considered.
Process is crucial. Each potential asset must be subject to all facets of due diligence and only through a clear and rigid process, will this be ensured.
Banner constantly reviews this process using its lending, risk, and legal expertise.
On-going management must be active, regular and focused. For all its investments, Banner will obtain detailed monthly reports on the use of funds and progress of the construction. Banner investment portfolio managers will also personally attend all project meetings with builders, architects and developers to personally gauge and assess any issues with construction.
All of the above is a daily activity for the manager, backed up by internal risk review to ensure processes are adhered to.
Defined investment criteria is a further part of the Banner risk strategy. Banner’s investments are located in the major population states of New South Wales and Victoria - the depth of the market is important in assessing the risk on a property and its potential for sale. Loan-ToValue (LTV) ratios are maintained at a level that provides some shelter for the fund from property price risk – LTVs averaging under 65% across the portfolio.
Banner does not invest in the large-scale high-density city apartment blocks. It favours smaller, bespoke developments in the inner suburbs with proven demand.
Banner also focuses on staged, land subdivisions in prime locations and growth corridors. All such projects have full recourse pre-sales with cash deposits paid and held by an independent stakeholder.
Banner also invests for terms of 12-24 months on fixed rates with multiple exit strategies. This creates a pool of assets that are frequently maturing, decreases the influence of longer-term cycles, and locks in a rate of return.
Whilst Banner invests across all sectors of the property market, it specialises in the residential market with some industrial and mixed-use properties and non-discretionary retails, such long-term leased supermarkets.
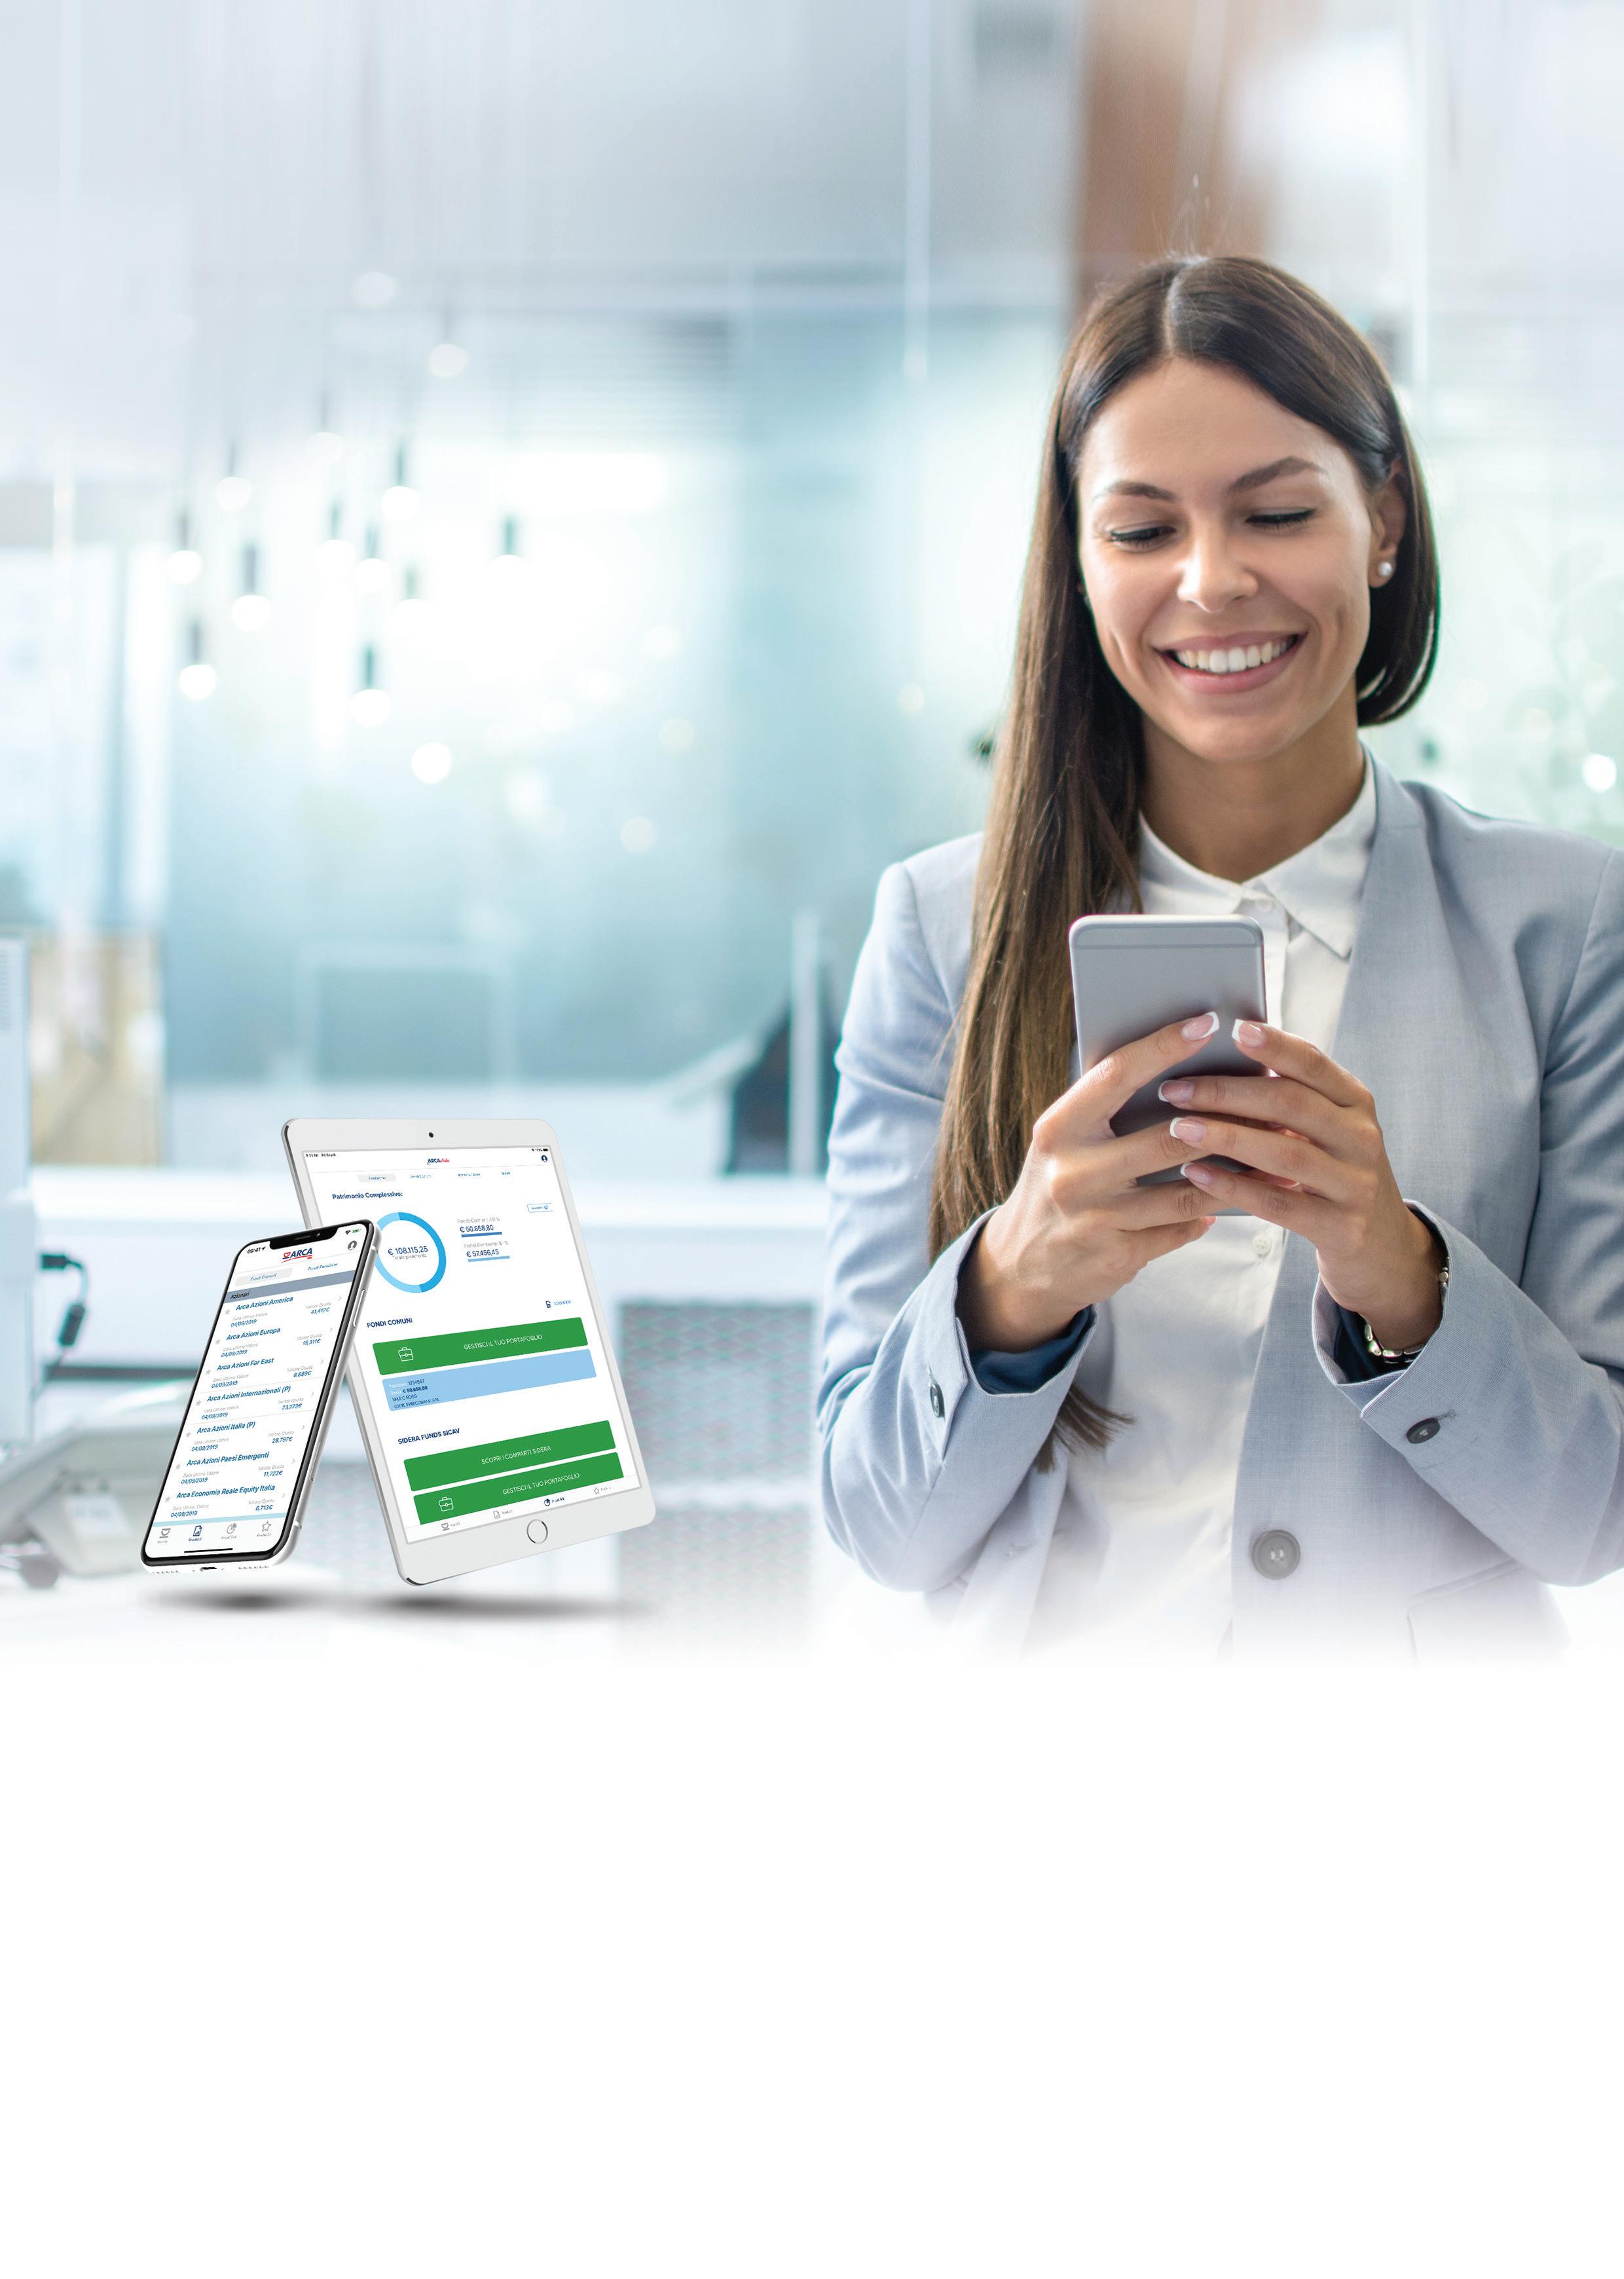
Through innovative technologies Arca Fondi SGR has set up new processes that have improved the relationship with customers and increased productivity and performance.

by Sam Morgan
COVID-19 is set to have a stimulating effect on various forms of mobility, thanks in part to a change in people’s travel habits, caused by the pandemic. The 2020s could be a golden age for bikes, scooters, electric cars and trains.
Lockdowns and the need for socialdistancing have convinced city planners to allocate more space to active mobility like cycling and walking.
As quarantines lift and more people go back out into the streets, space is at a premium.
In capitals like Berlin, Brussels, Paris and Rome, kilometres of new bike paths have been created and existing routes widened. Roads that were previously the domain of cars are now blocked off and pedestrianised.
Governments want people to use mass public transport only when absolutely necessary and to leave their cars at home when possible - which was already an objective of sorts before the virus struck - and have offered purchase subsidies to thousands of people.
Italians can qualify for a €500 voucher that can be spent on bikes, scooters, monowheels or hoverboards, while French citizens can get their bike repair bills paid for by the government. Although the now ubiquitous sight of
brightly-coloured ride-share e-scooters and e-bikes largely disappeared from Europe’s streets during lockdowns due mostly to curfews and hygiene concerns, the sector’s big players are planning a comeback.
uber recently offloaded its flame-red e-bikes and e-scooters to Lime, after leading an investment round worth $170 million. The two firms have agreed to integrate better their apps and collaborate more effectively.
“Lime is emerging from the crisis as the clear market leader, with expanded bike options and financing that will position us to build a sustainable long-lasting business,” said Lime Europe’s Ghassan Haddad.
The deal suffered an immediate major hiccup though, as thousands of e-bikes were sent to the scrapheap, as Uber cited “maintenance, liability and safety concerns”. After a mass public backlash, the companies decided to reverse their decision.
Improved air quality caused by the slump in industrial and transport activity during lockdown has also increased consumer awareness about health and climate issues. Uber’s ride-hailing rival Lyft has jumped on that bandwagon by pledging to go green in a big way.
in mid-June, the us firm said that all of its vehicles would be electric-powered by 2030 to prevent tens of thousands of tonnes of pollution from entering the atmosphere.
“Now more than ever, we need to work together to create cleaner, healthier, and more equitable communities,” said Lyft co-founder John Zimmer. “Success breeds success, and if we do this right, it creates a path for others.”
But his company did not reveal how much it is willing to spend to make that happen and convincing the huge number of people who use their own cars to work shifts will be a tall order.
New research shows that electric vehicles can actually be cheaper to run than regular combustion engine cars though, depending on which country drivers are in and where they are able to recharge their batteries.
According to a study by mobility group Transport & Environment, French drivers could save up to €3000 per year. In general, savings could reach 14% when compared to a normal diesel motor.
With more and more cities announcing or contemplating diesel and petrol bans, electric cars are rapidly becoming a financially sound decision for professional and personal use alike.
A new raft of government multi-billion-euro bailouts prompted by the virus outbreak is also set to increase the choice of models available and a fall in list price, as companies like Renault and Volkswagen will have to hit ambitious production targets.
According to Bloomberg, 10% of new sales globally will be electric cars by 2024 and 28% in 2030, with much of that demand coming from China and Europe. That boost will largely be prompted by a rapid decrease in battery costs, which form the bulk of purchase prices.
Relatively new technologies aside, an old cast member of the transport scene is due for more than a cameo appearance in the coming years: train travel is due a resurgence too.
According to UBS Research, a shift in consumer habits will be a boon to Europe’s high-speed rail market, which is on track to grow 10% every year this decade. The EU even wants to declare 2021 ‘The European Year of Rail’.
Passengers are generally willing to go on longer and perhaps more expensive journeys, if there are plus points like a lower carbon footprint and an improved travel experience, opening the door for trains to eat away at cheap short-haul flights.
Rail operators are starting to cotton on to that change in behaviour by bringing nighttrains out of storage, long moth-balled due chiefly to lack of profitability and interest from rapid transit junkies.
The coronavirus may have dealt a heavy body blow to the aviation and cruise industries but for slower nodes, better suited to a postpandemic world, the outbreak may prove to be the catalyst for a major shift in how we all get around.
by Kenny Fowler
Trying to gain a traditional visa can often be quite difficult and time-consuming. Golden visas can save you a lot of time and effort, for a price.
A golden visa is issued to individuals who invest a certain amount of money in the issuing country. The visa can be a temporary or a permanent residency visa. The most common means of gaining a golden visa is through the purchase of real estate.
The origins of golden visas go back to tax havens in the pacific and caribbean, which initiated investment programmes that allowed for tax advantages and visa-free travel. In the early 21st century, the number of immigrant investor programmes has accelerated, with about a quarter of all countries offering these visas.
The United States grants permanent U.S. residency through the EB-5 visa to investors of certain government-approved projects in the U.S. This visa gives a recipient the right to live, work, study or retire in the U.S. Once the project is complete, the recipient can receive their entire investment back. The visa allows not only for the residency of the investor but also their spouse and any children under the age of 21. The required investment for obtaining an EB-5 is $900 000.
The E2 visa is an alternative to the EB-5 and can be obtained through certain countries which have an E2 treaty with the U.S. The required investment is $500 000, making it significantly cheaper than an EB-5. An E2 visa can also be faster than an EB-5. however, the E2 is a non-immigrant visa so in contrast with the EB-5, obtaining an E2 cannot lead to getting a Green Card.
The Tier 1 Investment Visa allows the recipient to obtain temporary residency in the UK, for the investor and his or her immediate family. The UK provides no direct path to permanent citizenship. The temporary residency lasts three years and four months. Applicants can apply to get this residency extended an additional two years. after five years, investors can apply for indefinite leave. This can be shortened with more investment. After six years, a recipient can apply for British citizenship. The Tier 1 Investment Visa requires a minimum investment of £2 000 000.
Until March 2019, the UK offered the Tier 1 UK Entrepreneur Visa. But at that time, it was replaced with the Innovator Visa and the Startup Visa. Unlike the previous entrepreneur visa, an applicant must now provide an original business plan that meets new or existing market needs. The applicant must also show they have the necessary skills, knowledge and market experience to be able to run the business.
For a startup visa, no funds are required to qualify. Recipients can live in the UK with their families for two years. The sole focus of the recipient during that time is developing their business. After these two years are up, a startup visa holder can apply for an innovator visa.
The innovator visa requires a minimum investment of £50 000. Recipients and their families can reside in the UK for three years. During these three years, the recipients will be required to focus solely on developing their business. Once the three years are up, the applicant can apply for an extension to stay another three years or to take up permanent residence in the UK.
Golden visas are handled by EU member states, but residency in an EU member country allows one to travel across much of the union without any additional documentation. Citizenship enables one to work or travel within the EU, and even to non-EU countries which have visa-free agreements with EU member countries. here is a sampling of some of the best golden visas in the EU:
Portugal has one of the best golden visa programmes. It is the original “Golden Visa” programme and is actually where the name came from! It was launched in 2012 to help bolster the Portuguese real estate market.
A real estate investment of €350 000 is required to obtain a residency permit that allows for a spouse and dependent children. You can apply for European citizenship after five years. The visa can be renewed every two years as long as the applicant spends two weeks in Portugal every two years. This visa also allows travel to all 26 countries in the Schengen Borders Agreement.
Spain began its golden visa programme in 2013. In order to gain residency for a family, a real estate investment of €500 000 is required. The visa can be renewed every two years. An applicant can apply for permanent residency after five years and citizenship after ten years. There is no requirement to live in Spain to retain or renew the residency permit but applying for permanent residency or citizenship requires you to have actually resided in spain for five and ten years, respectively. Like the Portuguese golden visa, with the Spanish golden visa, you can visit all 26 countries in the Schengen Borders Agreement.
The Irish Immigrant Investor programme was launched in 2012 and then revamped in 2013. The update allows applicants from outside the EU to gain residency in Ireland with a €1 million investment in an Approved Investment Fund. Prospects must be found of good character, have a clean criminal record, and they must demonstrate a minimum net worth of €2 000 000.
St. Kitts and Nevis have one of the oldest golden visa programmes in the world. It was created in 1984 to grant citizenship through donation or real estate investment to those applicants who qualify. The government requires an investment of $150 000 to the Sustainable Growth Fund or an investment of $400 000 in real estate. The real estate can be reduced to $200 000 for those investors with connections to the islands. These figures do not include any fees.
Golden visa programmes are a way for countries to increase investment by granting residency to foreign investors. Whether they are used simply as a way to invest and keep an eye on your investment, a strategy for making travel easier or even as a means of gaining better educational or professional options for your kids, golden visas can provide a path to a better life.
Taipei Fubon Bank has earned the trust of its customers with its customeroriented approach, pursuit of innovation and sophisticated service, and has championed sustainability on a foundation of financial innovation in the corporate, social and economic realms, earning the bank considerable recognition from around the world.
On the institutional side, the corporate loan business grew rapidly and the syndicated loan business ranked third among privately run banks. On the retail side, a branch renovation project that localised service and product and service innovation generated solid growth in deposit, investment, insurance and credit assets. Outstanding mortgages ranked second among privately run banks and insurance sales ranked third among banking channels.
Taipei Fubon Bank is rolling out a Bank 3.0 digital banking environment that will use big data analysis to develop new revenue streams and set up advanced information systems to meet the growing demand for online and mobile banking services.
At the same time, the bank continues to integrate its branches and virtual channels to meet customers’ evolving financial services needs. Branches around Taiwan are being renovated to be more efficient, while internet and mobile banking services are being optimised to drive innovation in the customer experience and boost the overall quality of service.
INNOVATION AND TECHNOLOGY DRIVING NEW TRENDS
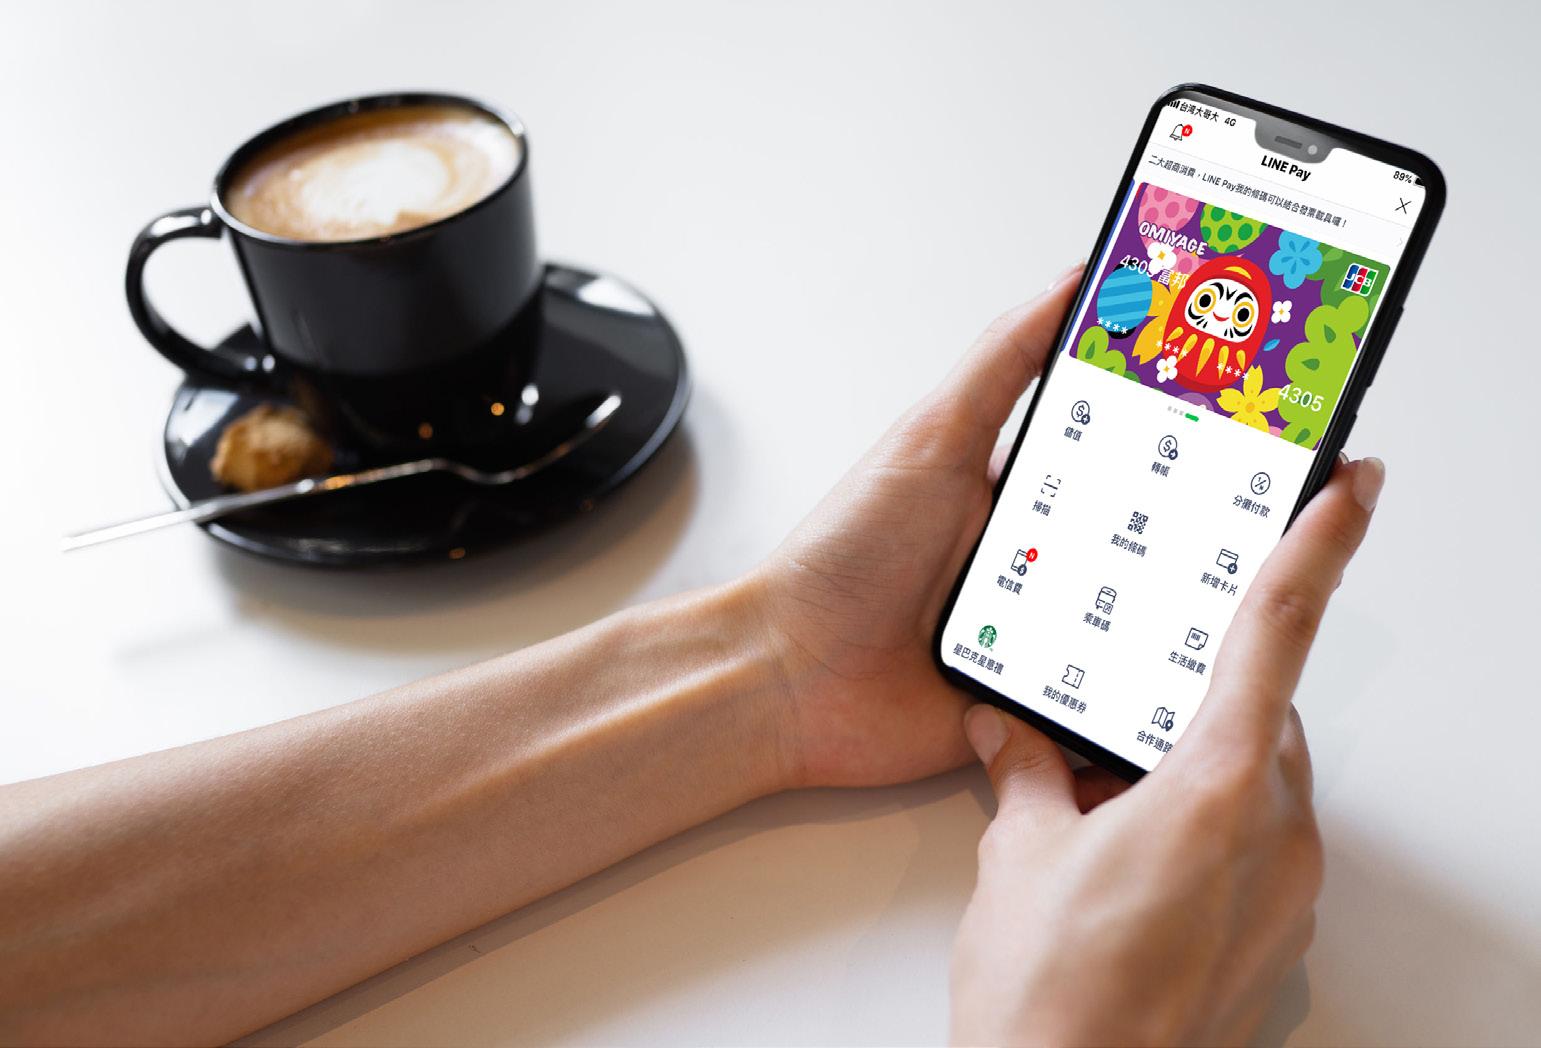
To deliver a better, more convenient banking experience, Taipei Fubon Bank has pioneered new “financial living” models that integrate cloud computing, big data, and artificial intelligence into daily life settings. The J card, aimed at frequent travelers to Japan and South Korea, accelerates review processes and offers a unique feature - users can increase their credit card limit with a simple tap of their smartphones, creating a great user experience.
By the end of 2019, 670 000 J cards had been issued, a new high for any single JCB credit card in Taiwan! It also moved Taipei fubon bank into the top five credit card issuing banks with 3.29 million cards in circulation.
The smart investment platform, Nano Investments, launched by the bank in collaboration with Nutmeg, the UK biggest robo-advisor, enables people to invest as little as US$ 100 in global diversified portfolios through fractional shares technology, helping them minimise risks and earn stable returns. By the end of 2019, assets under management in the platform had reached NT$1.4 billion, and over 97% of investors had earned positive returns.
Mobile payments are also ripe for innovation. The bank initiated Taiwan’s first blockchain interbank transfer sandbox experiment. The new technology simplified the transaction process and lowered costs, and may be extended in the future to cover cross-border remittances and supply chain financing. in another first, a new ai loan approval app was introduced that allows associates to check a company’s credit on the spot and calculate a precise credit line and loan rate, providing a more convenient SME loan experience.
Taipei Fubon Bank has assertively expanded overseas to support the global development of its customers, establishing a platform that spans Taiwan, hong Kong, China, Vietnam, Singapore, and Indonesia and offers efficient channels, innovative products and professional service. The eventual goal is to create a one-stop shop service platform that will help corporate clients go international and expand their size and network, and have them make the bank their top strategic banking partner.
As Taipei Fubon Bank develops a robust financial services platform across the region, it has not forgotten the spirit of giving back through tangible actions. The Bank has held an annual Budding Tycoon Money Management Camp since 1998 to foster healthy attitudes toward money among young Taiwanese and help them understand future financial trends.
Another initiative was launched in 2012 in cooperation with the Fubon Cultural & Education Foundation called the
Future Tycoon Outreach Programme to narrow the urban-rural divide and help disadvantaged elementary school students in remote areas learn basic concepts on how to properly manage money.
These long-term efforts have successfully planted the roots of financial literacy education in Taiwan.
IN CONVERSATION WITH ANNA ZAKRZEWSKI, A MANAGING DIRECTOR & PARTNER OF BOSTON CONSULTING GROUP (BCG).
Zakrzewski along with Kedra Newsom, Michael Kahlich, Maximilian Klein, Andrea Real Mattar, and Stephan Knobel, wrote the BCG report Managing the Next Decade of Women’s Wealth, published earlier this year.
Over the past few decades, women have become a sizeable economic force, but it’s these next few years that will be a defining decade for women in wealth, according to the new bcg report. Anna Zakrzewski, one of the lead authors, summarises, women are “adding $5 trillion to the wealth pool globally every year— outpacing the growth of the wealth market overall but in spite of the increasing power of their purse strings, women remain largely underserved by the wealth management community.”
While the report, Managing the Next Decade of Women’s Wealth, was published the week before the world went into lockdown, the long-term trends remain largely unaffected and women’s wealth is still expected to outpace global wealth growth over the next years. The trend is intensified by the growing number of women taking the lead in financial decisions. some regions have more catching up to do than others. In Asia, 79% of women take the lead on financial decisions compared to 86% of men. in north america, 70% of women take the lead in financial decisions versus 92% of men; in Europe however the rate drops to only 40% of women compared to 85% men and, in the Middle East, this compares to only 20% of women and 93% of men.
as Zakrzewski explains, “over the last five months, we have seen that COVID-19 is accelerating sustainable investing. 64% of investors believe the pandemic is a tipping point for ESG.” ESG (Environmental, Social, and Governance) refers to the three central factors in measuring the sustainability and societal impact of an investment. For women, value investing is of higher importance than for men.
These past months, ESG funds have begun to further diversify beyond the red button issue of climate change. “The full breadth of the definition is filtering into mainstream investment discussions,” says Zakrzewski. If wealth managers can avoid the pitfalls of common misconceptions and “personalise their approach to meet the specific needs and priorities of individual clients, regardless of gender”, Zakrzewski argues that the enormous business opportunity of female investors can be unlocked.
Naturally, how women generate their wealth varies from region to region. Women in North America currently hold the largest relative share of wealth, with 37% of the total regional wealth pool. Asia, with the notable exception of Japan, is the fastest-growing hub of wealth creation for women, set to add $1 trillion per year to their total wealth over the next four years – setting Asian women up to hold more wealth assets than any other region in the world except North America by 2023. In the Middle East, women’s wealth segments in assets under management (AuM) are also poised to experience substantial growth in the years ahead with an expected CAGR of 8.8%. Female rates of primary and secondary education participation are now similar to those of men, and women outnumber men at the university level in 15 of the 22 Arab countries.
Despite these advancements, wealth managers are still using historical social norms as a reference point, regarding men as the primary financial decision-makers, and this attitude is not going unnoticed. 64% of female respondents to BCG’s survey felt that their bank or wealth management provider needed to improve its value proposition, with working women and those in the highest wealth bands expressing the most dissatisfaction. The women’s segment is too often dismissed, considered primarily in terms of marketing. Outdated assumptions about what female investors want, combined with an inadequate understanding of women’s actual behaviours and preferences, have contributed to subpar service. As Zakrzewski explains, women do think differently, just not in the way tradition dictates.
“There is a preconception that women are far more risk-averse when it comes to investing but this simply isn’t the case. It takes women longer to make an investment decision because they tend to gather data and information before committing. But when they do take the plunge, it’s the same risk profile as men. Once they invest, it’s an equal playing field.”
If you dig a little deeper into women’s typical investment behaviour, they tend to spread their risk a bit more but remain more committed than men when it comes to long-term investments, having the patience to make investments with a longer-term perspective. If the performance of two investments is more or less on par, women tend to choose ESG-focused investments more than men; and also those that most align with their own values. In addition, they are looking to invest to fund specific life stages or goals much more than men.
In a nutshell, “the future pool of clients, both men and women, will not just want more, they’ll want better,” says Zakrzewski. This means they’re looking for investments that are engaged and purposeful. BCG’s research shows that gender-based differences in investor behaviour diminish with every new generation. Millennial men and women share very similar views, including a shared preference for purposedriven investing.
Meanwhile, more women than ever are taking the lead in financial decisions - 70% of millennial women, compared with just 40% of female baby boomers. Zakrzewski explains that “women’s empowerment is fuelled by three main drivers - wage equality, more entrepreneurial activities by women, and more women in leadership positions. Women that accumulate wealth themselves tend to manage it more actively. Our data shows that younger women delegate fewer financial decisions than older women.”
Ten years ago, Zakrzewski was writing a report with her colleagues on levelling the playing field. at the time, it was thought that 2020 would see much less unconscious bias and women would no longer be treated as a homogenous group by wealth managers. Although the advancement has been slower than she hoped, Zakrzewski remains optimistic that the speed of change is only going to accelerate and is hopeful that we will see the industry taking big strides in the next five years.
Sharia law prohibits banks from charging interest on loans to their borrowers.
islamic banks offer financing to individuals and businesses through real economic transactions such as joint ventures, deferred sale, and leasing agreements.
To offer credit financing, islamic banks need a mechanism to discipline debtors to pay on time. A common practice involves charging debtors with late fees, which are then donated to charity. however, because Islamic banks are not allowed to incur any profit and in turn any benefit
from these late-payment charges, they are not incentivised to collect these fees and distribute them to charitable organisations in a timely manner. Meanwhile, the debtors see these late fees as an act of charity, meaning that their sense of urgency to pay their debt obligations on time might diminish.
Blockchain originally impacted Islamic finance through optimisations like blockchain-based halal certification schemes but there’s a growing demand
for the technology to automate the execution of Shariah contracts and minimise the risk of procedural errors. It could also improve the traceability and transparency of certain funds in complex humanitarian settings.
Although the technology is still a controversial topic in islamic finance, both the Middle East and Southeast Asia are home to a growing number of Islamic fintechs.
Abu Dhabi Islamic Bank (ADIB), a leading islamic financial institution, was the first Islamic bank to successfully execute trade finance distribution transactions using blockchain technology.
The cross-border transactions, which were completed with multiple banks, were made possible through ADIB’s partnership with TradeAssets, a trade finance e-marketplace powered by blockchain to help digitise the traditional processes of origination and distribution of trade assets. For the past year, ADIB’s collaboration with TradeAssets has enabled it to automate trade finance transactions and conclude transactions successfully with banking counterparts in emerging markets.
The Islamic Research and Training Institute (IRTI) of the Islamic Development Bank (IsDB) Group has partnered with the blockchain technology firm blocko to build a blockchain-based innovative credit enhancement system. It would minimise the risks associated with credit financing to businesses and consumers by using new economic incentive models and advanced implementations of hybrid blockchain technology.
“The Islamic finance market is growing rapidly, with projections of a rise from around $2 trillion to an impressive $3.78 trillion by 2022. Yet certain technical and economic challenges have prevented the industry from truly flourishing,” said Dr Sami Al-Suwailem, Acting Director-General of IRTI.
The partnership aims to leverage the E24P blockchain teams’ deep expertise in deploying blockchain systems to further the IsDB’s mission of enabling greater financial inclusion, alleviating poverty, and accelerating the development of the islamic financial industry.
Phil Zamani, CEO of E24P, said, “the implementation of blockchain systems in complex processes like credit and insurance has long been sought after by financial institutions around the world. Forward-thinking Gulf Cooperation Council (GCC) countries, such as the UAE and Saudi Arabia, have been especially progressive, implementing blockchain projects to accelerate their digital transformation agendas and smart city innovation strategies.”
The new system being developed by IRTI and implemented jointly by IRTI and E24P uses a novel incentive mechanism that encourages early repayment and contributes fees to an insurance pool that covers involuntary credit defaults. Such a system would not be feasible through conventional arrangements but is facilitated through the use of highperformance blockchain technology. Once completed, the system will be of great value to islamic banks and other financial institutions.
With this system, Islamic banks, and indeed other financial institutions, can ensure that credit assessments are performed in a provably transparent and responsible manner while keeping the data and methodology used appropriately secure and confidential.
The system allows creditors to reduce the credit default rate to improve their overall business performance and accelerate efforts in areas of financial inclusion.
According to a recent S&P report, the global islamic finance industry will continue to expand slowly in 20192020 but fintech and blockchain could significantly accelerate the growth. The COVID-19 pandemic has also shown the importance of leveraging technology and creating a nimbler industry. With the right coordination between different islamic finance stakeholders, the report argues that the industry could create new avenues of sustainable growth that serve the markets.
“Fintech could stimulate growth by making transactions quicker, more secure, and easier to implement. And we believe the social role of islamic finance could unlock new growth opportunities as core markets implement the UN Sustainable Development Goals, and issuers and investors become more sensitive to environmental, social and governance (ESG) issues,” said S&P Global Ratings head of Islamic Finance, Mohamed Damak.
by Jan Langlo, director of the Association of Swiss Private Banks
As Albert Einstein said, “in the midst of every crisis, lies great opportunity”. This is mostly due to being forced to do things differently. In the wake of the recent pandemic, many rules were introduced or changed. how did this impact Swiss private banks? Let’s look at this from the point of view of employees, clients and regulatory authorities.
Nearly overnight, about 80% of bank employees were forced to work remotely. Business continuity plans were put to the test and proved the resilience of the banking system.
An evolution which would have taken years happened in a few weeks. Banks which were cautiously introducing home office now have, at most, 50% of their staff in their premises.
Split teams are still the norm and this helps reduce the number of people who use public transportation. The good news is that most employees who work from home enjoy it and are as productive as before, some even more. nevertheless, contacts in the office are still necessary for an optimal sharing of information and spreading of the company’s values.
Banks were not closed during the lockdown, as their activities are always essential. Payments still need to be made, even if some mandatory ones like taxes or insurance premiums were postponed. Credits were crucial to maintain liquidity and in a single week, commercial banks, government and the Swiss National Bank set up a plan to grant loans that are interest-free up to 500 000 Swiss francs and guaranteed by the Swiss State to small and medium enterprises, to compensate up to 10% of their annual revenues. This scheme allowed a quick distribution of more than 14 billion Swiss francs. The employees of commercial banks did a fantastic job and did not count their hours to handle the more than 130 000 credit requests that came in.
On the wealth management side, there was also a lot of activity during March, as clients wanted to reallocate their assets as the markets crashed. Although physical contact had to be avoided, human interaction remained at the heart of investment activity. Clients understood that their banker could no longer travel to meet them and adapted quite well to videoconferences. Many accounts were opened online, new applications were launched and contactless payments soared (and the limit under which no PIN entry is required was raised from 40 to 80 Swiss francs).
Regulatory authorities also showed a lot of flexibility in light of the constraints that banks faced. For instance, they agreed to extend the deadline to obtain certified copies of passports or other documents when opening an account from abroad. They relaxed the capital and liquidity requirements linked to the credits mentioned above. They added some exemptions relating to the leverage ratio and risk diversification. all this shows the value and efficiency of the swiss financial centre, where banks and authorities discuss and find practical solutions.
Going forward, the pandemic showed that the economy will need to rely more and more on digital solutions. Must we all really commute to work every day? Do we need to go to stores to buy something? Most production and leisure activities require a physical presence, but distribution only requires drivers (or drones), and services can be rendered online. in the field of finance, SwissBanking sees six digital trends:
• Banks accelerate the development of workflows without media discontinuity
Demand for financial products and services via digital channels rise quickly
• Diversity and complexity of payment transactions increase
• Trend towards smart working solutions intensifies
• Investments in high-quality and secure digital infrastructures grow
• Authorities speed up end-to-end e-capability
Switzerland will also soon be voting on the introduction of an electronic identity, supervised by the state, but implemented by private companies. As cloud solutions become more and more common, larger quantities of data will need to be exchanged, also on mobile devices. Swiss telecommunication operators are already developing their 5G network. All this will require a lot of energy, which implies
a stable power-grid and sustainable power stations. huge investments in infrastructure need to be made, to prepare for a clean and healthy society. And let’s not forget security, as nothing will eliminate the fact that some also see an opportunity for ill-gotten gains whenever a new system is put in place. Amidst all these changes, private banks are there to help their clients identify the winners of tomorrow.
Arca Fondi SGR is an Italian active asset management company, founded in 1983 by the association of 12 cooperative banks. Today, Arca Fondi manages around €32 billion divided between mutual funds, pension funds, and institutional accounts. Thanks to a network of distributors made up of more than 100 banks and other financial institutions scattered throughout the country, its client base is made up of over 800 000 investors. With almost forty years of experience, Arca has established itself as one of the country’s main asset managers.
The strength of Arca Fondi is its people. Teams who continuously improve themselves to achieve corporate goals. The corporate culture nurtures talent in an environment that encourages selfimprovement and striving for excellence. Thanks to numerous innovative processes implemented in recent years, the customer has been placed at the centre of every single activity. The professionalism and creativity of all employees make Arca Fondi the ideal partner for the investor looking for reliability and safety.
Innovation has been at the heart of Arca Fondi’s business model since its beginning. After the introduction of the law that established mutual funds in Italy (Law 77/1983), Arca was among the first asset managers to be created in the country. The first two funds, arca rr and Arca BB, were launched a year later in 1984. Even today, these two funds are real blockbusters, with an impeccable track record and a more than sevenfold increase in the net asset value. In 1998, the pension fund, Arca Previdenza, landed. In addition to being one of the first open pension funds in Italy, today it is also the largest in the country.
In 2015, Sidera Funds Sicav was created, a Luxembourg-based platform dedicated to private and affluent customers. Two years later, the PIR funds (Piani Individuali di Rispamio), a segment dedicated to investments in the Italian “real economy”, made their debut. In a short time, Arca also conquered leading positions in this market.
Finally, in 2019 Arca signed the United Nations Principles for Responsible investment (unpri), an important first
step that led to the creation of a range of ESG funds and an innovative proprietary ESG Rating system.
The innovation, however, is not limited to financial products, but also in creating new services for its partners. Arca Fondi has generated a digital ecosystem that can support and guide its distributors and customers.
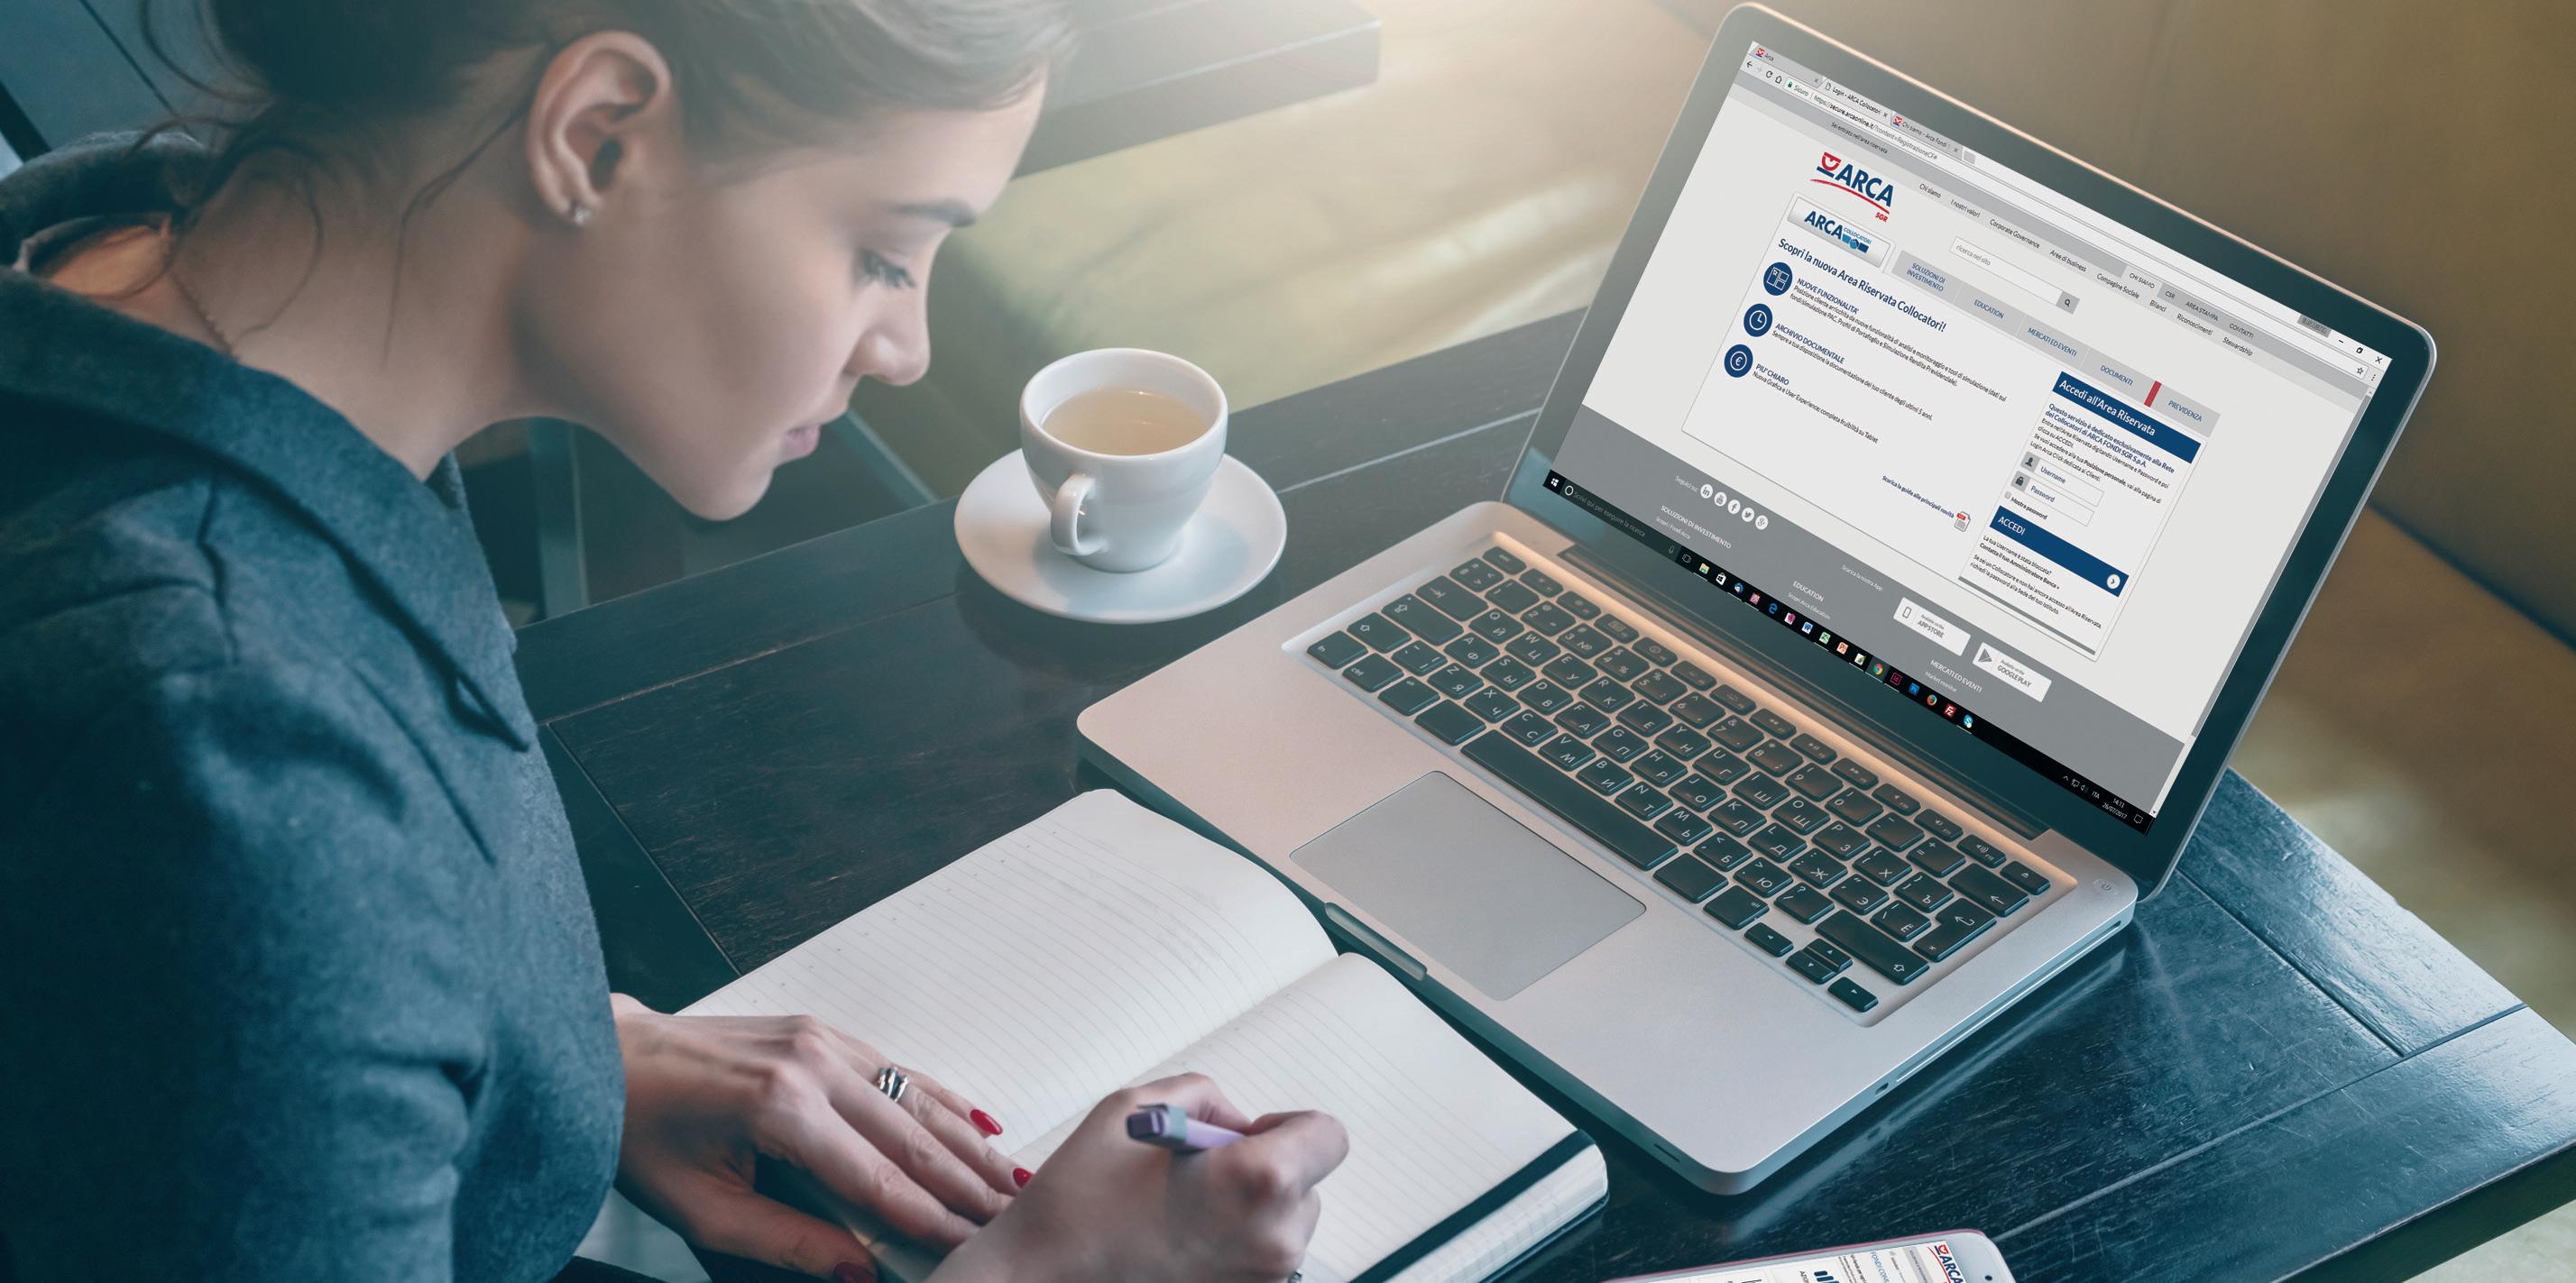
The website, Arcaonline.it, has recently undergone an important redesign to improve the user experience through any device. On the website, the partners can find all the relevant information required to support operations. In addition, there is a section dedicated to all the Arca Fondi products that can be viewed by anyone and provides information on the performance and composition of the funds and much more.
The site is also an archive of all Arca’s commercial and multimedia production. you can find videos that comment on the performance of the markets or sectors, but also exclusive and always updated reports. These materials are shared through dedicated newsletters
and using Arca’s social media channels which cover a series of initiatives as well as being a tool for advertising campaigns, often in collaboration with partner banks. Moreover, Arca has recently launched a financial education project entitled 3 minutes with Arca, a blog that aims to help readers easily understand the risks and opportunities of the markets.
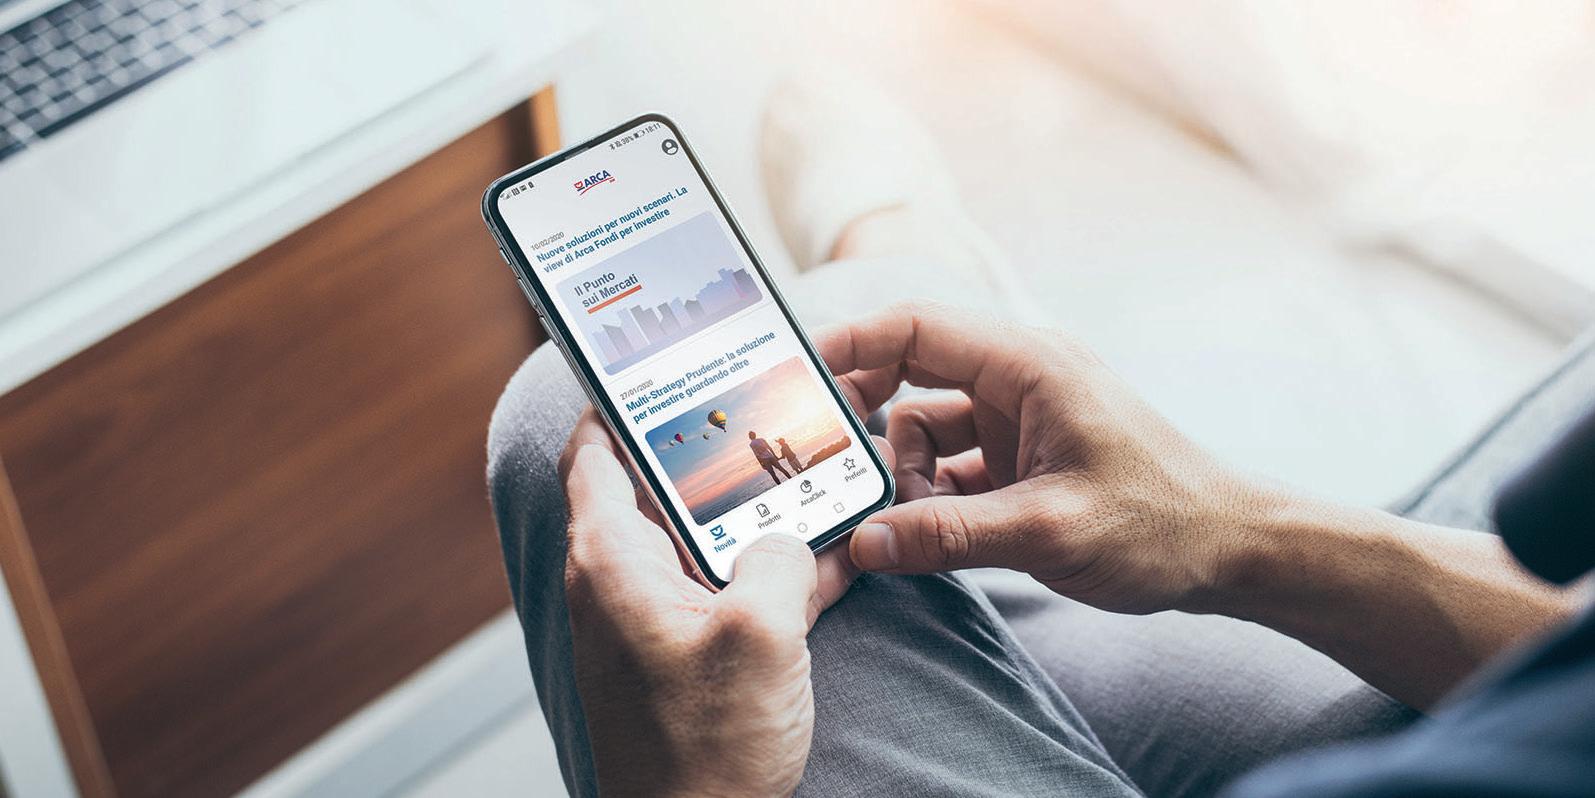
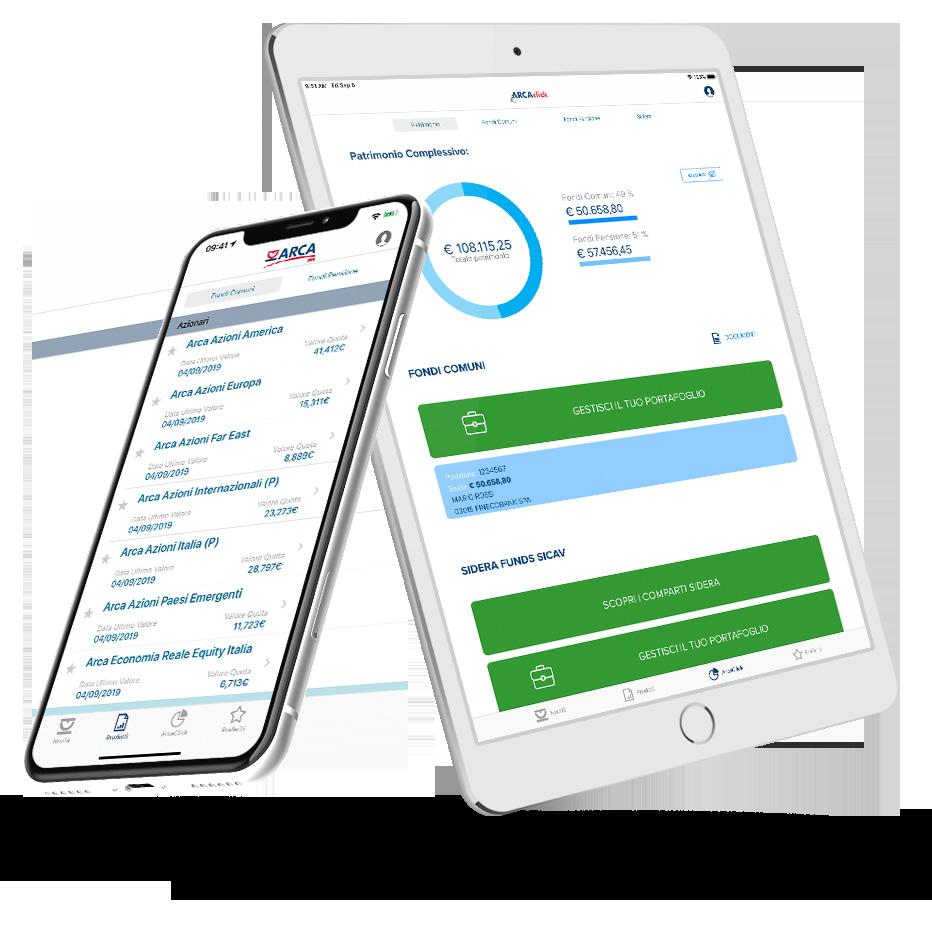
ArcaClick is the area dedicated to all customers who own Arca funds. With the latest facial recognition technologies, the registration process has recently been improved. The procedure can be carried out independently with a personal device or at the bank. ArcaClick allows the customer to have their portfolio, documents and all their practices under control. Those who join the pension fund can also quickly pay their contributions online if they wish. ArcaClick is also accessible from the Arca Fondi App, a free and constantly updated application available on both iOS and Android. The app is an important tool especially for the growing centrality of smartphones in all of our lives. Customers can always have their portfolio under control or read the latest news, discover the fund manager’s videos and much more.
In 2019, Arca created a new internal division called InnovAction Lab to further grow in the Italian market while facing up to the challenges of the future. InnovAction Lab focuses on improving processes using the latest technologies, data analysis and by making the customer the centre of attention. Over the past year, several projects have been put in place to improve relations with partners and customers.
An internal data warehouse has been created which represents the real brain of all commercial and analysis operations. To make the most of its potential, it’s been integrated with a latest-generation CRM, adapted to the needs of an asset manager. To support commercial partners, new innovative solutions have been created such as a Smart Advisor to help distributors sell the most suitable products for customers. Recently a ChatBot, called Sara, has been developed to help anyone in the search for information on the Arca world through the website, WhatsApp or Telegram.
InnovAction Lab is a division that makes colleagues’ collaboration the central part of its work. Everyone works side by side to bring different experiences to reach the most efficient conclusion. one of the main focuses is sustainability. For example, the rethinking of many processes has led to better integration and, above all, has been able to reduce paper consumption.
Today, many of these solutions have become realities that can be appreciated by both Arca Fondi’s customers and distribution partners. But this is only the beginning. Thanks to talent and technology, Arca’s ecosystem is constantly evolving to guarantee the most efficient and safe experience.
by Alex Kazaglis, Director of Vivid Economics
ONE YEAR AGO, THE UK BECAME THE FIRST MAJOR ECONOMY TO PASS NET-ZERO EMISSIONS INTO LAW.
In recent days, however, the Government’s statutory advisors, the Committee on Climate Change, have reported that government actions fall well short of what is required to meet net-zero. A green stimulus package could help fill that gap and deliver an internationally credible netzero plan (vital in the context of hosting the COP26 conference in 2021) as well as generating economic activity (at a time of recession and economic dislocation). A green stimulus could also help rebalance pre-existing regional inequities, through investment in areas of the UK where there is underemployment.
Vivid Economics’ recent work, A UK Investment Strategy: Building back a resilient and sustainable economy, set out priority areas for investment that also deliver against the net-zero agenda.
Key areas for investment are those that support employment and economic activity. While there are already over 460 000 UK jobs in low-carbon businesses and their supply chains, a further 200 000 jobs that could be supported in the next 10 years. But not all jobs are the same – the timeline and location of jobs are important. Over the short term, it is important that jobs boost overall economic activity. Fortunately for many large infrastructure projects, jobs and economic activity are generated during the construction phase.
To be a basis for growth in the longer term however, jobs must be in areas where there are displaced workers. In the UK context, this means investment opportunities that can boost the economic recovery of underperforming regions, such as by creating decent green jobs in those areas.
Many jobs are better suited to existing market mechanisms and private-sector delivery, rather than a stimulus effort.
There are low-carbon sectors where private investment can deliver the levels of deployment required. For example, lowcost onshore wind can proceed through the market. industrial energy efficiency can also proceed through the market but only if regulations are enhanced.
Taking these factors into account, our report identified £30 billion annual net-zero investments (combining public and private) that would help generate economic activity before 2030.
The five priority areas that emerged are:
1. Investment in green buildings can support the most jobs in the short run and provides societal and resilience benefits. The green building sector has a total annual investment need of £12 billion and this will support at least 85 000 direct jobs in green retrofitting by 2030. for energy efficiency building retrofits, there is a skill overlap with current construction jobs, but low-carbon heating requires maintenance and installation engineers to upskill from gas boilers to heat pumps.
Since our work has been published, this is a priority that has been reiterated by several reports, including the Energy and Climate Intelligence Unit in the UK and the IEA globally.
2. Investment in nature and biodiversity is a vital part of the UK recovery, including investing in rural employment and adapting to adverse climate effects and impacts. This includes projects that lead to carbon sequestration and biodiversity, as well as flood management which contributes to rural sectors. Our research shows that investments in parks will reduce health costs, reduce air pollution, and improve many other aspects of urban life.
3. Investing in clean energy infrastructure, especially in offshore wind and electricity grids, can support green jobs. 28 000 jobs, including in manufacturing could be supported in raising the UK’s offshore wind capacity from 8.5 GW to 40 GW. The sector is already market-driven, but current contracts for difference (CfDs) can be widened. Government can play a key role in redistributing the co-benefits, by strategically choosing production locations in underdeveloped regions. To support these larger power sectors, investment in transmission and distribution is also required, which has its own capacity to support jobs and economic activity. Investing in overcapacity of electricity grids is a smart strategy for future grid development.
4. Carbon Capture and Storage has the potential of supporting around 30 000 jobs. A net-zero pathway includes approximately 3 million metric tonnes of industrial CO2 captured per annum and will also require some form of carbon removal technology such as bioenergy with CCS (BECCS) or Direct Air Capture (DAC). Investment for industrial carbon capture alone will require around £400 million annually for both the capture units and the supporting transmission and storage infrastructure.
5. The UK automotive sector already supports over 100 000 jobs and lowcarbon investment in electric vehicles (EVs) and EV infrastructure could help support further growth. Currently, the sector is characterised by job substitution, where workers with skills to produce petrol/diesel vehicles can transfer these to EV assembly, supporting around 11 000 jobs by 2030. New jobs can be supported in complementary sectors: batteries and charging infrastructure, with an investment need of over £1 billion annually, can support around 5500 jobs, and these sub-sectors are especially interesting for creating a competitive advantage internationally. Additionally, creating a viable battery and charging infrastructure sector will have a positive spill over on EV producers to boost production, without having to use subsidies or other incentives.
TO PAY FOR THESE INVESTMENTS, MAJOR, WELL-DESIGNED NEW POLICY INITIATIVES ARE NEEDED TO RAISE THE REQUIRED PUBLIC FUNDS.
While the recently announced UK ETS is a good starting point, it is unlikely to raise sufficient revenue in the short term unless a high price floor is implemented. o ther mechanisms, such as carbon obligations, could be used to shift costs onto the private sector. Ultimately a balance of these tools will be required to raise funds in the short term and yield the more than £90 billion of net annual benefits to the UK.
From the city of Porrentruy, in the Swiss Jura, herculis Partners (wealth management) and herculis Guardians SA (storing precious goods and renting individual safes) have a front-row seat to the increasingly fierce competition in the wealth management sector and alternative investments. In particular, herculis managers have seen the global art market fluctuate in the wake of the financial crisis.
In an ever-changing global economy, art is now more accessible to a new public, through new channels. art and finance are now considered two fingers of the same hand – the union of culture and wealth. So herculis Group has gathered the right personnel, developed its employees’ expertise, and built a high-security area to store, exchange or simply to share these valuable items.
as in finance, transparency, regulation, and technological trends play an important role in the art market’s future. Therefore, a collaborative approach between all stakeholders (art professionals, collectors - young and old - and asset managers) is essential to respond to the pressing issues and challenges in the years to come.
Today’s art market is full of forgeries and the forecast is grim. But people are making a more proactive effort to mitigate the risk. It is a challenge for gallerists, experts and other industry players. At herculis Guardians, we have seen a significant change in the choices made by collectors. New collectors - young and from emerging regions - tend to use the services of others to help them with purchases. While most collectors tend to buy what they like, others acquire it as an asset class. And many are doing both.
Nikolay Karpenko head of herculis Guardians SA underlines, “our clients expect nothing less than perfection and know that they can count on us for unparalleled security and confidentiality to protect their most precious assets”.
The general public believes investing in art is usually a high-risk, illiquid, opaque, unregulated investment, with high transaction costs, at the mercy of erratic public tastes and short-term trends. This misconception may be enough to dissuade many people from taking an interest in the art markets and related investments.
The 2008 crisis stimulated the emergence of new compliance policies and new collective investment vehicles dedicated to art or other collectables around the world as well.
There are a number of trends pointing to better transparency, from authorities’ increasingly strict requirements to much more accessible data. Actually, on the fringes of the Geneva Art Fair, the Responsible Art Market (RAM) collective has been bringing together lawyers, experts, gallery owners and auction houses for the past four years. The RAM collective initiated a series of recommendations aimed at drawing the attention of collectors and gallery owners to the legal threats they face. For instance, any art piece sold for more than €10 000 must submit to the new anti-money laundering directive that came into force in early January across Europe. Gone are the days when a client could fall for a painting at the FIAC in Paris, buy it on the spot and walk away with it!
To some extent, technology, whether that’s the internet or the more recent example of blockchain, is now helping to alleviate these issues of transparency, traceability and accessibility.
Technological evolution strongly supports art as an asset class, while also making it more accessible.
We are witnessing a democratisation of this field. While some living artists can sell their works at auction for more than $10 million, 68% of the lots sold in 2018 went for less than $5000.
Blockchain has opened and decentralised the market. All network participants can see the artwork and all relevant information. Should they want to, they can go on to make direct contact with the seller, reducing the need for intermediaries. Thanks to blockchain and the internet, artists do not need galleries to present their work and attract buyers.
With the emergence of new business models such as online auctions, for artists creating and selling in the digital space, the possibilities seem endless.
This technology has been given a boost by the current health crisis and the cascading cancellations of fairs and other major art events. Like museums, actors have turned to online exhibitions and exchanges. This is a fundamental trend to emerge from the pandemic that will undoubtedly continue, just like teleworking or videoconferencing.
new financial vehicles make art an asset class by itself. Of course, the relationship between art and finance has existed for centuries, but today we are seeing a development of art services among financial institutions and small asset management boutiques such as herculis.
From an investment point of view, art is taking advantage of its attraction for diversification, especially in a period of low - or even negativeinterest rates in developed countries.
Advice and risk analyses offered by the asset management companies are increasingly accessible to investors who wish to build up a collection of works of art. Although art items do not usually generate cash flow and are also virtually “unhedged”, we have seen the emergence of financial products linked to the art domain.
One might wonder whether art might not be ready for a transformation similar to what happened in real estate 40 years ago. Real estate today is a widely accepted investment class, accessible to many, and is generally included in portfolios for diversification purposes. investing in young and little-known artists is very similar to venture capital financing.
We can distinguish three categories of artrelated services: art advisory services, art secured lending, art investment services. herculis Group supports its customers in all these categories.
At herculis Guardians, we offer a safe storage solution in a high-security environment with specially equipped vaults while making the collector’s life easier with a secure dedicated showroom. here, the collector might simply enjoy the work to the fullest or arrange for appraisal and commercial operations without making the paintings travel, saving both money and reducing risk - most accidental damage to artwork occurs during transport.
“It looks more like a museum of contemporary art than a warehouse,” says Claude Gaudin, Director.
We can store precious good in our EDO-FREEPORT warehouse, allowing the postponement of VAT, while waiting for the goods to be delivered to end customers anywhere in the world. customers benefit from lower insurance premiums, tax-free storage space and easy access to the nearest airport.
Naturally, COVID-19 is weighing on the market, particularly in Asia, a region that has certainly been key to the growth in demand for art in recent years and it will probably urge the fair organisers to review their models.
Our concluding suggestion to a potential art buyer: at this stage of the cycle, selectivity is paramount. But most importantly: follow your instincts and buy works of art that speak to you. Beyond purely speculative considerations, they could stay in your possession longer than you think!
in a global first, the swiss luxury watch brand, breitling, is accelerating its blockchain-based innovation with the release of a limited-edition watch, featuring a blockchain-based digital passport powered by Arianee to prove authenticity and ownership.
For now, the digital passport is exclusively available to Top Time owners and will enhance Breitling’s already best-in-class e-warranty programme by linking the guarantee directly to the watch and empowering clients to engage with the brand as they wish.
The 1965 classic gets a modern twist as the new limited edition series is breitling’s first watch offered with a blockchain-based digital passport attached that confirms the authenticity and ownership of the watch throughout its lifetime.
The protocol developed by Arianee gives a digital, inalterable, and augmented identity to each product; like any blockchain-based network, it is entirely secured and private.
Breitling is the first watchmaker worldwide to propose a warranty programme enabled by blockchain.
each Top Time owner will benefit from a private and unique digital passport securely linked to his or her limitededition watch. By scanning the validated e-warranty card, they can access and download an encrypted private wallet where the passport is securely stored.
The passport includes all the details about the watch, including its serial number, and is stamped with an event representing the date of the warranty activation on the purchase date. Only accessible by the owner through the wallet, this passport includes a transfer feature that enables the owner to prove the authenticity of the watch, and his or her legal ownership.
This innovative service will offer an additional layer of value for Breitling Top Time owners by eliminating the need for a physical authenticity certificate. Additionally, it will enable the transfer of the warranty.
With such blockchain-based digital passport, collectors no longer need to keep paper records and can engage with the brand as much as they wish, under full anonymity.
Breitling’s ambitions don’t end with the digital passport. As a sign of their commitment to developing blockchain’s potential for the industry, Breitling has become an active participant within the Arianee consortium.
Antonio Carriero, Breitling’s Global CDTO said, “with Arianee and its blockchain technology, we have the unique opportunity to strengthen the link with our customers. This is only the beginning, but we are already working on innovative ideas on how to further leverage Arianee to bring additional services to our customers”.
Arianee were pleased to welcome Breitling into the consortium. Co-founder, Emmanuelle Collet, added that “this project is a great illustration of how our open-source protocol can add a layer of value to existing innovative programmes. our open-source protocol is specifically built to make it easy to create and manage digital identities to ultimately add more value to brands and clients”.
As Carriero explains, “at Breitling, customer engagement is at the heart of everything we do. Technology empowers customers and digital is how they live. It is on us to change and to keep the pace with the speed society is moving”.
Keeping up with customers’ expectations of what products can and should be able to deliver means Breitling will be one of many investing more in digital technologies to revolutionise the luxury good market.
A sustainable business involves long-term, strategic planning for business growth with positive environmental, economic and societal continuity. It is about ensuring the prolonged existence of an organisation in a way that benefits the business, its stakeholders, and the environment. Organisations need to understand the impact of sustainable development on their longterm survival and the importance of its leaders’ commitment.
The triple bottom line of people, planet, and profit captures the essence of sustainability by measuring the impact of an organisation’s activities on profitability, shareholder values as well as its social, human and environmental capital. People and organisations today are constantly working towards balancing their triple bottom line.
The sustainability sector has grown rapidly, with global annual revenues at about $1 billion and projected revenue of over $12 trillion by 2030. The success or failure of sustainability goals must be measured in terms of the wellbeing of people and the health of our planet, and not only in terms of profit and loss.
at access bank, one of africa’s leading financial institutions, we are committed to contributing significantly, towards the achievement of the Sustainable Development Goals (SDGs). We are aware that our operations have a direct impact on the economy, people, and the environment. Therefore, we always ensure that our business operations and practices are environmentally responsible and socially relevant. Part of our contributions to the sDgs is also facilitating and financing sustainable economic growth as well as increasing our efficiencies to mitigate adverse environmental impact.
Over a decade into our sustainability journey, we have aligned our corporate philosophy with our sustainability strategy and remain committed to setting standards for sustainable business practices.
We provide innovative solutions and implement strategic initiatives for our shared future, as we pursue our vision to become the world’s most respected African bank.
We strengthen the people and businesses in our local communities by supporting various projects, organisations, and events that are focused on making a positive difference. Our priority areas of support include health, education, sports, arts, social welfare, and environment.
We have invested over N9.34 billion in various corporate social responsibility efforts since 2015, impacting more than 1316 communities and touching 30 075 356 lives and 793 NGOs. Some of our notable community investment programs include the 2020 hIV Testing and Counselling Services at the Access Bank Lagos City Marathon. At the event, we tested and counselled 3235 people. We also reached 33 468 people with hIV educational materials and distributed 10 000 condoms. In July 2020, amidst the COVID-19 pandemic, Access Bank partnered with 9iJaKids to deliver an online financial literacy and educational gamification modules to children. More than 2000 children were able to access financial literacy education through the programme.
In 2019, the bank partnered with ACT Foundation to provide grants to 28 NGOs to implement projects in the areas of health, entrepreneurship, environment and leadership. The grantees have so far impacted over 685 505 lives through their programmes.
The bank partnered with SME FUNDS, to develop the Green Social Entrepreneurship Program (GSEP), a social enterprise focused on ending poverty by promoting sustainable enterprise development. The program empowered entrepreneurs with clean cooking stove technology, which makes use of Bio-Gels made from water hyacinth, biocremol, caustic soda, fragrance and chlorophyll, to replace existing cooking technologies that are harmful to both human health and the environment.
Thanks to this programme, 598 households now use clean stove technology across Nigeria while 2100 people use clean stove technology, displacing 292 metric tonnes of CO2.
In addition to Access Bank’s community investment efforts, its employees advance sustainable social development in their communities through the Employee Volunteering Scheme. Employees contribute ideas, skills, and resources to address social issues while gaining hands-on experience and fulfilment.
Between 2015 and 2019, employees devoted 2 735 011 hours in over 320 strategic initiatives across six geo-political zones in Nigeria! Volunteering is embedded in the performance appraisals of all staff, thereby encouraging active participation.
Access Bank’s culture recognises that a better and prosperous future is linked to the well-being and health of our planet. The bank invests in innovative technologies and techniques that promote the efficient use of resources and address sustainability issues when managing risk.
Access Bank’s dedication to a cleaner environment is evident from its investment in alternative energy sources. Alternative sources of energy will power the future and Access Bank continuously seizes opportunities to harness energy derived from environmentally conscious means. The bank currently has 58 branches powered by alternative energy (hybrid); 559 solar-powered ATMs nationwide; leD lightings and motion-sensitive lightings in the head office and some branch locations. It recycles its waste across 75 business locations, there are water-efficient taps at its head office. it also ensures regular reporting, monitoring, and evaluation of electricity consumption across all branches.
The bank has an early shut-down policy which ensures that staff members shut down systems at 7 p.m. These efforts have contributed towards reducing our carbon emissions as we recorded a 33.6% decrease in our electricity consumption at our head office and 31% decrease nationwide in 2019.
Our ‘No-Paper’ initiative focuses on saving trees to help protect the environment. We have automated our business processes with the launch of the ERP Dynamics 365 and ProcessMaker applications. This year, the bank launched the Paper to Pencil recycling initiative, converting old branded paper items of Access Bank to pencils.
access bank’s goal is to facilitate and finance sustainable economic growth, leading the way on sustainable finance, financial inclusion, helping develop enterprises and championing sustainability regulation and thought leadership. This is done through our strategic partnerships and collaboration with formidable institutions, to address responsible business needs as well as provide solutions that help improve communities. in 2019, access bank launched the first-ever n15 billion corporate green bonds, certified by the climate bonds initiatives (cbi). The Bond was listed on the FMDQ platform, the Nigerian Stock Exchange, and the Luxemburg Stock Exchange. The proceeds from the bonds financed environmentally friendly projects.
In 2018, we launched the Africa’s Gateway to the World campaign, a strategic initiative which promotes global access to finance in Africa, thereby increasing economic opportunities and investments to further boost national savings.
Our Access Africa product is an instant fund transfer product designed to simplify global payments by Person-to-Person (P2P), Business-to-Business (B2B), Person to Business (P2B), Government to person (g2p) and any other payment activities/flows. access Bank has leveraged its extensive partner network to extend the reach of Access Africa to about 15 countries which include the UK, France, Germany, China, and Benin. Within the year, transaction value stood over $41 million in approximately 14 000 transactions.
Access Bank has continued to comply with environmental and social laws as one of Africa’s foremost banks in sustainability. In 2019, the bank served as the regional lead in drafting the Global Principles for Responsible Banking in collaboration with UNEP fi. The princinples serve as a global framework for financial institutions to comply with a set standard for interacting with the environment.
The bank also serves on the board of several leading local and global organisations, including:
• Co-Chair, Corporate Alliance on Malaria in Africa
• Co-Chair, Nigeria Business Coalition Against AIDS
Chair, Nigerian Sustainable Banking Principles Steering Committee
• Member, Private Sector Delegation to the Global Fund Board
Board Member, United Nations Global Compact Local Network Nigeria
• Africa Consultative lead, Global Principles for Responsible Banking
• Member, United Nations Environment Programme Finance Initiative
• Member, Equator Principles
• Gold Member, Global Reporting Initiative
• Member, International Council for Sustainable Standards and Certification Initiative
Over the years, Access Bank has gained recognition and remained a pioneer among its peers mainly due to its strategic collaborations and efforts in promoting sustainable development both in Africa and globally. As a result, the bank received numerous awards from prestigious awarding bodies, both locally and internationally.
access bank continues to set the pace for sustainable finance in Nigeria and Africa by delivering value-adding products and services, improving the economic and social status of our communities. Our commitment to sound sustainability practices means we constantly monitor the socio-economic and environmental impact of the activities of all our stakeholders and remain at the vanguard of sustainability regulation and thought leadership.
by Aykut Alan
Islamic banks have been integrated into the world financial and banking system in the last 20 years, although the banking system in Islam is much older. however, islamic banking and financial instruments offer a limited service to investors compared to the banking practices we know. The basic principle of islamic financing is not to use interest or “riba” in the words of those who manage these banks in any financial investment or banking transactions.
The concept of islamic finance, defined as “interest-free banking” or “participation banking” in the economic literature, requires that financial transactions and banking operations be carried out in accordance with the basic rules of Islam.
in islamic financial institutions, interest is not applied when borrowing or lending. it is also prohibited to use financial instruments open to speculation in the islamic financial market. Today, islamic
finance tools are used in about 60 countries. The islamic financial market accounts for 1% of the global financial system, estimated at roughly $2.5 trillion, covering some 1400 institutions spread across 80 countries.
The basis of islamic finance is the prohibition of interest. There is no problem in terms of profit from an investment. The basic principle is not to make money from money, but to make money by turning your money into an investment, but in this case, there is a possibility of loss. The main structures used in the islamic financial market are:
• Istisna’a: It refers to the exception to the financial institution borrowing to its clients for a project that has not been produced yet, to provide capital with a contract.
• Ijara (Islamic leasing): These are operational or financial leasing contracts similar to leasing. The bank buys assets on behalf of its customer and makes it available to third parties with a fixed lease. The property is owned by the bank but shares the profit from the rental fee with the investor.
• Mudaraba (instalment sales): It is a partnership in which the bank provides capital and the other party provides labour, knowledge, and experience.
• Sukuk (Islamic bonds): Islamic bonds give partial ownership. The holder gets a fixed share of the income from the assets.
These various forms of financing provided by both Islamic banks and the Islamic finance departments of international banks can be provided as part of a project finance package, in line with traditionally lending banks.
islamic finance reached a significant size in the Middle east and Malaysia in the 2000s. It sees limited demand from Turkey, as the country is integrated into the global banking system. Over the past five years, islamic banking has also started to grow in africa and Asia.
The size of the financial sector is 8-10 times the size of the global gross domestic product. The 2008 crisis, in particular, highlighted the risks of this imbalance. The rise of islamic finance, the capital system which is based on net assets, really came after 2008.
Thanks to the USA’s relatively small Muslim population, the number of participating banks in which individual investors have access to islamic finance products is small. although some banks in the usa have announced islamic financing packages that contain products compatible with sharia, islamic financing instruments are not currently in high demand in this country.
The American Finance house LARIBA, founded in California in the eighties, and the Amana Funds, founded in Washington, are two of the first islamic financial institutions established in the USA. The Dow Jones Islamic Market U.S. Index is designed to measure the performance of U.S. equity securities that have been screened for adherence to sharia investment guidelines. Other index providers such as Standard & Poor’s, Morgan Stanley Capital International, Financial Times Stock Exchange, and Russell Investment publish an Islamic stock index that attracts investors from all over the world.
The country where islamic financing is most common in Europe is England. As a financial centre, london is a magnet for many Muslim investors due to the minor time difference.
The UK’s Muslim population, of roughly two and a half million people, use islamic finance products prolifically. The beginning of islamic finance in the uK dates back to the eighties. Founded in 1982 to operate in the field of housing finance, al baraka international was the first islamic financial institution in the uK.
in 2005, the uK’s first islamic investment bank was established, the European Islamic Investment Bank. Some of the retail and investment banks operating in the UK include Abu Dhabi Islamic Bank, Al Rayan Bank, Bank of London and the Middle East, Gatehouse Bank, and QIB UK.
In 2014, the UK strengthened its position as the centre of islamic financing in europe, when it became the first nonMuslim country to issue sovereign sukuk.
The London Stock Exchange is now a preferred global market for sukuk issuances.
London aims to be the leader in shariacompatible finance in the West. There are five licensed islamic banks in the uK today and over 20 traditional banks offer islamic financial products. apart from this, there are 65 interest-free bonds with a total amount of $50 billion on the London stock exchange, along with Islamic funds of $700 million assets.
after the 2008 crisis, islamic finance began to seem relatively safe to Western banks. Interest-free bonds were a positive signal for new markets. Islamic funds provide an opportunity to reach a large amount of liquidity, and islamic banks enable profits from local Muslim communities.
Outside of the UK, there are just a few initiatives in Europe leading the charge for islamic finance. luxembourg is the first eurozone country to issue national interest-free bills and to offer 49 shariacompatible funds. The first islamic bank in Germany, KT Bank AG, was established in 2015.
In Switzerland, Islamic insurance and takaful services are offered rather than broader islamic financing. There are no swiss laws specifically addressing islamic finance so the islamic finance products are subject to the same regulations as conventional instruments. however, the Swiss legal system is, generally, shariafriendly, given that Swiss contract law is based on two key principles: the freedom of contract and the freedom of form.
With $500 million worth of sukuks issued in Africa in 2018, the continent accounts for only 0.5% of the world’s sukuks in circulation. however the large Muslim population, currently underbanked and underserved, could be “a solid foundation on which islamic financial assets, and therefore profits, can grow rapidly,” say Moody’s analysts.
One clear example is Nigeria’s Sterling Bank, whose Islamic banking section experienced a 24% growth in profits last year despite a 16% contraction in total assets in the Nigerian commercial banking segment, according to Moody’s.
in south america, islamic finance is just getting started. With the opening of Trustbank Amanah in Suriname in 2017, the region had its very first islamic bank.
The other South American country opening up to islamic finance is Guyana, with the support of the Islamic Development Bank. While there is currently no regulation on islamic finance in Guyana, and also no Islamic bank, the country received $900 million in financial and technical assistance from the Islamic Development Bank over a three-year period, starting in 2018. The money will be used to develop Guyana’s economic infrastructure, rural development, educational capacities and improve trade and competitiveness. The establishment of Islamic banking institutions is planned for later.
When the bulls are running, success stories are everywhere. however, in complex and volatile times, the innovative alone lead the charge.
Cornèr Bank (Overseas) Ltd, ever a pacesetter, pioneer, and catalyst for positive change in The Bahamas, has just been awarded the Best Private Banking Services - The Bahamas 2020 title. It’s in recognition of Cornèr Bank’s reputation as a beacon of banking excellence and innovation, developing services and educational materials that give Bahamas-based investors local access to the full gamut of global investment opportunities, opening the door to a new financial era in the islands.
Cornèr Bank’s proven track record of bringing new and awardwinning offerings to the bahamian financial sector, as well as educational services designed to inform new clients about these products’ use, have made the bank the clear choice.
Every successful pioneering expedition launches from a wellstocked base camp - and cornèr bank’s bahamian affiliate is no different. Founded in 1952 in Lugano, Switzerland’s third-largest banking centre, the Cornèr Bank Group focused on building a strong financial foundation to keep the ship sailing smoothly, even in rough seas. Today it boasts an exceptional Tier 1 capital ratio of 24.4% - three times higher than the minimum regulatory requirements - and has been listed first in financial soundness on The Banker’s Top 1000 World Banks list for four consecutive years.
From this excellent footing, Cornèr Bank Group has consistently extended its range of services and areas of operation to match increasingly global demand for sophisticated and seamless banking solutions. its extensive list of financial services is offered from Switzerland, London, Milan, Vaduz, and of course, through Cornèr Bank (Overseas) Limited, Nassau, the capital city of The Bahamas. From its parent company’s deeply-rooted foundation, cornèr bank bahamas has been successfully providing financial solutions in the islands since 1996.
The Bahamas has long been a prominent financial hub in the western hemisphere, thanks to its proximity to both North and Latin America, its stable democracy, and favourable tax environment (though no doubt the gin-clear waters, bone-white beaches, and balmy weather played a role as well). Without taxation on capital gains, inheritance, or income, The Bahamas has been a private banking nexus for decades — the benefits of which had only been available to foreign residents. Despite serving wealthy foreigners in the country’s extensive financial services industry for more than half a century, Bahamians had been limited to investing within their island’s coastlines. On the horizon would come unprecedented relaxations in the archipelago’s foreign exchange regulations, opening the door for Cornèr Bahamas to lead the charge.
In 2018, The Central Bank of The Bahamas relaxed its restrictive regulations, and overnight, the doors to world markets were thrown open. Native holders of Bahamian dollars were liberated and able to finally reap the benefits the world of trading and investing could offer. True to its pioneering spirit, Cornèr was poised and ready to guide Bahamians through the unfamiliar waters of the international markets. The bank had spent two years preparing to offer to Bahamians its online trading platform, Cornèrtrader, and its 2018 launch marked the first time a local firm had offered real-time access to the NYSE and the NASDAQ. Not only was Cornèr Bahamas prepared to welcome new clientele, but the bank also positioned itself as a financial hub for newcomers navigating the markets, proving itself to be a true cornerstone of the Bahamian community.
Cornèr Bank (Overseas) Ltd’s CEO, Christine Russell — a Bahamian national herself, and a seasoned veteran of the bahamian financial sector — best articulates the significance of this achievement:
“The advent of Cornèrtrader marked a milestone in Bahamian financial culture, as it empowers Bahamians like never before. For the first time, we gave Bahamians and residents alike the opportunity to engage in any of the world’s major stock exchanges from virtually anywhere - in their homes or even on the beach.”
To a country previously limited to a shallow pool of relatively undiversified investment offerings, this was a giant leap forward.
“With a click of a mouse, Bahamians could easily purchase anything they wanted on Amazon, but until Cornèrtrader, they could not say the same for a share of Amazon itself. No longer are we just consumers, now we can be owners too.”
In a further show of exemplary commitment to their clientele, Cornèr Bank (Overseas) offers the learning tools necessary to use its new and exciting products. At the Bahamian launch of Cornèrtrader, the bank’s director Luca Salzborn summarised the efforts, saying, “we are committed to offering to all our existing and prospective clients’ continuous education with seminars or one-to-one meetings about markets and the use of our platform, as we believe that a key element for successful investing lies in mastering the technical and financial aspects that go with it”.
For Bahamas-based investors less eager to dive into markets unassisted, Cornèr Bank (Overseas) offers additional types of accounts alongside its Cornèrtrader platform that provide users with assistance and recommendations tailored to their preferences. holders of Investment Advisory Accounts receive proposals based on their personal level of risk aversion and investment goals. To take it further, Cornèr Bank (Overseas) offers Discretionary Investment Management Accounts, which are managed according to the client’s risk profile.
“I would like to thank the International Investors Awards, and the subscribers of International Investors magazine, for recognising Cornèr Bank’s continued leadership and excellence,” says Russell. “It’s an honour and a privilege to accept this award on behalf of my organisation — but the true reward comes from knowing that we are making a real difference in the quality of our clients’ investment options.”
Cornèr Bank (Overseas) Ltd’s product innovation, consistency in client communication, transparency and overall client satisfaction will continue to propel the bank not just to the top of the award podium, but into the future, setting the pace for financial services worldwide.
by Cameron Williams
Just a few years ago, there used to be a running joke about robots taking over the world. Back then, if I were to say that robots would be the norm for how we manage our money in the future, no one would have taken me seriously!
Today, in its most literal sense, technology-based wealth management is actually starting to take over many of the mundane tasks related to how we manage our money. These technologybased money management tools are called “Robo-Advisors,” and they already represent a nearly trillion-dollar industry within investing and wealth management.
Not to be confused with a walking, talking robot, a robo-advisor is a technologybased algorithm that builds a custom investment portfolio for you based on a few common investing questions. The algorithms are built with the aid of financial experts and tech gurus, to automate some of the basic tasks in wealth management.
here are some example questions asked when setting up a robo-advisor account. These questions help the technologybased algorithm automatically customise an investment portfolio for you.
• How much investing experience do you have?
How soon will you need the invested money?
• How tolerant are you of market volatility?
• How comfortable would you feel if your portfolio dropped 10% in value in the short term?
What is the primary objective of your investments? (growth, income, maintain value, etc.)
• Do you have other invested assets?
These questions are used as binary indicators to the robo-advisor algorithm. Your responses will direct the robo-advisor to build a portfolio that is in your best interest and customised to your investing style based on your responses.
For example, you may be a young investor just starting out and looking for a diversified portfolio with moderate risk. This will be noted upon answering some investing questions, and the robo-advisor will automatically build you an investment portfolio that is well-diversified among different companies and investments, as well as create a portfolio with moderate risk tolerance.
Examples of some of today’s reputable robo-advisors today are:
• Wealthfront
• Betterment
Acorns
• Wealthsimple
Many of these robo-advisors give their clients access to financial experts in case you have a more complicated question. In short, robo-advisors save customers and investment banks time and money.
It’s no question that robo-advisors make investing more convenient, costeffective, and less time consuming to manage.

It’s safe to say that robo-advisors are more popular among younger generations, due to their natural understanding of technology, having grown up with smartphones and voice assistants.
In fact, that may be a clear indicator of how the growth of robo-advisors will trend globally with younger generations becoming more dominant as the years progress. Consider the following market trends, courtesy of Statista.com.
ASSETS UNDER MANAGEMENT
In 2017, the reported assets under management within the robo-advisor segment was $297.72 billion. Today, the total assets under management in 2020 is projected to be $987.49 billion or over three times as much as reported in 2017.
By 2024, the total assets under management within the robo-advisor segment is projected to be $2.487 trillion!
In the year 2017, the total number of users within the robo-advisor segment was approximately 42.78 million. Today, the total number of reported users for 2020 is 224.52 million. That’s over five times growth in just three short years.
The number of total robo-advisor users in the year 2024 is projected to be approximately 436.33 million users, or almost double what it is today.
AVERAGE ASSETS UNDER MANAGEMENT PER USER
While the total assets under management and total number of robo-advisor users have been on a drastic upward trend, the average amount of assets under management per user has slightly declined since 2017 from $6959 down to $4398. It’s expected to grow to about $5700 by the year 2020.
What does this data suggest? More people can invest today due to the growth and convenient features of robo-advisors. Naturally, as younger investors enter the market, they will likely have less money
available to invest. Fortunately, one of the goals of robo-advisors in the first place is to allow more people to invest with less required money to begin.
The five countries that have the most assets under management within the robo-advisor segment are:
1. The United States - with $682.73 billion under management
2. China - with $74.57 billion under management
3. Japan - with $30.32 billion under management
4. The United Kingdom - with $18.23 billion under management
5. Italy - with $15.27 billion under management
As you can see, the potential growth opportunity for robo-advisors is massive, and one that is likely to spread to more countries extremely fast. The stock market alone has a total market capitalisation size of approximately $70.75 trillion, leaving a lot of untouched territory for the roboadvisor industry.
suffice it to say that we’re still in the beginning stages of the global impact of robo-advisors.
Are robo-advisors taking the place of the traditional financial advisor? in some cases, yes. But I would consider the growing robo-advisor trend more of a shift in how business is done than anything else.
Traditional financial advisors will most likely always be needed.
Janine Menasakanian, the director of Key Accounts at one of the most famous investment companies today, Vanguard, believes that “Robo is great for simple, self-directed work, but not for complex planning activities.”
For now, I think it’s safe to say that robo-advisors are great for basic wealth management activities such as portfolio diversification, building customised investment plans to your personal risk tolerance, portfolio rebalancing, and tax-loss harvesting. Most robo-advisors are gateway products for investment companies that offer their robo-advisor customers the ability to set up a meeting with a human financial expert for more complex planning.
It’s a great option to start investing if you don’t have much experience, don’t have extra money to pay for a costly advisor, and don’t have complex investing needs like detailed estate planning, tax planning, and business succession plans. Roboadvisors are here to stay and will continue growing at an accelerated pace.
















By Rob McNamara
2020 will go down in history as a hard blow to an already weakened economy, but what will be its legacy for investor confidence?
By September 2019, Brexit had already made its mark on the UK economy.
According to the Decision-Maker Panel (DMP), set up by Nottingham and Stanford universities, investment had reduced steadily by around 11% while productivity had decreased by between 2 and 5% since the referendum result hit the headlines. Analysts were bracing for hard times, but at least refreshed voter confidence in the Conservative agenda had put a little fire back into the negotiation process. Investors might have begun feeling like perhaps things were on the up.
in January 2020, The investor confidence Index had jumped by 21% to its highest level since November 2015, with increasing interest in UK investment. Traction was steady and the fearmongering had died down somewhat across the media. Boris
Johnson’s government had it all under control, we were reassured, and they were well on their way to ‘Get Brexit Done’.
There was even optimism from the 3000 chief financial officers surveyed by the DMP, working in collaboration with the Bank of England, which indicated that investment might be set to increase. There was a real expectation that investment could grow by as much as 4.6%, an increase from 2.4% from the three months preceding. It would be absurd to claim that uncertainty had been significantly dialled down, but investors were beginning to see some strong reasons to invest once more in the UK.
The last thing the government needed was a global pandemic. Perhaps this is why it took so long to accept the magnitude of this new virus; they simply could not believe their bad luck. having fought so hard to inject certainty back into the economy and reassure the public
that they had this all under control, the universe threw a corona-shaped curveball. The catastrophic loss of life has been devastating. The economy is a secondary victim.
The Bloomberg Brexit Barometer tracks economic well-being in the United Kingdom and is updated daily, using weather icons to indicate how inclement, or not, the state economy is since the vote to leave. Today it shows a dark cloud with a flicker of gif lighting protruding.
There can be no denying the fact that much of the economic trouble right now stems from the early impacts of COVID-19 and the lockdown, and not from Brexit itself. Yet both COVID-19 and Brexit mean uncertainty, and uncertainty is what investors are agitated about. The combination is intimidating.
The markets have recovered a little since their initial crash in March, but there is a real risk that a second crash is on its way.
As tensions rise between the US and China and another wave of redundancies across europe looms as governments’ fiscal interventions tail off, a hard Brexit may just be enough to cause another sharp decline in investor sentiment. 2020 seems to be a triple threat year.
Face-to-face negotiations resumed last week between Britain and the EU after three months of video conferencing. They quickly broke down as discussions reached an impasse, and the two opposing sides failed to reach even basic consensus on the terms of the divorce. Investors fear now that crashing out of the EU will result in defaulting to World Trade Organisation terms, which means unfavourable tariffs and quotas. For many, this makes other markets outside of the UK look far less uncertain, and thus alluring.
Asia is set to continue to benefit from a tumultuous Europe.
Nausicca Delfas, the Financial Conduct Authority’s Director of International, was quoted in a recent interview with Bloomberg, “if the two sides fail to provide companies cross-border access, known as equivalence, equity and derivativestrading business could face disruption. European investors might also be required to trade shares inside the bloc unless they’re given access to U.K. markets”.
Furthermore, with a continued lack of information from the negotiations about what it will cost to do business once Britain and the EU part ways, plenty of investors will see this uncertainty as a reason to keep their money away from such worrisome markets.
In short, maybe. For some investors, the opportunity to buy cheap stock right now might be very attractive. If the second crash does come as expected, it could be a prime time to pick up a few bargains. It’s still a brave person’s game though and buying shares on the decline isn’t always going to net you the long-term gains you’re looking for.
Diversification across a number of industries, especially renewable energy and technology, both of which showed strong potential prepandemic, might offer a little light at the end of the 2020 tunnel.
Uncertainty seems to be the presiding theme this year, and there is little indication this is set to change any time soon. For many, pragmatism is the new normal and lack of information and clarity from the Brexit negotiations will only prolong that. It might be a year to wait and watch to see how things unfold, with investors both inside and outside of the UK taking advice to not hold their breath. Perhaps we’ve had enough uncertainty already to last us a lifetime.
Access Bank Plc. is a leading full-service commercial bank with a network of more than 600 branches and service outlets, spanning three continents, 12 countries and 31 million customers.
Listed on the Nigerian Stock Exchange since 1998, access bank is a diversified financial institution which combines a strong retail customer franchise and digital platform with deep corporate banking expertise and proven risk management and capital management capabilities. The bank serves its various markets through four business segments: Retail, Business, Commercial and Corporate. The bank has over 900 000 shareholders (including several Nigerian and international institutional investors) and has enjoyed what is arguably Africa’s most successful banking growth trajectory in the last twelve years.
Following its merger with Diamond Bank in March 2019, Access Bank became one of Africa’s largest retail banks by retail customer base.
As part of its continued growth strategy, Access Bank is focused on mainstreaming sustainable business practices into its operations. The bank strives to deliver sustainable economic growth that is profitable, environmentally responsible and socially relevant, helping customers to access more and achieve their dreams.
Italy’s ARCA Fondi SGR is an asset management company that is also authorised to manage individual portfolios of institutional clients. The company was born from the history and experience of ARCA SGR, founded in 1983 by 12 popular banks.
The distributor network is made up of more than 120 financial regulated institutions operating across more than 8000 branches and on-line channels, with a team of independent financial advisors. The company has grown in time, expanding its network of distributors and serving more than 800 000 final clients. With one of the largest distribution networks in the Italian asset management industry and the long-standing presence of its brand in the marketplace, ARCA Fondi SGR is ranked by Italian investors as one of the most well-known asset managers in Italy.
Since 2006, AvaTrade has been one of the most regulated brokers in the world. Licensed in nine jurisdictions and running local offices around the world, it provides ultra-low spreads on over 1000 trading instruments across a range of marketleading trading platforms.
awarded ‘best affiliate programme 2020’ by International Investor, AvaTrade also offers a partners programme, ‘AvaPartner’. With a wide selection of partnership models from introducing brokers, online affiliates, trading academies and service providers, AvaPartner contains attractive payment structures, robust customer relationship management (CRM) and effective risk management tools. With over 90 000 registered partners, more than $250 million paid in commissions and up to $1000 CPA or 40% revenue share – it’s no wonder so many partners choose AvaPartner!
Founded in Chile in 1944 as Banco Israelita, Banco Internacional now uses a nationwide network of 12 branches and four business centres, staffed by over 500 employees, as well as a suite of digital platforms to bring it closer to its customers and help it lead the corporate segment in the Chilean banking industry.
Since 2016, Banco Internacional has been the fastest-growing bank in Chile, with a business model that allows for diversification between strategic segments, revenue sources and high organic growth.
Banco Internacional is majority-owned by Inversiones La Construcción SA, a successful track-record and proven financial stability, which bought the bank in 2015. Good governance, which is also ensured through a reputable board and a solid management team with experience in the industry.
The bank’s values include delivering quality to every customer with the highest ethical standards. Banco Internacional incorporates sustainability as a fundamental part of its management through four pillars:
- Culture of service and ethics
- Responsible investment
- Inclusion, quality and access
- Contribution to public debate
Launched in January 2013, Bank Nizwa offers the people of Oman a unique banking experience that combines Shariacompliant products and services with today’s dynamic financial requirements.
Over the past seven years, the customer base has grown steadily as more people seek an alternative solution to conventional banking. As Islamic banking gains momentum in Oman, Bank Nizwa continues to offer reliable competitive propositions for customers looking to lead financially secure lifestyles.
The bank currently offers a suite of financing, savings and investment products for individual customers. The bank also has an extensive portfolio of services catering to SMEs, corporate and commercial customers, while providing tailored products for investment banking and global markets. Bank Nizwa has been consistently introducing forward-thinking products and services, such as its online and mobile banking solutions.
Bank Nizwa launched its Strategy 2020, a five-year vision to become the sultanate’s leading islamic financial institution. The strategy focuses on five pillars of development including financial performance, technological advancement, market share, team and culture, in addition to a progressive organisation.
Guided by the principles of Sharia, and a firm dedication to giving back, bank nizwa has taken a leading role in promoting the social development of local communities.
Banner is an experienced asset and funds manager, specialised in debt and equity products in the Australian real estate market. Banner was started in 2010 by Andrew Turner (CEO) and a small group of initial investors and chiefly invested the funds of its principals. The range of investors has organically expanded to institutions, corporates, and other funds. All the original investors remain. This organic and gradual growth guided and continues to guide the investment principles of ‘putting the investor first’, through responsiveness, preserving capital and earning a return.
banner is a registered provider of financial product in the highly regulated Australian financial services and funds management sector. The head office is in Melbourne, with a sydney office, principals located and active in Japan and Singapore. Its investors are mostly located in Singapore, hong Kong, Japan, Europe and Australia.
The Banner funds have funded property projects valued at over AUD8 billion. A majority of Banner’s investors are nonresidents, and it is well-versed in dealing with the needs of off-shore investors.
Cornèr Bank (Overseas) Ltd. has been a paragon of excellence in the world of private banking for over 20 years. Built on a solid foundation of constant innovation, strong financial positioning, and capital soundness, Cornèr Bank offers its globally diversified clientele competitive and tailored solutions in an increasingly complex world.
Cornèr Bank brings expert knowledge and a wide range of top-tier financial services to serve not only international clients but to Bahamians and residents alike. Through consistent product development, cornèr has diversified its offerings to include the Cornèrtrader platform and an array of investment services. Cornèr Bank continues to experience remarkable growth and increased stability as it takes pride in maintaining its stellar international reputation.
cornèr bank (overseas) ltd. is an affiliate of Swiss-based parent company, Cornèr Bank Ltd, and is licensed with and regulated by both the Central Bank of The Bahamas and the Securities Commission of The Bahamas.
ICU is an independent asset management and investment advisory firm specialising in the emerging markets of Central and Eastern Europe.
Founded in 2006 by senior investment professionals from ING, ICU is Ukraine’s leading asset manager with over $500 million in assets under management. Their current strategy includes significant allocations to venture capital and distressed debt.
ICU’s veteran investment team has experience in private equity & venture capital, high yield corporate debt, distressed debt, restructurings and other special situations across a number of emerging markets. Investment decisions are supported by robust macroeconomic and sectoral analyses from the firm’s inhouse team of research economists.
ICU aims to provide their clients with superior risk-adjusted returns across a number of asset classes. The firm is expanding its reach into key European markets via a combination of organic growth and acquisition and continues to expand the range its investment offerings.
Private Wealth Systems is a global financial technology company that is solving the financial industry’s structural challenges of data, scale, and security in order for those who manage complex investment portfolios to have the information they need to make the most informed decisions.
The team’s collective experience includes designing and building three of the leading family office investment reporting and portfolio accounting systems.
The company’s private cloud suite of multi-asset, multi-manager investment software includes account aggregation, data reconciliation, performance calculation and client reporting that supports even the most complex global balance sheets.
Taipei Fubon Bank, a 100% owned subsidiary of Fubon Financial holdings, was created through the merger of Taipei Bank and Fubon Bank. The merger, formally completed on the first of January 2005, was the first in Taiwan’s banking history involving a state-owned bank and a private bank. As of April 2020, Taipei Fubon Bank had total assets of NT$3.168 trillion and operated a total of 127 domestic branches and five overseas branches plus one office. it has the most branches in Taipei of any private bank in Taiwan.
backed by a highly efficient channel platform, an unrivaled line of products and services, and extremely effective operations, Taipei Fubon Bank is determined to emerge as the preferred financial strategy partner for customers in the Greater China market and move steadily toward the vision of becoming “a top regional bank in Asia.”
The Tickmill Group, consisting of Tickmill Ltd, Tickmill UK, Tickmill EU and Tickmill Asia, provides a secure and professional trading environment where clients can trade a plethora of instruments including forex, stock indices, precious metals, bonds and energies. With innovative tools and advanced technology, Tickmill facilitates trading for professional, institutional and retail clients across the globe, giving access to over 80 financial instruments, spanning four asset classes.
Tickmill UK Ltd is regulated by the UK Financial Conduct Authority (License Number: 717270). Tickmill Europe Ltd is regulated by the Cyprus Securities and Exchange Commission (License Number: 278/15). Tickmill Ltd is regulated by the Financial Services Authority of Seychelles (License Number: SD008). Tickmill Asia Ltd is regulated by the Financial Services Authority of Labuan Malaysia (License Number: MB/18/0028).