Securities Analytics Research
Verifiably Independent
U.S. Securities Litigation Risk Trends – July 2026
August 19, 2026
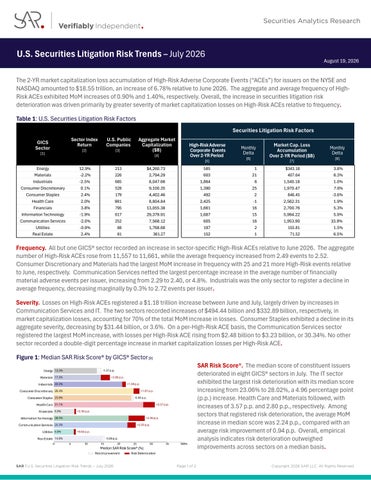
The 2-YR market capitalization loss accumulation of High-Risk Adverse Corporate Events (“ACEs”) for issuers on the NYSE and NASDAQ amounted to $18.55 trillion, an increase of 6.78% relative to June 2026. The aggregate and average frequency of HighRisk ACEs exhibited MoM increases of 0.90% and 1.40%, respectively. Overall, the increase in securities litigation risk deterioration was driven primarily by greater severity of market capitalization losses on High-Risk ACEs relative to frequency. Table 1: U.S. Securities Litigation Risk Factors Securities Litigation Risk Factors GICS Sector [1]
Sector Index Return [2]
U.S. Public Companies [3]
Aggregate Market Capitalization ($B) [4]
High-Risk Adverse Corporate Events Over 2-YR Period [5]
Energy Materials Industrials Consumer Discretionary Consumer Staples Health Care Financials Information Technology Communication Services Utilities Real Estate
12.9% -2.2% -2.5% 0.1% 2.4% 2.0% 3.8% -1.9% -2.0% -0.9% 2.4%
213 226 685 528 179 981 795 617 252 88 61
$4,260.73 2,794.29 8,047.66 9,100.35 4,402.46 8,804.84 13,055.38 29,379.91 7,568.12 1,768.68 361.27
585 603 1,864 1,390 492 2,425 1,661 1,687 605 197 152
Monthly Delta [6]
Market Cap. Loss Accumulation Over 2-YR Period ($B)
Monthly Delta
$343.18 407.64 1,540.18 1,970.47 846.45 2,562.31 2,700.76 5,994.22 1,953.90 155.81 71.52
3.8% 6.3% 1.0% 7.6% -3.6% 1.9% 5.3% 5.9% 33.9% 1.5% 6.5%
[7]
1 21 6 25 2 -1 16 15 16 2 1
[8]
Frequency. All but one GICS® sector recorded an increase in sector-specific High-Risk ACEs relative to June 2026. The aggregate number of High-Risk ACEs rose from 11,557 to 11,661, while the average frequency increased from 2.49 events to 2.52. Consumer Discretionary and Materials had the largest MoM increase in frequency with 25 and 21 more High-Risk events relative to June, respectively. Communication Services netted the largest percentage increase in the average number of financially material adverse events per issuer, increasing from 2.29 to 2.40, or 4.8%. Industrials was the only sector to register a decline in average frequency, decreasing marginally by 0.3% to 2.72 events per issuer. Severity. Losses on High-Risk ACEs registered a $1.18 trillion increase between June and July, largely driven by increases in Communication Services and IT. The two sectors recorded increases of $494.44 billion and $332.89 billion, respectively, in market capitalization losses, accounting for 70% of the total MoM increase in losses. Consumer Staples exhibited a decline in its aggregate severity, decreasing by $31.44 billion, or 3.6%. On a per-High-Risk ACE basis, the Communication Services sector registered the largest MoM increase, with losses per High-Risk ACE rising from $2.48 billion to $3.23 billion, or 30.34%. No other sector recorded a double-digit percentage increase in market capitalization losses per High-Risk ACE. Figure 1: Median SAR Risk Score® by GICS® Sector [9]
SAR U.S. Securities Litigation Risk Trends – July 2026
SAR Risk Score®. The median score of constituent issuers deteriorated in eight GICS® sectors in July. The IT sector exhibited the largest risk deterioration with its median score increasing from 23.06% to 28.02%, a 4.96 percentage point (p.p.) increase. Health Care and Materials followed, with increases of 3.57 p.p. and 2.80 p.p., respectively. Among sectors that registered risk deterioration, the average MoM increase in median score was 2.24 p.p., compared with an average risk improvement of 0.94 p.p. Overall, empirical analysis indicates risk deterioration outweighed improvements across sectors on a median basis. Page 1 of 2
Copyright 2026 SAR LLC. All Rights Reserved.